

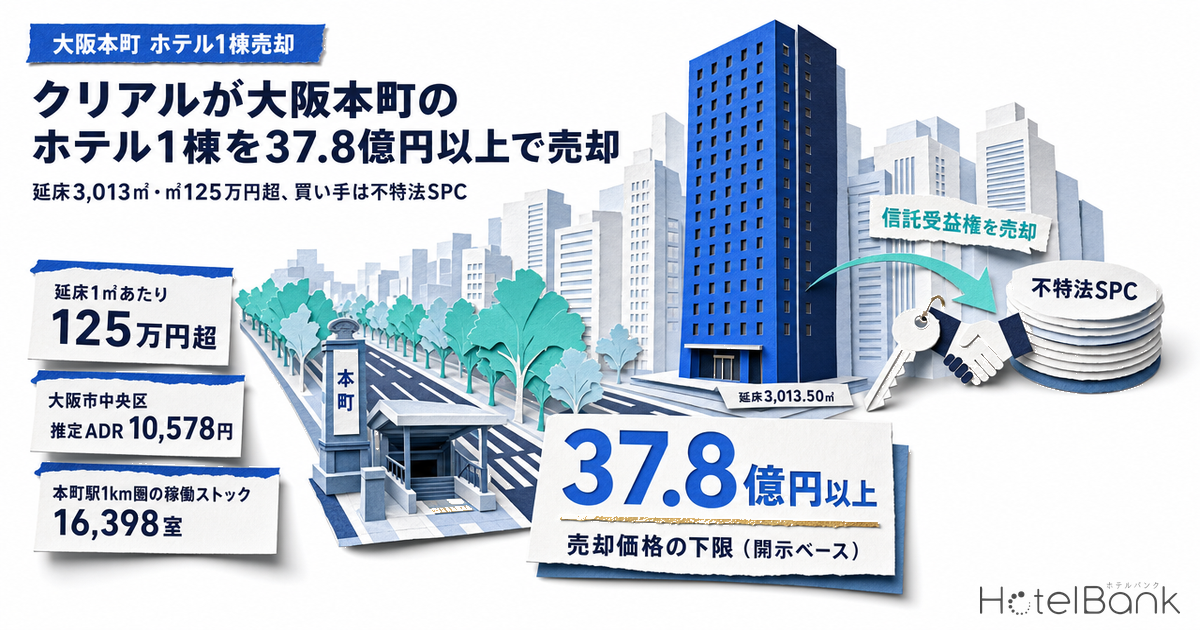
On October 8, 2026, CREAL Inc. (TSE Growth: 2998) disclosed that it will sell the trust beneficiary interest in Garner Hotel Osaka Honmachi Midosuji in Chuo-ku, Osaka (completed March 2018, steel frame, 13 floors, gross floor area 3,013.50 m²) to a godo kaisha that conducts specified joint real estate business under the Real Estate Specified Joint Enterprise Act. The price was withheld on confidentiality grounds, but the disclosure states that it is at least 10% of the company’s consolidated net sales of ¥37,795 million for the fiscal year ended March 2026. That puts the floor at ¥3.78 billion, or more than ¥1.25 million per m² of floor area. In the same Honmachi district, CREAL had just raised ¥3.423 billion from individual investors this summer for a hotel building in Kita-Semba, fully subscribed. This article starts from what the October 8 disclosure reveals about the deal, then layers on the design of the Kita-Semba fund, the estimated settled ADR in Osaka’s Chuo-ku one year after the Expo, and the room stock within 1 km of Honmachi Station, to read, through price per m² and required RevPAR, a deal in which a fractional-ownership vehicle becomes the buyer of a whole hotel.
Metric Definitions Used in This Article
- ADR (Average Daily Rate) = an estimated settled room rate (tax-exclusive equivalent), calculated by applying a segment-specific adjustment factor to the lowest published plan level on OTAs (per room, double occupancy, tax-inclusive). Checked against property-level results disclosed by listed hotel REITs (91 properties, most recent 3 months), the median error is about 7%. These are estimates and differ from each property’s actual settled prices and accounting figures. Area-level ADR is the median across covered properties (the level of a typical property in the area).
- OCC (Occupancy) = the share of rooms sold out of total rooms in the area (an estimate based on OTA sales inventory; consistency checks against monthly REIT disclosures show accuracy within a few points). Estimated OCC in this article is shown together with “N properties / M rooms covered (based on listings on major booking sites)”.
- RevPAR (estimated) = the product of the ADR and OCC above. It is a product of two estimates, not an actual result.
- Room stock = the total rooms of properties within a radius of Honmachi Station (34.6827°N, 135.4989°E) with observed selling prices in the most recent 3 months (July-September 2026). Duplicates from renamings of the same building were merged.
- Data sources = MetroEngines Research & Consulting (price, inventory and property data), CREAL Inc. timely disclosures and official fund page, MLIT Real Estate Information Library, and IR materials of each investment corporation.
- — ¥3.78bn or more, above ¥1.254M per m² of floor area: the sale price of Garner Hotel Osaka Honmachi Midosuji is undisclosed, but a floor follows from the disclosure’s “at least 10% of consolidated net sales.” The buyer is a specified-joint-enterprise SPC established in August 2025.
- — 6.4% of the 7.4% annual yield comes from the sale: the Kita-Semba fund in the same Honmachi area (168 rooms, ¥7.21bn total, LTV 49.7%) is built on the assumption of handing the asset to the next buyer within three years.
- — Chuo-ku estimated ADR ¥10,578 (-34.0% YoY): estimated OCC in September 2026 held at 82.9% (130 properties / 19,720 rooms), for an estimated RevPAR of about ¥8,800.
- — Required RevPAR of roughly ¥7,300-¥11,400: at a 4.5% required yield and 40% GOP margin it is about ¥8,200, inside the current market level. At a yield of 5.0% or higher, or a 35% GOP margin, it exceeds the market level.
- — 80% of the 16,398 rooms within 1 km of Honmachi Station opened in 2016 or later: the roughly 13,100 rooms built in that same supply wave form the pool of candidates for conversion and sale.
The Deal as Disclosed: Price Withheld, but the Floor and Price per m² Are Fixed
Start with the October 8 timely disclosure itself. At its board meeting that day, CREAL resolved to sell, as real estate held for sale, the trust beneficiary interest in a hotel building in Chuo-ku, Osaka (completed March 2018, steel frame, 13 floors above ground, gross floor area 3,013.50 m²). The buyer is Centaurus GK (ケンタウルス合同会社). Its representative member is CR Carnation, a general incorporated association; its head office is in Ginza, Chuo-ku, Tokyo; its business is listed as “specified joint real estate business under Article 2, Paragraph 8 of the Real Estate Specified Joint Enterprise Act”; and it was established on August 22, 2025. Capital, personnel and business relationships with CREAL are all stated as “not applicable.” The contract was signed on October 8, 2026, and handover is scheduled for December 15, 2026.
On price, the disclosure says CREAL “refrains from disclosing it due to a contractual confidentiality obligation with the buyer,” while stating that “the sale price is at least 10% of the Company’s consolidated net sales of ¥37,795 million for the fiscal year ended March 2026.” That sentence reflects the materiality threshold under disclosure rules; it is not the price itself. But a floor can be derived from it mechanically: ¥37,795 million × 10% = ¥3,779.5 million, or ¥3.78 billion or more. Divided by the 3,013.50 m² floor area, that is more than ¥1.254 million per m², or more than ¥4.146 million per tsubo (3.3058 m²/tsubo). To repeat, this is a floor (“at least this level”), not the actual price. On earnings, the disclosure says the impact of the sale on the fiscal year ending March 2027 is already reflected in the consolidated forecast published on May 15, 2026.
| Item | Disclosed | Notes |
|---|---|---|
| Property name | Garner Hotel Osaka Honmachi Midosuji | Opening under IHG Hotels & Resorts’ Garner brand announced in January 2025 (IHG release, January 20, 2025) |
| Location / use | Chuo-ku, Osaka City, Osaka / hotel | Street address not stated in the disclosure |
| Completion / structure | March 2018 (Heisei 30), steel frame, 13 floors above ground | Gross floor area 3,013.50 m² |
| Buyer | Centaurus GK | Representative member: CR Carnation (general incorporated association); head office Ginza, Chuo-ku, Tokyo; established August 22, 2025 |
| Buyer’s business | Specified joint real estate business under Article 2, Paragraph 8 of the Real Estate Specified Joint Enterprise Act | Capital, personnel and business relationships with CREAL: “not applicable” |
| Sale price | Undisclosed (at least 10% of consolidated net sales of ¥37,795 million) | Floor of ¥3,779.5 million = over ¥1.254M per m² of floor area, over ¥4.146M per tsubo (our calculation) |
| Schedule | Contract October 8, 2026 / handover December 15, 2026 (scheduled) | Reflected in the forecast for the fiscal year ending March 2027 |
The room count is not in this disclosure. However, CREAL’s July 31, 2026 release announcing the start of operations at three Garner hotels lists the Midosuji building as 168 rooms (completed March 2018); applying the floor price gives at least about ¥22.5 million per room. In its January 20, 2025 release, IHG announced that three properties had opened: “Garner Hotel Osaka Honmachi Station,” “Garner Hotel Osaka Honmachi Midosuji” and “Garner Hotel Osaka Honmachi Kita Semba,” positioning Garner as a “midscale conversion brand.” The timeline of a building completed in March 2018 opening as a Garner in January 2025 shows that this was a conversion of an existing hotel.
The Buyer Is a Specified-Joint-Enterprise SPC: A New Vehicle at the Exit for Whole Hotels
What stands out in this deal is less the price than the type of buyer. The buyer is a godo kaisha running a “specified joint enterprise” (tokurei jigyo) under the Real Estate Specified Joint Enterprise Act (the “Futokuho”), in other words a bankruptcy-remote special purpose company (SPC). Under this scheme, an entity established solely to conduct specified joint real estate business files a notification with the competent minister, accepts investments from participants (investors), and outsources transaction operations to a Type 3 operator and solicitation to a Type 4 operator. MLIT’s explanation of the system describes it as introduced by a 2013 (Heisei 25) amendment to bring private capital into the seismic upgrading and regeneration of buildings. It is the same type of vehicle that CREAL itself described, in its July 16, 2026 release announcing the close of the Kita-Semba fund offering, as a “bankruptcy-remote scheme using Futokuho Type 3 and Type 4.”
That said, all the disclosure tells us about the buyer SPC is its name, representative member, head office, business and date of establishment, and that its relationship with CREAL is “not applicable.” It does not say which firms are involved as the Type 3 and Type 4 operators, whether the offering will target individual investors, or whether the money is institutional, and this article does not speculate. We simply set two facts side by side: a vehicle established in August 2025 appeared just over a year later as the buyer of a whole hotel, and CREAL itself had structured a vehicle of the same type in the same Honmachi area and closed its offering fully subscribed. How transfer taxes and the range of buyers change when the asset traded is a trust beneficiary interest, as in this case, is covered with reference to primary legislation in Three Hotel Acquisition Vehicles: 3.0% Transfer Tax vs. Near Zero.
The Kita-Semba Fund Next Door: Designed to Return 6.4% of 7.4% “Through the Sale”
The closest comparison is the “Osaka Kita-Semba Hotel” fund that CREAL offered from late June to July 15, 2026. According to the official fund page and release, the asset is the 168-room “Garner Hotel Osaka Honmachi Kita Semba” (108 doubles, 59 twins, 1 accessible) at 2-6-8 Awajimachi, Chuo-ku, Osaka, about a 7-minute walk from Honmachi, Kitahama and Yodoyabashi stations. It operates under a franchise agreement with IHG, with hotel operations handled by CREAL Hotels under a management agreement. The offering was ¥3.423 billion (minimum to close: ¥2.5 billion), bank financing ¥3.79 billion, and total fund size (GMV) ¥7.213 billion; the official page shows an LTV of 49.7%, with the debt described as a non-recourse loan. The expected investment period is 36 months, from July 31, 2026 to July 31, 2029, and the expected yield is 7.4% per year (pre-tax), explicitly broken down as 1.0% income gain and 6.4% capital gain.
The key point of this design is that most of the 7.4% per year comes from sale gains. Rent is variable, “fluctuating with the hotel’s operating performance,” and the income component from rent is only 1.0% per year. The remaining 6.4% assumes the property is sold within the three-year expected period: 6.4% × 3 years = 19.2%, applied to the ¥3.423 billion equity, means the design calls for about ¥660 million in sale-gain equivalent (pre-tax, expected) at exit. The official page notes that sale efforts will be made at any time from the acquisition date and the asset sold as soon as a buyer is found; that if it cannot be sold within the expected period, the term may be extended up to a maximum of 60 months; and that part (20%) of the sale gain goes to CREAL as an incentive fee. It also says the actual average investment period of similar funds has been about 17 months. “Handing it to the next buyer within three years” is the premise of the product.
| Item | Published | How to read it |
|---|---|---|
| Offering amount (equity) | ¥3.423bn | Minimum to close ¥2.5bn. Closed fully subscribed (July 16, 2026) |
| Bank financing | ¥3.79bn | Non-recourse loan |
| Total fund size (GMV) | ¥7.213bn | About ¥42.93M per room across 168 rooms (fund-total basis, our calculation) |
| LTV | 49.7% | As shown on the official fund page |
| Expected yield (annual, pre-tax) | 7.4% | 1.0% income + 6.4% capital |
| Expected investment period | 36 months | July 31, 2026 to July 31, 2029. Extension up to 60 months |
| Capital component over 3 years | About ¥660M | 6.4% × 3 years × ¥3.423bn (our calculation, expected) |
The Midosuji building and the Kita-Semba building opened simultaneously under the same brand in January 2025, and CREAL acquired both on July 31, 2026 (Kita-Semba was settled through a specified joint enterprise fund that CREAL structured itself). About two months after acquisition, one is under contract for sale to a specified-joint-enterprise SPC, while the other raised money from individuals through CREAL’s own specified joint enterprise. The kind of vehicle that was set up at Kita-Semba on the premise of “a sale within three years” has, at Midosuji, now ended up on the buy side. As long as fractional vehicles are designed not only to “hold” hotels but also to “pass them on,” such deals may recur rather than happen once.
Estimated Settled ADR in Chuo-ku, Osaka: -34% YoY One Year After the Expo
So where does the lodging market stand in Chuo-ku, Osaka, where a building priced at this level sits? On MetroEngines Research & Consulting’s estimated settled ADR, Chuo-ku (all segments) came in at ¥10,578 in September 2026 (N=193 properties), down 34.0% from ¥16,018 a year earlier (N=188 properties). The prior year was during Expo 2025 Osaka, Kansai (April 13 to October 13, 2025). After peaking at ¥16,534 in October 2025, ADR fell to ¥9,290 in June 2026 and has since been recovering: ¥9,791 in July, ¥10,292 in August and ¥10,578 in September. The 12-month average from October 2025 to September 2026 is ¥11,869, 13% below the previous 12 months (¥13,707). The business hotel segment (N=155 properties) also stood at ¥10,578 in September with a 12-month average of ¥11,858, moving at almost the same level as the ward overall. For a comparison of Osaka’s post-Expo rate decline from both REIT-reported results and estimated settled ADR, see JHR Aug 2026 by Region: Osaka ADR -29.8% at 93.5% Occ, Okinawa -9.9%.
Osaka Prefecture as a whole moved the same way: its September estimated settled ADR was ¥9,310 (N=655 properties), down 32.4% from ¥13,764 a year earlier. Behind this, beyond the Expo payback, is a change in the mix of foreign visitors. JNTO estimates 3,098,900 international visitors in August 2026, down 9.6% YoY; Korea set an August record at 850,500 (+28.7%), while China fell sharply to 418,000 (-59.0%). Estimated OCC in Chuo-ku stayed above 80%: 80.1% in June (122 properties / 19,337 rooms covered, based on major booking site listings), 83.8% in July (128 properties / 19,694 rooms), 82.2% in August (127 properties / 19,287 rooms) and 82.9% in September (130 properties / 19,720 rooms). The pattern is one of giving up rate to win back occupancy. Multiplying the September 2026 ADR of ¥10,578 by OCC of 82.9% gives an estimated RevPAR of about ¥8,800.
| Month (2026) | Est. ADR (Chuo-ku) | YoY | Est. OCC | Properties / rooms covered | Est. RevPAR |
|---|---|---|---|---|---|
| June | ¥9,290 | -35.8% | 80.1% | 122 properties / 19,337 rooms | approx. ¥7,400 |
| July | ¥9,791 | -34.3% | 83.8% | 128 properties / 19,694 rooms | approx. ¥8,200 |
| August | ¥10,292 | -34.6% | 82.2% | 127 properties / 19,287 rooms | approx. ¥8,500 |
| September | ¥10,578 | -34.0% | 82.9% | 130 properties / 19,720 rooms | approx. ¥8,800 |
We also checked the estimated settled ADR of the three Garner hotels in Honmachi. In October 2025 they were at 80-100% of the ward median (¥13,485-¥15,844), and in September 2026 at 75-90% (¥7,995-¥9,537), tracking almost the same path as the median. The Midosuji property being sold was at ¥7,995 in September 2026, the lowest of the three. In other words, the sale price in this deal reflects not Expo-period rates but a building expected to run at post-Expo levels. This feeds directly into how to read the required RevPAR in the next section.
Required RevPAR to Carry ¥1.25M/m² on Variable Rent: Sensitivity to GOP Margin, Yield and Interest Rates
Let us translate the floor price of ¥3,779.5 million derived from the disclosure into the view of a buyer holding the asset on variable rent. According to the Japan Real Estate Institute’s “Japanese Real Estate Investor Survey” (54th, as of April 2026), the expected yield for limited-service hotels is 4.1% in Tokyo and 4.5% in Osaka. We assume three required NOI yields (4.5%, 5.0% and 5.5%), that the owner receives 85% of the hotel’s GOP (gross operating profit) as rent, and three GOP margins (35%, 40% and 45%). The room count is not in this disclosure, so we use the 168 rooms stated in CREAL’s July 31, 2026 release. Dividing the required annual revenue by this room count and 365 days gives the RevPAR required to justify the floor price.
| Required NOI yield | Required NOI | GOP margin 35% | GOP margin 40% | GOP margin 45% |
|---|---|---|---|---|
| 4.5% (Osaka expected yield) | ¥170M | Revenue ¥572M / RevPAR ¥9,300 | Revenue ¥500M / RevPAR ¥8,200 | Revenue ¥445M / RevPAR ¥7,300 |
| 5.0% | ¥189M | Revenue ¥635M / RevPAR ¥10,400 | Revenue ¥556M / RevPAR ¥9,100 | Revenue ¥494M / RevPAR ¥8,100 |
| 5.5% | ¥208M | Revenue ¥699M / RevPAR ¥11,400 | Revenue ¥611M / RevPAR ¥10,000 | Revenue ¥544M / RevPAR ¥8,900 |
Set against the ward’s market level, the combination of a 4.5% required yield and a 40% GOP margin gives a required RevPAR of about ¥8,200, within Chuo-ku’s estimated September 2026 RevPAR (about ¥8,800). Raising the required yield to 5.0% lifts it to about ¥9,100, and if the GOP margin stays at 35% it rises to about ¥10,400, somewhat above the ward’s post-Expo market level. Put differently, even the floor price only works when the conditions line up: a stable GOP margin of 40% or more and a yield target in the mid-4% range. If the actual price is above the floor, the required earnings level is higher still. On the other hand, measured against a period like October 2025, when the ward’s estimated ADR was in the ¥16,500 range, there was ample headroom over this required level. It seems natural to read the buyer as looking at the recovery potential: how far rates can come back from the post-Expo trough.
We also check the yield to equity holders when debt is added. At the same LTV of about 50% as Kita-Semba and interest rates of 1.5%, 2.0% and 2.5%, the cash yield on equity is 7.5%, 7.0% and 6.5% at a 4.5% required NOI yield, and 9.5%, 9.0% and 8.5% at 5.5% (a simple calculation ignoring principal repayment, fees and taxes). The Kita-Semba fund’s offer of 7.4% per year, as 1.0% income plus 6.4% capital, can be read as an allocation that uses most rental income to cover interest and operating and management costs, and shifts investor returns toward sale gains. For lenders, this is a structure in which interest coverage under variable rent tracks RevPAR, so the month-to-month swing in the ward’s estimated RevPAR (about ¥7,400 in June to about ¥8,800 in September) maps directly onto the range of a stress scenario.
The Honmachi Station Location: Land Prices +13.8%, Commercial Zone at 1000% FAR, and the Gap to Replacement Cost
To test the price from another angle, consider the location figures. According to MLIT’s Real Estate Information Library, the 2026 official land price at the benchmark site “Honmachi 3-chome 22-1 et al.,” about 380 m from Honmachi Station, is ¥4,610,000 per m², up 13.8% YoY. That follows ¥3,590,000 in 2024 (+11.5%) and ¥4,050,000 in 2025 (+12.8%), three straight years of double-digit gains. “Nishi-Honmachi 1-chome 19-3,” about 230 m west, stands at ¥2,950,000 (+16.6%), and “Bingomachi 3-chome 28 et al.,” about 330 m east, at ¥10,600,000 (+15.0%); benchmark sites around the station all rose 13-17%. The Honmachi Station site is zoned commercial with an 80% building coverage ratio and 1000% floor area ratio, and station ridership per the National Land Numerical Information (station passenger counts) was 200,963 per day in FY2023 (219,137 in FY2019).
| Zoning | Commercial district |
| Building coverage / floor area ratio | 80% / 1000% |
| Official land price (Honmachi 3-chome), 2026 | ¥4.61M/m² (+13.8%) |
| Honmachi Sta. ridership, FY2023 | 200,963/day |
| Operating stock within 1 km | 107 properties, 16,398 rooms |
| Land (¥4.61M/m² ÷ 1000% FAR) | approx. ¥460K |
| Building (steel frame ¥2.405M/tsubo ÷ 3.3058) | approx. ¥730K |
| Total | approx. ¥1.19M |
| Floor of this sale price | over ¥1.254M |
As a rough guide, the replacement cost, adding the land portion (official land price allocated over floor area at the maximum FAR) to the steel-frame unit cost from the construction starts statistics, comes to about ¥1.19 million per m² of floor area, and this deal’s floor of over ¥1.254 million sits just above it. The existing building is 8 years old and carries depreciation, while a new build would mean a 2-3 year construction period and rising construction costs. That brings the character of the deal into focus: “acquiring an operating building with a track record at a price close to new-build cost.” With land values rising by double digits every year, the rise in replacement cost itself also helps support the price of existing buildings.
The three Garner hotels (including the property being sold) Owned by listed hotel REITs Other operating properties Dashed lines = 500 m / 1 km radius
Room Stock Within 1 km of Honmachi Station: 16,398 Rooms in 107 Properties, 80% Opened Since 2016
What about supply? Listing the properties MetroEngines Research & Consulting tracks within a 1 km radius of Honmachi Station, merging duplicates from renamings of the same building, and defining as operating those with observed selling prices in the most recent 3 months (July-September 2026) gives 107 properties and 16,398 rooms. Narrowing to 500 m gives 29 properties and 4,757 rooms; the Garner Hotel Osaka Honmachi Midosuji being sold and the Kita-Semba building are about 600-650 m from the station. By opening year, 3,099 rooms opened in 2015 or earlier, 6,653 in 2016-2019, 3,822 in 2020-2022 and 2,660 in 2023 or later (164 rooms with unknown opening year), so 80% of the current stock was supplied in 2016 or later. The three years 2017-2019 alone account for 6,288 rooms, or 38% of the total.
| Radius | Operating properties | Rooms | Notes |
|---|---|---|---|
| 500 m | 29 | 4,757 | Mainly large business hotels along the Midosuji Line |
| 1 km | 107 | 16,398 | Of which 6 properties / 817 rooms owned by listed hotel REITs |
| (Reference) Chuo-ku, Osaka | 130 | 19,720 | Population covered by estimated OCC (September 2026, based on major booking site listings) |
The building in this deal (completed March 2018) was built right in the middle of the 2017-2019 supply wave. Buildings from that same wave are now 7-9 years old and entering a phase in which they return to the market through brand conversions and changes of ownership; the roughly 13,100 rooms built since 2016 make up a large pool of future “candidates for conversion and sale.” Heavy supply also means competition, but because building specifications and locations are similar, it is also an area where comparable transactions tend to accumulate for buyers.
The Widening Buyer Base: Scale and Yield Targets of REITs, Private Funds and Specified Joint Enterprises
How far has the range of buyers for a building of this size widened? According to our ownership master (each investment corporation’s IR portfolio list, as of October 12, 2026), listed hotel REITs own 6 properties with 817 rooms within 1 km of Honmachi Station: Invincible Investment Corporation (8963)’s Hotel MyStays Midosuji Honmachi (ホテルマイステイズ御堂筋本町; 108 rooms, acquired August 2018, ¥5,039 million); Ichigo Hotel REIT Investment Corporation (3463)’s The OneFive Osaka Sakaisuji (ザ・ワンファイブ大阪堺筋; 130 rooms, acquired November 2015, ¥1,630 million); Japan Hotel REIT Investment Corporation (8985)’s Hotel Oriental Express Osaka Shinsaibashi (ホテル オリエンタル エクスプレス 大阪心斎橋; 124 rooms, ¥2,738 million; the REIT does not publish property-level acquisition dates in its portfolio list); Nippon Hotel & Residential Investment Corporation (3472)’s APA Hotel Namba-Kita Shinsaibashi-Ekimae (アパホテル〈なんば北 心斎橋駅前〉; 162 rooms, acquired December 2025, ¥4,850 million); Invincible Investment Corporation’s Hotel MyStays Sakaisuji Honmachi (ホテルマイステイズ堺筋本町; 190 rooms, acquired July 2014, ¥2,514 million); and Hoshino Resorts REIT (3287)’s hotel androoms Osaka Hommachi (ホテル・アンドルームス大阪本町; 103 rooms, acquired April 2018, ¥4,238 million). Per room, prices range from ¥12.54 million to ¥46.66 million, with differences in acquisition timing, location and grade showing up directly as differences in unit price.
| Property | Acquirer | Rooms | Acquisition price | Per room | Timing / notes |
|---|---|---|---|---|---|
| Hotel MyStays Midosuji Honmachi | Invincible Investment Corporation | 108 | ¥5,039M | ¥46.66M | August 2018. About 420 m from Honmachi Sta. |
| APA Hotel Namba-Kita Shinsaibashi-Ekimae | Nippon Hotel & Residential Investment Corporation | 162 | ¥4,850M | ¥29.94M | December 2025. About 980 m from Honmachi Sta. |
| Hotel Oriental Express Osaka Shinsaibashi | Japan Hotel REIT Investment Corporation | 124 | ¥2,738M | ¥22.08M | Acquisition date not published by property. About 750 m from Honmachi Sta. |
| Comfort Hotel Osaka Shinsaibashi (Ichigo Shinsaibashi Building) | Ichigo Hotel REIT Investment Corporation | 214 | ¥3,700M | ¥17.29M | August 2023. Appraisal NOI yield 4.7% (disclosure of March 15, 2023) |
| The OneFive Osaka Sakaisuji | Ichigo Hotel REIT Investment Corporation | 130 | ¥1,630M | ¥12.54M | November 2015. About 750 m from Honmachi Sta. |
| Garner Hotel Osaka Honmachi Kita Semba (fund total) | Specified joint enterprise (structured by CREAL) | 168 | ¥7,213M | ¥42.93M | July 2026. Equity ¥3.423bn + debt ¥3.79bn |
| Garner Hotel Osaka Honmachi Midosuji | Specified-joint-enterprise SPC (Centaurus GK) | 168 | ¥3,779.5M or more | ¥22.5M or more | Handover scheduled December 2026. Over ¥1.254M per m² of floor area |
On yield targets: listed REITs are at appraisal NOI yields in the high-4% range (4.7% on Ichigo Hotel REIT’s Shinsaibashi acquisition), and the investor survey’s expected yield for limited-service hotels in Osaka is 4.5%, both of them income-type buyers that “run on rent.” Private REITs hold hotels at a 5.9% share, or ¥473.2 billion (as previously reported in our Private REIT Hotels 5.9%, ¥473.2bn article), with money from regional banks and pension funds flowing into hotels that meet their inclusion criteria. Specified joint enterprises, by contrast, as in the Kita-Semba example, put 6.4% of the 7.4% annual yield into sale gains and raise individual money on the premise of passing the asset to the next buyer within three years. While income-type buyers wait for RevPAR to recover, capital-type vehicles take on the building first and pass it to income-type buyers after the recovery. If this division of labor holds, the exit for whole limited-service hotels in central cities widens a notch further than before. A size of a few billion yen per building is on the small side for a single listed REIT asset and hard for a private fund to structure on a standalone basis, but it fits neatly within a specified joint enterprise offering (¥3.4 billion in this case). If deals like this one increase, the reason will be this fit in size. The distribution of listed REIT yield targets can be checked as property-level cap rates in Hotel REIT Appraisals Hit 1.25x Cost: Cap Rates Across 298 Assets.
Implications for Develop-to-Sell Players: More Exit Options and a Wider Pool of Capital Providers
For companies that develop, hold and sell limited-service hotels in cities, what this deal shows is that there is now one more exit option. Hotels of about 3,000 m² of floor area and 100-something rooms have tended to have a limited buyer pool of operating companies and high-net-worth individuals, because they are small for listed REITs and labor-intensive relative to their size for private funds. When specified-joint-enterprise SPCs join the buyers, a route opens for vehicles pooling small individual investments to acquire whole buildings, and the pool of capital providers for deals of a few billion yen widens. From the lender’s side, as the Kita-Semba example shows, non-recourse loans at an LTV of around 50% are being attached to specified joint enterprise vehicles, and the conditions are falling into place to monitor the interest coverage of variable-rent hotels through the ward’s estimated RevPAR.
On the other hand, capital-type vehicles make “a sale within three years” a premise of the product. When developers sell to such a vehicle, they need to think about price including whether the next buyer (an income-type REIT, private fund or operating company) can take it on at that unit price three years later. This deal’s floor of over ¥1.25 million per m² is a level that works with the combination of Chuo-ku’s post-Expo market RevPAR (about ¥8,800), a 40% GOP margin and a yield in the mid-4% range, and it can be read as a price that factors in recovery potential. As rates and double-digit land price growth continue, the roughly 13,100 rooms built since 2016 within 1 km of Honmachi Station may keep coming to market as candidates for conversion and sale. For operators at any stage of development, holding or sale, the habit of measuring the exit by both price per m² and required RevPAR will likely be the key to turning a wider pool of capital providers into earnings opportunities.
Summary
CREAL’s October 8 disclosure withheld the price but set a floor with a single sentence, “at least 10% of consolidated net sales,” revealing that a building with 3,013.50 m² of floor area will go to a specified-joint-enterprise SPC for at least ¥3.78 billion, or more than ¥1.25 million per m². The Kita-Semba fund in the same Honmachi area acquired 168 rooms for ¥7.21 billion (¥3.42 billion equity + ¥3.79 billion debt) and is designed to return 6.4% of its 7.4% annual yield through a sale within three years. Chuo-ku, Osaka’s estimated settled ADR fell to ¥10,578 in September 2026 after the Expo, down 34% YoY, but estimated OCC held at 82.9% and estimated RevPAR is about ¥8,800. The RevPAR required at the floor price is about ¥8,200 at a 4.5% yield and 40% GOP margin, within the market level; official land prices around Honmachi Station rose 13.8%, and replacement cost is roughly ¥1.19 million per m² of floor area. Eighty percent of the 16,398 operating rooms within 1 km of Honmachi Station opened in 2016 or later, and the buildings from that wave form the pool of conversion and sale candidates. If income-type REITs and private funds and capital-type specified joint enterprises divide the roles between them, the exit for whole limited-service hotels in central cities will be wider than before.
Frequently Asked Questions
Q. Is the “¥3.78 billion or more” sale price a confirmed figure?
No. The disclosure only states “at least 10% of consolidated net sales of ¥37,795 million”; ¥3.78 billion is the floor that can be derived from it. The actual price is undisclosed and may be above the floor.
Q. What is a specified-joint-enterprise SPC under the Futokuho?
Under the Real Estate Specified Joint Enterprise Act, a special purpose company established solely to conduct specified joint real estate business files a notification with the competent minister, accepts investments from investors, and outsources transaction and solicitation operations to licensed operators. It is a bankruptcy-remote structure. CREAL’s Kita-Semba fund is structured as the same type.
Q. Are the ADR and RevPAR figures in this article actual results?
No. They are estimates by MetroEngines Research & Consulting based on published OTA prices and sales inventory, with a median error of about 7% when checked against REIT-disclosed results. They differ from each property’s actual settled prices and occupancy.
Related Articles
References and Sources
■ Data Sources
CREAL Inc. timely disclosure (October 8, 2026), official fund page and July 16, 2026 release; IHG release of January 20, 2025; each investment corporation’s IR portfolio list (as of October 12, 2026); MLIT Real Estate Information Library (land price publication, zoning, station ridership) and Building Construction Starts statistics; Japan Real Estate Institute, “54th Japanese Real Estate Investor Survey”; and MetroEngines Research & Consulting estimated settled ADR, estimated OCC and property data (Chuo-ku, Osaka: N=184-194 properties per month; within 1 km of Honmachi Station: N=107 properties).
■ Estimation Assumptions
The sale price is the floor of ¥3,779.5 million derived from the disclosure wording (at least 10% of consolidated net sales of ¥37,795 million). The room count is the 168 rooms stated in CREAL’s July 31, 2026 release. Required NOI yields of 4.5% / 5.0% / 5.5%, GOP margins of 35% / 40% / 45%, and an owner’s share of 85% of GOP were assumed; required RevPAR was obtained by dividing required revenue by 168 rooms × 365 days. The leverage calculation assumes LTV of about 50% and interest rates of 1.5-2.5%, ignoring principal repayment, fees and taxes. Replacement cost is the sum of official land price ÷ maximum FAR and the steel-frame planned construction cost (national figure) from the Building Construction Starts statistics.
■ Limitations
The actual sale price and rent terms are undisclosed, so the required RevPAR is only a guide relative to the floor price. Estimated ADR and OCC are estimates based on published OTA prices and sales inventory and differ from each property’s actual results (median error of about 7% against results disclosed by listed hotel REITs). Replacement cost is a rough guide that does not consider site-specific factors or depreciation of the existing building. The investor composition and the Type 3 and Type 4 operators of the buyer SPC are not disclosed, and this article draws no conclusions on them.
■ Primary Sources (Timely Disclosures, Official Pages, Press Releases)
- CREAL Inc., “Notice Concerning Sale of Trust Beneficiary Interest (Real Estate for Sale) (Garner Hotel Osaka Honmachi Midosuji)” (October 8, 2026, Japanese)
- CREAL Inc. official fund page, “Fund No. 145: Osaka Kita-Semba Hotel” (Japanese)
- CREAL Inc., “CREAL’s Osaka Kita-Semba Hotel Fund Closes Fully Subscribed” (July 16, 2026, Japanese)
- IHG Hotels & Resorts, “IHG Hotels & Resorts launches Garner brand in Japan with three new openings in Osaka” (January 20, 2025)
- Ichigo Hotel REIT Investment Corporation, materials on assets to be acquired (March 15, 2023; Comfort Hotel Osaka Shinsaibashi appraisal NOI yield 4.7%, Japanese)
■ Government Statistics and Public Data
- MLIT, “About Real Estate Specified Joint Enterprises” (Japanese)
- MLIT, “Outline of the Bill to Partially Amend the Real Estate Specified Joint Enterprise Act (Creation of Specified Joint Enterprises)” (Japanese)
- MLIT Real Estate Information Library: land price publication (Honmachi 3-chome 22-1 et al.), zoning, station ridership (National Land Numerical Information S12)
- MLIT, “Building Construction Starts Statistics” 2025 (hotels or ryokan, planned construction cost by structure)
- Japan National Tourism Organization (JNTO), “Visitor Arrivals” August 2026 estimate (released September 16, 2026)
■ Industry Reports and REITs
- Japan Real Estate Institute, “54th Japanese Real Estate Investor Survey (as of April 2026)”: expected yields for limited-service hotels
- Invincible Investment Corporation portfolio (GOP results of MHM-operated hotels)
- Relo Hotel Solutions, “GOPPAR” explainer (GOP margins of around 30-40% as a common industry benchmark, Japanese)
- IR portfolio lists of each investment corporation (Ichigo Hotel REIT, Invincible Investment Corporation, Nippon Hotel & Residential Investment Corporation, Japan Hotel REIT, Hoshino Resorts REIT, MORI TRUST REIT, Kasumigaseki Hotel REIT): ownership master as of October 12, 2026
■ Market Data
- MetroEngines Research & Consulting: estimated settled ADR (Chuo-ku, Osaka N=184-194 properties per month; Osaka Prefecture N=655 properties), estimated OCC (Chuo-ku, 122-130 properties / 19,287-19,720 rooms covered), and property and room data within a radius of Honmachi Station (N=107 properties)