

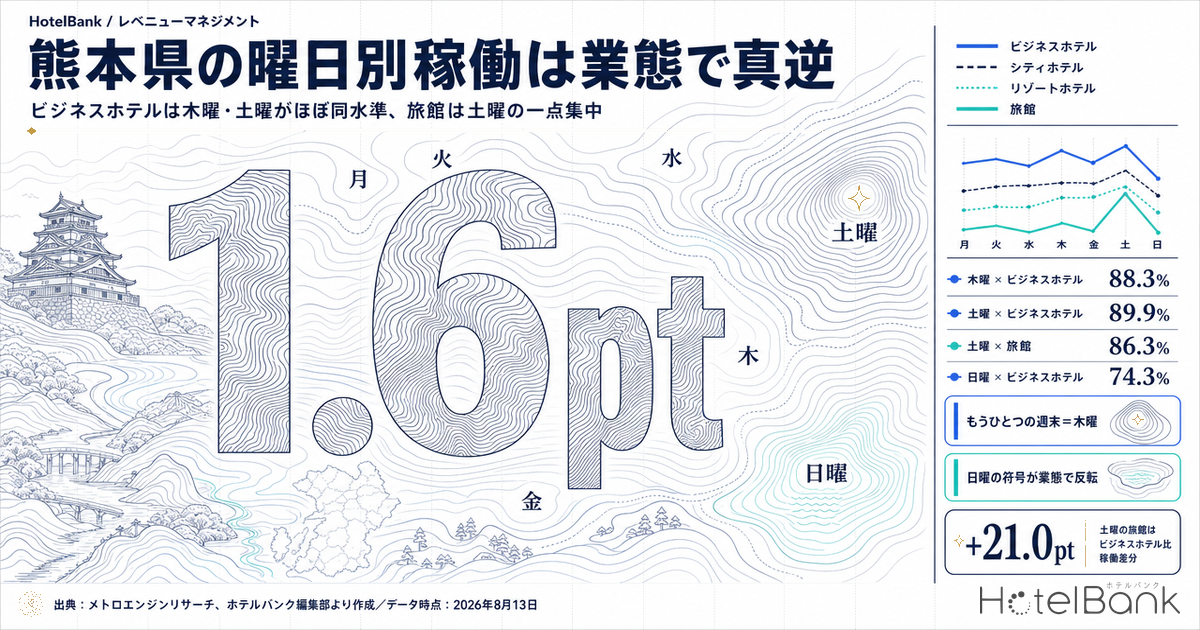
Aggregating Kumamoto’s June and July 2026 results by day of week on a room-weighted basis, business hotels post an estimated OCC of 89.9% on Saturday against 88.3% on Thursday — a gap of just 1.6pt. Sunday, by contrast, drops to 74.3%, widening the gap versus Saturday to 15.6pt. A day-of-week design built on the premise that “weekends are busy and weekdays are slow” succeeds or fails by property type in this market. Ryokan run 86.3% on Saturday against 75.5% on weekdays, a clear weekend-driven 10.8pt spread; resorts show a two-day weekend pattern at 90.1% on Saturday and 86.4% on Sunday; city hotels sit at essentially the same level on Thursday (91.0%) and Saturday (91.2%). Within a single prefecture, the shape of the peaks and troughs across the week is a different animal for each property type.
Coverage: accommodation facilities in Kumamoto, N=436–523 properties (prefecture-wide, all types, on a daily observation basis; of these, four types — business hotels, city hotels, resort hotels and ryokan — are compared). The price metric in this article is estimated settled ADR (a settled price level inferred from sales data such as OTAs, approximately tax-exclusive), and occupancy is an estimate based on OTA-listed inventory. Definitions for both appear at the end of the article. Data as of: August 13, 2026.
- — Business hotels run 88.3% on Thursday and 89.9% on Saturday, a gap of 1.6pt (June–July 2026, room-weighted). City hotels are at 91.0% on Thursday and 91.2% on Saturday, a gap of 0.2pt. For these two types, Thursday sits at the level of a second weekend.
- — The sign of Sunday flips by property type. Measured against the weekday (Mon–Fri) weighted average, the gap is −10.6pt for business hotels and −5.0pt for city hotels, versus +7.0pt for resorts and +3.2pt for ryokan. The same single day is both a trough and a peak.
- — Ryokan are a single-peak type at 86.3% on Saturday against 75.5% on weekdays, while resorts are a two-day weekend type at 90.1% on Saturday and 86.4% on Sunday. Weekend-concentrated pricing design is consistent with the data for these two types.
- — The pace of pickup differs too. Thursday (September 3) went from 71.0% at 45 days out to 92.0% most recently, +21.0pt, while Saturday (September 5) moved from 80.0% to 86.4%, +6.4pt. The window in which room remains to revise pricing varies by day of week.
- — The prefecture-wide (all types) day-of-week curve is pulled by business hotels, which account for 60.5% of room count. If ryokan and resorts benchmark against the prefecture average, they are working from a premise that is off by roughly 10pt.
Estimated OCC by day of week in Kumamoto — the peak sits in a different place for each type
The chart below shows the room-weighted average by day of week of Kumamoto’s daily estimated OCC (based on OTA-listed inventory) across the 61 days from June 1 to July 31, 2026. The weighting is calculated as “total rooms sold across all dates falling on that day of week ÷ total room count,” so it reflects differences in inventory scale from day to day exactly as they are.
Source: MetroEngines Research; compiled by the HotelBank Editorial Team
The four lines trace distinctly different demand structures. Business hotels and city hotels build steadily from Tuesday through Thursday, reach their peak zone on Thursday, ease back on Friday, lift again on Saturday and fall away on Sunday — an “M-shaped” pattern. Resort hotels and ryokan, by contrast, run almost flat from Monday through Thursday, tick up slightly from Friday, jump sharply on Saturday and hold up reasonably well on Sunday — a “single weekend peak” pattern.
| Property type (N=properties) | Mon | Tue | Wed | Thu | Fri | Sat | Sun | Sat−Sun |
|---|---|---|---|---|---|---|---|---|
| Business hotels (N=102–109) | 79.7 | 85.3 | 87.0 | 88.3 | 83.9 | 89.9 | 74.3 | 15.6pt |
| City hotels (N=17–18) | 83.0 | 87.6 | 89.1 | 91.0 | 88.2 | 91.2 | 82.7 | 8.5pt |
| Resort hotels (N=16–21) | 79.7 | 79.1 | 76.6 | 79.3 | 81.9 | 90.1 | 86.4 | 3.7pt |
| Ryokan (N=160–217) | 75.0 | 74.7 | 75.1 | 75.6 | 77.0 | 86.3 | 78.8 | 7.5pt |
Unit = % (estimated OCC, based on OTA-listed inventory; the 61 days of June–July 2026 aggregated by day of week as a room-weighted average). Source: MetroEngines Research; compiled by the HotelBank Editorial Team
Laid out numerically, the differences are starker still. Business hotels’ 88.3% on Thursday runs 4.4pt above the same type’s 83.9% on Friday, and sits just 1.6pt below Saturday’s 89.9%. It is also 3.5pt above the weekday (Mon–Fri) weighted average of 84.8%. For city hotels the gap between Thursday’s 91.0% and Saturday’s 91.2% is 0.2pt — effectively identical levels. In other words, for these two types Thursday is a day that should be treated not as a “weekday” but as a second weekend.
Conversely, for resort hotels and ryokan, Thursday sits at 79.3% and 75.6% respectively, buried entirely within the weekdays. The gap versus Saturday is 10.8pt for resorts and 10.7pt for ryokan. Even within the same “accommodation demand in Kumamoto,” the day-of-week calendar means something entirely different for types that primarily absorb business-travel demand moving on weekdays versus those that primarily absorb weekend leisure and tourism demand. The structure in which the weekly peak shifts by type and by market is not unique to Kumamoto: as shown in Saitama Business Hotels: Sat 77.2% vs Sun 70.1%, Gap Widens to 11pt, even within the same business-hotel type the arrangement of peaks and troughs differs from market to market.
The Sunday trough flips sign by type — and “Sunday” is not uniform either
The most direct expression of the day-of-week differences is the deviation of Saturday and Sunday from the weekday (Mon–Fri) weighted average. The chart below lines up that difference for each property type.
Source: MetroEngines Research; compiled by the HotelBank Editorial Team
The Saturday deviation is positive for every type, but the magnitude varies widely. Ryokan are at +10.8pt and resorts at +10.7pt, while business hotels come in at +5.0pt and city hotels at just +3.5pt. More important is Sunday: resorts run +7.0pt and ryokan +3.2pt against weekdays, while business hotels sink to −10.6pt and city hotels to −5.0pt. The same single day, Sunday, is both an earning day and the deepest trough depending on the property type. The depth of that Sunday trough also varies by market — in some prefectures the same business-hotel type shows a trough of only 7 to 9pt, shallower than Kumamoto’s.
That said, the “Sunday trough” is not uniform either. Kumamoto’s business hotels had eight Sundays across June–July 2026, of which five landed between 66.3% and 68.9%, occupying the bottom of the period as a whole (June 21 at 66.3%, June 7 at 67.0%, June 14 at 68.6%, July 5 at 68.6%, July 12 at 68.9%). The remaining three scatter widely: July 19 at 92.9%, June 28 at 87.8% and July 26 at 73.9%. July 19 was a Sunday followed by a public holiday on the 20th, and it stands 26.6pt above the lowest reading of June 21. That holiday itself, Monday July 20, came in at 71.1% — the lowest of the nine Mondays in the period. Demand across a long weekend shows up as “building through the middle day and draining away entirely on the final day,” and setting inventory and rates by day of week alone, without looking at how the calendar falls, means missing both the peak and the trough.
On a monthly basis, business hotels’ estimated OCC was 82.6% in June 2026 and 85.6% in July. Over the same period the other types recorded 86.7% and 88.4% for city hotels, 81.2% and 82.0% for resort hotels, and 76.8% and 77.7% for ryokan. The 61 days used for the day-of-week aggregation form a continuous period with no gaps in observation for any of the types.
One note on aggregation method. The day-of-week figures in this article are room-weighted (on an inventory-total basis), and the difference versus a simple average of daily estimated OCC is at most 0.4pt (resort hotels on Tuesday). The weighting matters far more, however, when looking at the “prefecture-wide” figure across types. Across the 61 days, business hotels averaged 12,402 rooms, or 60.5% of the prefecture-wide (all types) total, while ryokan — despite ranking among the largest by property count at 160–217 properties — hold a room-count share of just 16.6% (an average of 3,410 rooms). That is why the prefecture-wide estimated OCC by day of week (Mon 79.6%, Tue 83.3%, Wed 84.6%, Thu 85.6%, Fri 83.0%, Sat 89.4%, Sun 77.4%, N=436–523 properties) closely resembles the business-hotel shape, and why ryokan and resort operators who use the “prefecture-wide day-of-week curve” directly as their own benchmark end up working from a premise that is off from reality by roughly 10pt. A second point: the final four days of the aggregation period (July 28–31) fall immediately after the 2026 Kumamoto Earthquake (which struck at 16:27 on July 28), and should be read with that discount in mind. In the immediate aftermath, OTA-listed inventory at affected properties disappears altogether, which can push estimated OCC higher in a way unrelated to real demand. This structure — in which inventory disappearance and actual closure do not line up — is examined in detail in Kumamoto Quake 2026, 72 Hours On: 6 Closures vs 17.9% Inventory Loss. The affected days amount to one day each out of roughly nine for Tuesday, Wednesday, Thursday and Friday respectively, so the effect on the period average is limited, though the possibility that those particular days are marginally overstated remains.
Booking curves for Thursday, Saturday and Sunday — days that build up, and days that start high
Differences by day of week show up not only in the final occupancy level but in “when the rooms fill.” For Kumamoto’s business hotels (N=110 properties, 12,902 rooms), we tracked estimated OCC from 45 days before the stay date through to the most recent observation for three dates: Thursday September 3, Saturday September 5 and Sunday September 6, 2026.
Source: MetroEngines Research; compiled by the HotelBank Editorial Team
| Stay date | 45 days out | 30 days out | Latest observation | 45 days out → latest |
|---|---|---|---|---|
| Thursday, September 3, 2026 | 71.0 | 83.7 | 92.0 (22 days out) | +21.0pt |
| Saturday, September 5, 2026 | 80.0 | 84.5 | 86.4 (24 days out) | +6.4pt |
| Sunday, September 6, 2026 | 68.1 | 80.0 | 80.1 (25 days out) | +12.0pt |
Unit = % (estimated OCC, based on OTA-listed inventory). Kumamoto business hotels N=110 properties, 12,902 rooms; observed property count at 45 days out was 100–102. Source: MetroEngines Research; compiled by the HotelBank Editorial Team
Saturday (September 5) is already the highest of the three at 45 days out, at 80.0%, but adds only 6.4pt from there to the latest observation. Thursday (September 3), by contrast, starts 9.0pt below Saturday at 71.0% at 45 days out, reaches 83.7% at 30 days out and 92.0% at 22 days out, for a gain of +21.0pt over the period — ultimately finishing 5.6pt above Saturday. Sunday (September 6) builds 11.9pt from 68.1% at 45 days out to 80.0% at 30 days out, then runs essentially flat at 80.1% at 25 days out.
The same tendency is visible the following week. Thursday September 10 went from 62.0% at 45 days out to 88.8% at 29 days out, +26.8pt, while Saturday September 12 moved from 69.9% at 45 days out to 84.6% at 31 days out, +14.7pt. The pattern is consistent: Thursday is a day that builds “late and large,” while Saturday builds “early and small.”
And there are exceptions among Sundays too. Sunday September 20 was already at 87.1% at 45 days out and reached 91.8% at 39 days out — a gap of 19.0pt versus the same weekday on September 6 (68.1% at 45 days out). September 20 is a Sunday followed by a public holiday on the 21st, the same character of day as July 19 in the June–July results. Every quarter contains a handful of days that the day-of-week label alone cannot explain.
A yardstick for rate levels — estimated settled ADR for confirmed months
Price levels by day of week are not addressed in this article, because estimated settled ADR is a metric that is canonical at monthly granularity. As a monthly yardstick for positioning your own rate band against the market, however, we show the year-on-year comparison between confirmed values. Estimated settled ADR for Kumamoto’s business hotels was in the ¥6,600s in June 2026 and the ¥6,500s in July, both marginally below the same month a year earlier. City hotels were in the ¥8,300s in June 2026 and the ¥8,800s in July.
| Property type and month | Estimated settled ADR (confirmed) | Same month, prior year (confirmed) | Year on year | N=properties |
|---|---|---|---|---|
| Business hotels, June 2026 | ¥6,612 | ¥6,635 | −0.3% | 118 (prior year 115) |
| Business hotels, July 2026 | ¥6,574 | ¥6,634 | −0.9% | 119 (prior year 115) |
| City hotels, June 2026 | ¥8,332 | ¥8,921 | −6.6% | 19 (prior year 19) |
| City hotels, July 2026 | ¥8,842 | ¥9,078 | −2.6% | 19 (prior year 19) |
Estimated settled ADR (approximately tax-exclusive). Comparison between confirmed values for past months. Source: MetroEngines Research; compiled by the HotelBank Editorial Team
Weekday occupancy levels of 88.3% on Thursday and 87.0% on Wednesday are being secured, yet estimated settled ADR for the confirmed months sits marginally below the same month a year earlier. Where the occupancy peaks fall and whether rate is being captured at those peaks are separate questions, and mapping the day-of-week structure is the starting point for reconciling the two.
For revenue managers operating hotels and ryokan in Kumamoto — implications and an action plan
1. There is room to reset the “weekend premium” design to match your own property type’s day-of-week curve. For business hotels the gap between Saturday’s 89.9% and Thursday’s 88.3% is 1.6pt; for city hotels, Saturday 91.2% versus Thursday 91.0% is 0.2pt. If these two types are loading a heavy premium onto Saturday alone while leaving Thursday at the weekday rate, the demand peak and the rate peak may be out of alignment. Ryokan and resorts, conversely, show a 10.7–10.8pt gap between Saturday and weekdays, so a weekend-concentrated design is consistent with the data.
2. The treatment of Sunday swings in opposite directions by type. Business hotels’ Sunday at 74.3% runs 10.6pt below the weekday weighted average, while resorts’ Sunday at 86.4% runs 7.0pt above weekdays. A setting that lumps Sunday in as “part of the weekend” risks, for some types, holding a high rate against the deepest trough of the week. Sunday is worth considering independently, as a target day for consecutive-night incentives and stay extensions.
3. On some days the calendar arrangement takes precedence over the day-of-week label. Sunday July 19 at 92.9%, against the following public holiday, Monday July 20, at 71.1%. Sunday September 20 reached 87.1% at 45 days out, a 19.0pt gap versus the 68.1% of an ordinary Sunday on September 6. Days before a public holiday and the final day of a long weekend are worth handling individually, as exceptions to the day-of-week rule.
4. Differences in how demand builds govern the timing of rate revisions. Thursday (September 3) went from 71.0% at 45 days out to 92.0% most recently, +21.0pt; Saturday (September 5) from 80.0% to 86.4%, +6.4pt. Judging on the absolute level at an early stage alone, Thursday looks like a “weak day” when in fact it builds later. Saturday’s level tends to be set early, and the scope to recover at a late stage is relatively small.
| Time horizon | Action | Decision trigger | Objective |
|---|---|---|---|
| Today to this week | Re-sort your own last 61 days of occupancy by day of week on a room-weighted basis and overlay it on the figures for your type in this article | If, in the business-hotel type, your Thursday is clearly below the market’s 88.3%, or, in the ryokan type, your Saturday falls short of 86.3% | Identify the misalignment in day-of-week design as a gap against the level for your own type, rather than by intuition |
| Today to this week | Audit the rate differential between Thursday and Saturday, and consider whether Wednesday and Thursday can be carved out of the “weekday” bucket | If, against the market’s 88.3% on Thursday and 87.0% on Wednesday, your Thursday and Wednesday rates remain set identically to Monday (a 79.7% day) | Confirm the room to align the rate peak with the demand peak |
| Within two weeks | Pull out the holiday-adjacent Sundays and long-weekend final days within the next 45 days and exclude them from the standard day-of-week rule | If your calendar contains days like Sunday September 20, at 87.1% at 45 days out, far above an ordinary Sunday’s 68.1% | Avoid processing exception days through a blanket weekend/weekday split |
| Within two weeks | Redesign Sunday inventory as a vehicle for Saturday–Sunday and Sunday–Monday consecutive stays rather than single-night sales | If your Sunday is tracking at or below the business-hotel market level of 74.3% (−10.6pt versus weekdays) | Fill the deepest trough by means other than single-night discounting |
| Looking to next month | Separate the timing of rate revisions for Thursday and Saturday, leaving scope to revise Thursday from 30 days out onward | Bearing in mind that even if your Thursday sits around the market’s 71.0% at 45 days out, the market builds to 83.7% by 30 days out | Avoid judging Thursday a weak day on the early-stage level alone |
| Looking to next month | Reconcile your own monthly ADR against the market level for confirmed months to check where your rate band sits | If your setting for the month in question remains below the business-hotel estimated settled ADR of ¥6,574–¥6,612 (confirmed, June–July 2026) while occupancy alone matches the market | Verify whether rate is being captured at the occupancy peak |
Source: MetroEngines Research; compiled by the HotelBank Editorial Team
Converting a filled Sunday trough into rooms — three scenarios and a sensitivity grid
Every figure up to this point is an actual measurement; what follows is not a new observation but an arithmetic conversion derived from this article’s definition of estimated OCC (100 − 100 × listed unsold rooms ÷ total room count). By definition, 1pt corresponds to 1% of total room count, so a difference in occupancy translates directly into rooms. Using Kumamoto business hotels’ 61-day average of 12,402 rooms and the eight Sundays in the period, we set out the room impact of a shift in the Sunday level.
| Scenario | Sunday estimated OCC | Gap vs the period’s Sunday average | Room difference per Sunday | Total across 8 Sundays |
|---|---|---|---|---|
| Pessimistic (average level of the five lowest Sundays in the period) | 67.9% | −6.4pt | −794 rooms | −6,350 room-nights |
| Mid (the period’s Sunday average = current state) | 74.3% | ±0pt | ±0 rooms | ±0 room-nights |
| Optimistic (the trough closes to the weekday (Mon–Fri) weighted average) | 84.8% | +10.5pt | +1,302 rooms | +10,418 room-nights |
Pessimistic = the average of the five lowest of the eight Sundays in June–July 2026 (66.3 / 67.0 / 68.6 / 68.6 / 68.9%). Optimistic = the weekday weighted average of 84.8% for the same period. Source: MetroEngines Research; compiled by the HotelBank Editorial Team
To bring a prefecture-wide discussion down to your own property, apply the same conversion using your own room count. The table below shows, for “points added to Sunday × your room count,” the additional rooms that could be sold per Sunday. The +10.5pt at the top of the range corresponds to the optimistic scenario above — Sunday reaching the weekday weighted average for the period.
| Points added to Sunday | 60 rooms | 100 rooms | 150 rooms | 200 rooms | 300 rooms |
|---|---|---|---|---|---|
| +2.0pt | 1.2 | 2.0 | 3.0 | 4.0 | 6.0 |
| +4.0pt | 2.4 | 4.0 | 6.0 | 8.0 | 12.0 |
| +6.0pt | 3.6 | 6.0 | 9.0 | 12.0 | 18.0 |
| +8.0pt | 4.8 | 8.0 | 12.0 | 16.0 | 24.0 |
| +10.5pt | 6.3 | 10.5 | 15.8 | 21.0 | 31.5 |
Cells are room count × points added ÷ 100. This is an arithmetic conversion from the definition of estimated OCC and does not forecast future occupancy. Source: MetroEngines Research; compiled by the HotelBank Editorial Team
Summary — three yardsticks for reading the week
Kumamoto’s June–July 2026 results yield three yardsticks for auditing day-of-week design.
First, the location of the peak. Business hotels at 88.3% on Thursday and 89.9% on Saturday (a 1.6pt gap) and city hotels at 91.0% and 91.2% (0.2pt), against ryokan at 75.6% on Thursday and 86.3% on Saturday (10.7pt) and resorts at 79.3% and 90.1% (10.8pt). Which of the two patterns your property type follows changes the very definition of “the weekend.”
Second, the sign of the trough. The gap between Sunday and the weekday weighted average is −10.6pt for business hotels and −5.0pt for city hotels, against +7.0pt for resorts and +3.2pt for ryokan. Whether Sunday is a trough or a peak flips by property type.
Third, the speed of pickup. Thursday (September 3) went from 71.0% at 45 days out to 92.0% most recently, +21.0pt; Saturday (September 5) from 80.0% to 86.4%, +6.4pt. Even for days that land at around the same 90%, a different route to get there changes the timing of the levers you pull.
The general rule that “weekends sell high” is worth checking type by type before applying it in a market like Kumamoto, where weekday business-travel demand carries substantial weight. Can Thursday be treated as a second weekend? How should Sunday be filled? Starting by confirming those two points against your own day-of-week curve will reveal where the room lies in your existing rate calendar.
Metric Definitions Used in This Article
| Item | Detail |
|---|---|
| Definition of estimated OCC | Occupancy based on OTA-listed inventory = 100 − 100 × OTA-listed unsold rooms ÷ total room count. It is an estimate based on how listed inventory sells through on OTAs, and its definition differs from actual room occupancy (it reads higher). This article denotes it as “estimated OCC (based on OTA-listed inventory).” The period covered is June 1 to July 31, 2026 (61 days). |
| Booking curve | Based on observations from 45 days before the stay date through to the latest reading. Coverage is Kumamoto business hotels for stay dates September 3, 5, 6, 10, 12, 19 and 20, 2026. |
| Definition of estimated settled ADR | A settled price level (approximately tax-exclusive) inferred from sales data such as OTAs (lowest-plan levels × type-specific coefficients, an ensemble across multiple channels). Past months are confirmed values; the current and future months are estimates based on the sales position at the present time. Reconciliation against disclosed operating results gives a median error of 6.6%. Only confirmed values for June–July 2025 and June–July 2026 are cited in this article. |
| Breakdown of N | Estimated OCC by day of week (June–July 2026, range of property counts on a daily observation basis): business hotels 102–109 properties, 11,762–12,726 rooms; city hotels 17–18 properties, 1,913–1,999 rooms; resort hotels 16–21 properties, 1,102–1,399 rooms; ryokan 160–217 properties, 2,822–3,791 rooms; prefecture-wide (all types) 436–523 properties, 19,573–21,388 rooms. Booking curves: Kumamoto business hotels, 110 properties, 12,902 rooms (observed property count at 45 days out 100–102). Estimated settled ADR: business hotels 118–119 properties (115 in the prior year), city hotels 19 properties (19 in the prior year). |
| Aggregation method | Day-of-week values are a room-weighted average of total rooms sold on the relevant dates ÷ total room count. The difference versus a simple average of daily estimated OCC is at most 0.4pt. Year-on-year comparisons are calculated between confirmed values only. |
| Data as of | Data as of: August 13, 2026. Sales positions and inventory fluctuate daily, so the figures in this article are a snapshot as of the time of retrieval. |
Source: MetroEngines Research; compiled by the HotelBank Editorial Team
■ Data sources
MetroEngines Research daily aggregation of OTA-listed inventory and listed prices (Kumamoto). Estimated OCC by day of week covers the 61 days from June 1 to July 31, 2026; booking curves cover observations from 45 days out onward for September 2026 stays; estimated settled ADR covers confirmed values for June–July 2025 and June–July 2026. Property types are split into four categories — business hotels, city hotels, resort hotels and ryokan — while “prefecture-wide” covers all types, including deluxe, capsule and others.
■ Calculation assumptions
Day-of-week values are a room-weighted average of total rooms sold on the relevant day of week ÷ total room count (the difference versus a simple average of daily estimated OCC is at most 0.4pt). Weekdays use the same weighting across Monday to Friday. Conversion from points to rooms is calculated from the definition of estimated OCC (100 − 100 × listed unsold rooms ÷ total room count), taking 1pt as 1% of total room count, and the Sunday scenarios use business hotels’ 61-day average of 12,402 rooms and the eight Sundays in the period. Year-on-year comparisons are calculated between confirmed values only.
■ Limitations and caveats
Estimated OCC is based on OTA-listed inventory, and its definition differs from actual room occupancy (it reads higher). Estimated settled ADR has a median error of 6.6% against disclosed REIT results (approximately tax-exclusive). The final four days of the aggregation period (July 28–31) fall immediately after the 2026 Kumamoto Earthquake, and estimated OCC may be overstated because listed inventory at affected properties disappeared. The scenario and sensitivity tables are arithmetic conversions within the range of measured values in the body text, not forecasts of future occupancy; price levels by day of week (day-of-week ADR) are not addressed in this article because estimated settled ADR is canonical at monthly granularity.
Related reading
- Saitama Business Hotels: Sat 77.2% vs Sun 70.1%, Gap Widens to 11pt
- Mie August Booking Curves: Business Hotels Swing 25.5pt, Ryokan 9.7pt
- Tochigi Booking Curves by Type: Resort 81.1% at T-45, Only +2.6pt Left
- Kagoshima Summer Booking Curves: 23.2pt Gap by Type at 45 Days Out
- Kumamoto Quake 2026, 72 Hours On: 6 Closures vs 17.9% Inventory Loss