

RevPAR (Revenue per Available Room) restates room revenue on a “per available room” basis. Neither ADR (average daily rate) on its own nor occupancy (OCC) on its own measures how well the rooms division is really performing; RevPAR folds both into a single number. It is the first figure Japan’s listed hotel REITs disclose in their monthly operating results, and the first one international hotel chains reach for on an earnings call.
This article sets out the definition and confirms numerically that three different formulas return the same result. It then uses a 100-room profit-and-loss model to show that the same RevPAR does not produce the same profit when one property is high-ADR and the other is high-occupancy, and goes on to cover estimated 2026 RevPAR levels by hotel category, the distance between those estimates and REIT disclosures, and how RevPAR sits alongside GOPPAR, TRevPAR and the RevPAR Index (MPI / ARI / RGI).
Metric Definitions Used in This Article
- RevPAR: Room revenue ÷ available room nights. Available room nights = total rooms × days in the period. Equals ADR × occupancy rate.
- ADR (average daily rate): An estimated settled rate (tax-excluded equivalent) calculated by applying a category-specific adjustment factor to the lowest published plan rate each property lists on OTAs (double occupancy, per room, tax included). Cross-checked against per-property results disclosed by listed hotel REITs, the median error is 6.6%. These are estimates and differ from each property’s actual transacted rates and accounting figures. Area-level ADR is the median across properties in scope (the level of a typical property in that area).
- Room occupancy rate (Japan Tourism Agency definition): Rooms sold ÷ available room nights × 100. This is the official aggregation definition used in the Japan Tourism Agency’s “Overnight Travel Statistics Survey”. This article refers to it as the official occupancy rate.
- OCC (estimated occupancy): Rooms sold as a share of total rooms in the area (an estimate based on OTA sales inventory; consistency checks against monthly REIT disclosures put accuracy in the range of a few percentage points). This article refers to it as the OTA-inventory-based estimated occupancy rate and treats it as a separate metric with a different population and a different denominator from the official occupancy rate.
- GOP: Total revenue − (direct departmental costs + undistributed operating expenses). GOPPAR: GOP ÷ available room nights. TRevPAR: total revenue ÷ available room nights.
- Data sources: MetroEngines Research / Japan Tourism Agency, “Overnight Travel Statistics Survey” / monthly disclosures from individual REITs
- — RevPAR = room revenue ÷ available room nights = ADR × occupancy rate. All three formulas always return the same value. The decisive difference from ADR is that the denominator counts rooms that could be sold, not rooms that were sold.
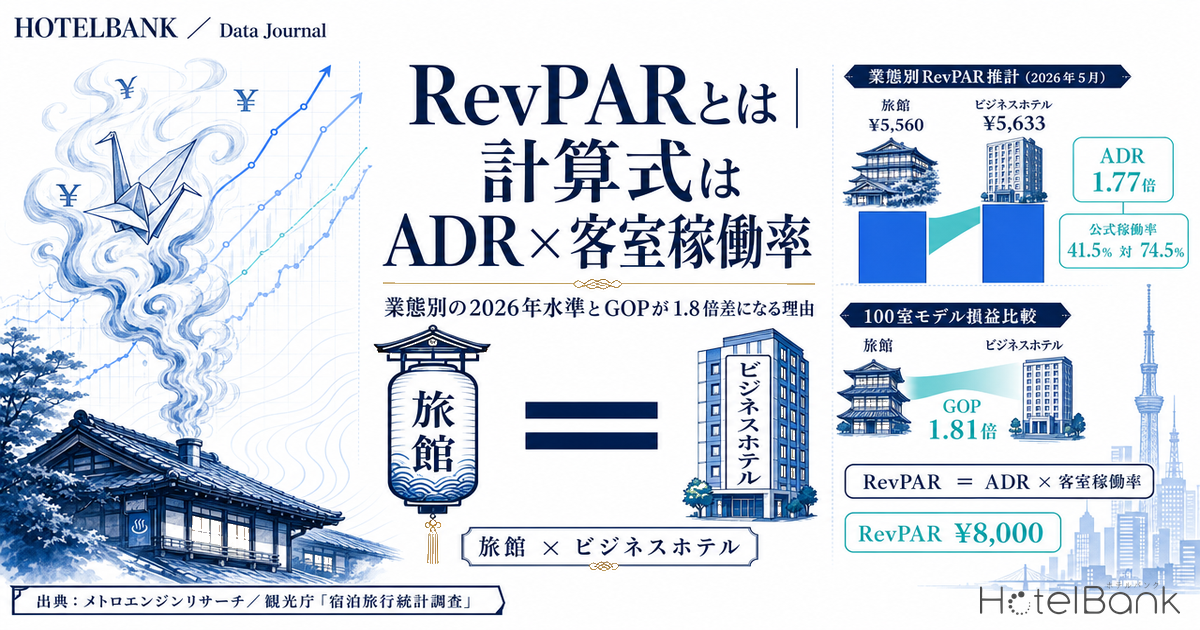
- — The same RevPAR does not produce the same GOP. In a 100-room model held at RevPAR ¥8,000, ADR ¥16,000 × OCC 50% delivers annual GOP of ¥76.8mn while ADR ¥10,000 × OCC 80% delivers ¥42.3mn — a gap of 1.81x. Selling 1.6x more room nights means 1.6x the housekeeping, linen and supplies.
- — That does not make the high-ADR model universally better. Once the high-ADR property’s fixed costs exceed 1.24x those of the high-occupancy property, the ranking flips. The break-even occupancy rates are also completely different — 32.8% against 62.0%. RevPAR alone does not settle the question.
- — Estimated May 2026 RevPAR puts ryokan (¥5,560) and business hotels (¥5,633) almost level. Ryokan ADR is 1.77x that of business hotels, but with official occupancy at 41.5% against 74.5%, room revenue ends up neck and neck.
- — Listed hotel REITs disclose higher RevPAR than our estimates because of portfolio mix, not methodology. Run the same estimate for business hotels in Tokyo alone and it comes to roughly ¥12,600 — above the disclosed REIT range.
What RevPAR Is — Confirming That Three Formulas Give the Same Number
The definition of RevPAR is extremely simple. Take rooms-division revenue and divide it by the total number of rooms that could have been sold during the period.
RevPAR = room revenue ÷ available room nights
available room nights = total rooms × days in the period
From there comes the decomposition used more often in practice. Room revenue equals ADR × rooms sold, and rooms sold ÷ available room nights is the occupancy rate itself. Written out:
RevPAR = (ADR × rooms sold) ÷ available room nights = ADR × occupancy rate
Put differently, RevPAR expresses how much a property earned per room on average even when it was not full. ADR takes only rooms sold into its denominator and therefore ignores vacancies; RevPAR puts vacant rooms into the denominator too. That difference in denominator is the core of what separates ADR from RevPAR. The example below — a 100-room property operating for 30 days — confirms that all three calculations agree.
| Item | Value | Calculation |
|---|---|---|
| Total rooms | 100 rooms | assumption |
| Available room nights | 3,000 | 100 rooms × 30 days |
| Rooms sold | 1,800 | assumption |
| Occupancy rate (OCC) | 60.0% | 1,800 ÷ 3,000 |
| Room revenue | ¥21,600,000 | assumption |
| ADR | ¥12,000 | 21,600,000 ÷ 1,800 rooms |
| RevPAR (formula 1) | ¥7,200 | 21,600,000 ÷ 3,000 rooms |
| RevPAR (formula 2) | ¥7,200 | ¥12,000 × 60.0% |
| RevPAR (formula 3) | ¥7,200 | (¥12,000 × 1,800 rooms) ÷ 3,000 rooms |
Source: compiled by the HotelBank Editorial Team
Two situations typically knock the denominator out of line in practice. The first is how to treat rooms closed for renovation. The Japan Tourism Agency’s aggregation puts the number of physically existing rooms in the denominator, so rooms taken out of service for renovation are in principle still counted. An internal RevPAR that counts only rooms in service will not line up with external statistics. The second is days of operation: a property that closes seasonally has to fix in advance whether it uses 365 days or actual operating days, or a year-on-year comparison means nothing. Before comparing RevPAR, the denominators have to be aligned.
For the definition of ADR itself, and how far listed OTA prices sit from settled rates, see What Is Hotel ADR? Settled Rates 34-57% of Listed Prices, 2026. The occupancy side — the definition of the room occupancy rate, how it differs from bed occupancy, and how to back out break-even occupancy — sits outside the scope of this article, which stays on the decomposition of RevPAR.
The Same RevPAR Does Not Give the Same GOP — A 100-Room P&L
RevPAR summarises room revenue, not profit. This is the point most often misunderstood. Even at an identical RevPAR, costs move substantially depending on whether the mix behind it is high ADR with low occupancy or low ADR with high occupancy. The reason is straightforward: housekeeping, linen, amenities and in-room utilities scale with rooms sold, not with revenue.
Take a 100-room property operating 365 days a year and set two patterns to the same RevPAR of ¥8,000 (the ADR and occupancy figures below are model assumptions, not observed values). Pattern A is ADR ¥16,000 × OCC 50%; pattern B is ADR ¥10,000 × OCC 80%. Annual room revenue is identical at ¥292.0mn, but rooms sold differ by 1.6x — 18,250 for A against 29,200 for B.
| Item | A: high ADR × low OCC ¥16,000 × 50% | B: low ADR × high OCC ¥10,000 × 80% | Difference |
|---|---|---|---|
| Available room nights | 36,500 | 36,500 | — |
| Rooms sold | 18,250 | 29,200 | +10,950 |
| Room revenue | ¥292,000,000 | ¥292,000,000 | ¥0 |
| Housekeeping and linen (@¥2,400/room) | ¥43,800,000 | ¥70,080,000 | +¥26,280,000 |
| Consumables and amenities (@¥350/room) | ¥6,387,500 | ¥10,220,000 | +¥3,832,500 |
| Variable in-room utilities (@¥400/room) | ¥7,300,000 | ¥11,680,000 | +¥4,380,000 |
| Distribution commissions (4% of revenue) | ¥11,680,000 | ¥11,680,000 | ¥0 |
| Total variable costs | ¥69,167,500 | ¥103,660,000 | +¥34,492,500 |
| Fixed costs (payroll, fixed utilities, marketing, repairs, administration) | ¥146,000,000 | ¥146,000,000 | ¥0 |
| GOP | ¥76,832,500 | ¥42,340,000 | −¥34,492,500 |
| GOP margin (on room revenue) | 26.3% | 14.5% | −11.8pt |
| GOPPAR | ¥2,105 | ¥1,160 | −¥945 |
| Break-even occupancy | 32.8% | 62.0% | +29.2pt |
Source: MetroEngine Inc.; compiled by the HotelBank Editorial Team (unit-cost assumptions based on typical levels for rooms-focused properties)
Source: MetroEngine Inc.; compiled by the HotelBank Editorial Team
From the same ¥292.0mn of room revenue, GOP splits into ¥76.8mn and ¥42.3mn — a ratio of 1.81x, or ¥34.5mn a year in cash terms. The substance of “same RevPAR, different profit” is exactly this gap in variable costs. For B to reach the same GOP, room revenue would have to rise 12.3%, to roughly ¥328mn (RevPAR around ¥9,000, equivalent to ADR around ¥11,200).
But do not conclude that the high-ADR model wins
One assumption in Table 2 deserves scrutiny: fixed costs were set at ¥146.0mn for both patterns. In reality, a property commanding ADR ¥16,000 usually carries a richer service level, room specification and staffing, and its fixed costs are heavier accordingly. The moment A’s fixed costs pass ¥180.5mn — 1.24x B’s — the GOP ranking reverses.
| A’s fixed costs | Ratio to B | GOP of A | GOP of B | Result |
|---|---|---|---|---|
| ¥146,000,000 | 1.00x | ¥76,832,500 | ¥42,340,000 | A ahead |
| ¥168,000,000 | 1.15x | ¥54,832,500 | ¥42,340,000 | A ahead |
| ¥180,492,500 | 1.24x | ¥42,340,000 | ¥42,340,000 | crossover (equal) |
| ¥190,000,000 | 1.30x | ¥32,832,500 | ¥42,340,000 | B ahead |
Source: MetroEngine Inc.; compiled by the HotelBank Editorial Team
The asymmetry runs the other way as well. Break-even occupancy is 32.8% for A and 62.0% for B — nearly 30 points apart. A is unlikely to fall below break-even even in thin months, but the pool of demand willing to pay ¥16,000 is shallow, leaving more room for occupancy to drop by double-digit points in a demand shock. B falls below break-even once it drops under 62%, but in exchange it holds a deep, price-elastic customer base, which makes the floor on revenue easier to read.
There is also the point that selling more room nights means a larger base for on-property spend. Put in-house spend at ¥900 per room sold with a 60% gross margin, and ancillary revenue comes to ¥16.4mn for A and ¥26.3mn for B — which puts TRevPAR at ¥8,450 for A and ¥8,720 for B, reversing the order. Look at rooms alone and A is stronger; look at total property revenue and B comes out ahead. This is precisely why an operation that chases RevPAR alone tends to narrow the field of view at properties with food, beverage and retail.
The conclusion is that RevPAR is a metric for comparing rooms-division revenue efficiency on a level basis — it is not profitability itself. There is more than one route to the same RevPAR, and which route is profitable for a given property depends on its variable unit costs, its fixed-cost base and whether it has on-property spend.
A 5×5 Grid of ADR × Occupancy: Where the Same RevPAR Splits on Profit
Table 2 compared just two points. Holding the same model assumptions (100 rooms, 36,500 available room nights a year, ¥3,150 per room sold in housekeeping/consumables/variable utilities combined, distribution commissions at 4% of revenue, fixed costs of ¥146.0mn) and varying ADR across five levels and occupancy across five levels gives annual GOP as a surface, which makes the relationship between RevPAR and profit visible. The shaded cells are the combinations that produce RevPAR ¥8,000 — that is, patterns A and B from Table 2.
| Occupancy \ ADR | ¥10,000 | ¥12,000 | ¥14,000 | ¥16,000 | ¥18,000 |
|---|---|---|---|---|---|
| 50% | -28.3 RevPAR ¥5,000 | 6.8 RevPAR ¥6,000 | 41.8 RevPAR ¥7,000 | 76.8 RevPAR ¥8,000 | 111.9 RevPAR ¥9,000 |
| 60% | -4.7 RevPAR ¥6,000 | 37.3 RevPAR ¥7,200 | 79.4 RevPAR ¥8,400 | 121.4 RevPAR ¥9,600 | 163.4 RevPAR ¥10,800 |
| 70% | 18.8 RevPAR ¥7,000 | 67.9 RevPAR ¥8,400 | 116.9 RevPAR ¥9,800 | 166.0 RevPAR ¥11,200 | 215.0 RevPAR ¥12,600 |
| 80% | 42.3 RevPAR ¥8,000 | 98.4 RevPAR ¥9,600 | 154.5 RevPAR ¥11,200 | 210.5 RevPAR ¥12,800 | 266.6 RevPAR ¥14,400 |
| 90% | 65.9 RevPAR ¥9,000 | 129.0 RevPAR ¥10,800 | 192.0 RevPAR ¥12,600 | 255.1 RevPAR ¥14,400 | 318.2 RevPAR ¥16,200 |
Source: MetroEngine Inc.; compiled by the HotelBank Editorial Team (same cost assumptions as Table 2)
The two shaded cells — ¥76.8mn at ADR ¥16,000 × 50% occupancy, and ¥42.3mn at ADR ¥10,000 × 80% occupancy — match Table 2 exactly. The same grid also holds two combinations that produce RevPAR ¥9,600: ADR ¥16,000 × 60% at ¥121.4mn and ADR ¥12,000 × 80% at ¥98.4mn, a gap of ¥23.0mn. The higher RevPAR climbs, the wider the profit spread within a single RevPAR level becomes.
Read the table across and it shows the profit gain from raising rate; read it down and it shows the gain from raising occupancy. The GOP increment from lifting occupancy by 10 points (a uniform ¥30.55mn in the ADR ¥12,000 column) is smaller than the increment from lifting ADR by ¥2,000 (a uniform ¥56.06mn along the 80% occupancy row), because incremental occupancy carries ¥3,150 of per-room variable cost with it while incremental rate carries only the 4% revenue-based commission. That asymmetry is the quantitative expression of the “same RevPAR, different GOP” result in Table 2.
Note, though, that fixed costs are held at ¥146.0mn in every cell. As Table 3 showed, if properties in the high-ADR band in fact carry heavier fixed costs, the right-hand columns need to be read down by that amount. What this table shows is the profit gap once cost structures are aligned — not the relative merits of one hotel category over another.
Estimating 2026 RevPAR by Hotel Category — Ryokan and Business Hotels Sit Level
From here the article works with observed data. MetroEngines Research’s estimated settled ADR (May 2026, settled basis) was calculated by category for each of the 47 prefectures, and the median of those prefecture medians is treated as “the level of a typical property nationally”. Multiplying that by the category-level room occupancy rates in the Japan Tourism Agency’s “Overnight Travel Statistics Survey” for May 2026 (second preliminary figures) gives the RevPAR estimates below.
| Category | Estimated settled ADR median of prefecture medians | ADR quartiles p25-p75 | Official occupancy JTA, May 2026 | RevPAR estimate | RevPAR range | N for ADR |
|---|---|---|---|---|---|---|
| Business hotels | ¥7,600 | ¥6,900-¥8,300 | 74.5% | ¥5,600 | ¥5,200-¥6,200 | 7,466 |
| City hotels | ¥9,300 | ¥8,200-¥13,400 | 73.0% | ¥6,800 | ¥6,000-¥9,800 | 1,108 |
| Resort hotels | ¥16,400 | ¥12,800-¥18,800 | 58.4% | ¥9,600 | ¥7,400-¥11,000 | 1,596 |
| Ryokan | ¥13,400 | ¥10,800-¥16,800 | 41.5% | ¥5,600 | ¥4,500-¥7,000 | 6,893 |
Source: MetroEngines Research (estimated settled ADR, May 2026, N=17,063 properties) and Japan Tourism Agency, “Overnight Travel Statistics Survey”, May 2026 (second preliminary figures); compiled by the HotelBank Editorial Team
Source: MetroEngines Research and Japan Tourism Agency, “Overnight Travel Statistics Survey”; compiled by the HotelBank Editorial Team
The most instructive result in the table is that ryokan and business hotels land at almost the same RevPAR. Ryokan estimated settled ADR of ¥13,400 is 1.77x the ¥7,600 of business hotels, but with official occupancy at 41.5% against 74.5%, both come out at roughly ¥5,600 (ryokan ¥5,560, business hotels ¥5,633, a ratio of 0.99). A high rate can be offset by occupancy. It is a textbook case of why folding both into the single axis of RevPAR is what makes room revenue comparable across categories.
The estimate carries several constraints. The first is the population. On the ADR side, the scope covers properties tracked by MetroEngines Research whose activity can be confirmed on OTAs, so ryokan, minshuku and simple lodgings that do not list on OTAs are excluded. On the occupancy side, the Japan Tourism Agency survey draws on a population of 75,665 establishments nationwide, and the May 2026 second preliminary figures are estimated from 20,854 responding establishments at a 45.9% effective response rate. The fact that numerator and denominator come from different surveys is a property of this estimate that has to be kept in mind. Care is also needed when reading year-on-year movement in the Japan Tourism Agency statistics themselves, because changes in the stratification basis of the sample can create discontinuities in the series.
RevPAR also moves substantially depending on which occupancy rate is applied. For the same month of May 2026, our own occupancy estimate derived from OTA inventory depletion was, on a nationally weighted basis, 89.3% for business hotels, 90.1% for city hotels, 82.9% for resort hotels and 82.4% for ryokan (N=22,212 properties, 1,351,342 rooms). Applying those figures instead puts RevPAR at roughly ¥6,800 for business hotels and roughly ¥11,000 for ryokan — 1.99x the official-occupancy figure in the ryokan case. The two are separate metrics with different populations and different denominators, and must not be mixed. That the divergence widens for ryokan, which hold more inventory off OTAs, follows directly from that difference in definition.
Forty-seven different routes to the same RevPAR
Even holding the category fixed, regions build RevPAR in different ways. The scatter plot below places estimated settled ADR (horizontal axis) against official occupancy (vertical axis) for business hotels in all 47 prefectures. The curve is an iso-RevPAR line joining the combinations that produce the same value as the national RevPAR estimate (about ¥5,600). Prefectures above and to the right of the curve exceed the national level; those below and to the left fall short.
Source: MetroEngines Research (estimated settled ADR, May 2026, N=7,466 properties) and Japan Tourism Agency, “Overnight Travel Statistics Survey”, May 2026 (second preliminary figures); compiled by the HotelBank Editorial Team
Miyagi and Kagawa illustrate the structure well. Miyagi runs ADR of about ¥8,000 at 66.2% occupancy; Kagawa runs about ¥7,500 at 71.3%. Both land at RevPAR of roughly ¥5,300 (¥5,314 and ¥5,329 respectively). The RevPAR gap is just ¥15, but ADR differs by 7.4% and occupancy by 5.1 points. One builds the same room revenue on rate, the other on occupancy. As Table 2 showed, those two do not yield the same profit: the Kagawa pattern, selling more room nights, carries heavier variable costs.
Business-hotel RevPAR ranges across a 3.5x spread over the 47 prefectures, topped by Tokyo at roughly ¥12,600. The median is about ¥5,500 and the quartiles run from about ¥4,700 to ¥6,200. Before benchmarking a property’s RevPAR against “the national average”, the practical starting point is to reset it against the level for the same category in the same prefecture.
How to Read the Distance to RevPAR Disclosed by Listed Hotel REITs
RevPAR is also the core metric Japan’s listed hotel REITs disclose in their monthly operating results. It is convenient as an industry benchmark, but compare it directly with a single property’s numbers and the levels usually do not match. The table below sets out the June 2026 monthly disclosures, after which the reasons are unpacked.
| Investment corporation | Scope as disclosed | Occupancy | ADR | RevPAR | RevPAR YoY |
|---|---|---|---|---|---|
| Japan Hotel REIT Investment Corporation | 29 hotels on variable-rent and similar schemes (total) | 81.2% | ¥18,509 | ¥15,023 | +1.7% |
| Invincible Investment Corporation | 103 domestic hotels (total) | 82.2% | ¥12,306 | ¥10,118 | −4.0% (same-property basis, 101 properties) |
| Ichigo Hotel REIT Investment Corporation | 24 hotels (total), excluding 2 closed for renovation | 80.6% | ¥8,872 | ¥7,147 | −9.6% |
Source: June 2026 monthly operating disclosures from each investment corporation; compiled by the HotelBank Editorial Team
Source: monthly REIT disclosures, MetroEngines Research and Japan Tourism Agency, “Overnight Travel Statistics Survey”; compiled by the HotelBank Editorial Team
RevPAR across the three runs from about ¥7,100 to about ¥15,000 — a 2.1x spread. That they diverge this much while looking at the same domestic hotel market in the same month is not because the metric is constructed differently, but because the portfolios are composed differently. The point becomes clear in the regional breakdown Japan Hotel REIT Investment Corporation discloses itself. In June 2026, Okinawa ran RevPAR of about ¥18,300 (76.0% occupancy, ADR about ¥24,000) while Tokyo ran about ¥9,500 (78.6%, about ¥12,000) — a 1.93x gap inside a single portfolio. A portfolio-wide figure is nothing more than the weighted average of that mix.
The distance to this article’s estimates follows the same logic. The national RevPAR estimate for business hotels is about ¥5,600, but that is the median of prefecture medians and includes regional Japan on equal footing. Restrict the same estimate to business hotels in Tokyo and it comes to roughly ¥12,600, level with the top of the REIT range in Table 5. The gap against REIT disclosures is a matter of geographic mix and property scale, not a methodological discrepancy.
Year-on-year figures also need care. Invincible Investment Corporation reported June 2026 RevPAR down 4.0% year on year (on a same-property basis covering the 101 properties comparable with the prior year; the absolute figures in the table above are totals for the 103 properties in scope), and in its monthly disclosure the corporation cites the pullback following the Osaka-Kansai Expo, a decline in travellers from China amid deteriorating Japan-China relations, and typhoon effects. Before using a single month’s movement as a benchmark, it is worth reading the explanatory factors the discloser has published. Note also that the corporation’s cumulative RevPAR for January-June 2026 was up 1.6% year on year — the single month and the cumulative figure point in opposite directions.
There are three practical points when using REIT disclosures to benchmark a property. First, always check the scope of the disclosure. “29 hotels on variable-rent and similar schemes”, “103 domestic hotels” and “24 hotels excluding those closed for renovation” in Table 5 are all scopes each corporation states explicitly, and the treatment of renovation closures and fixed-rent properties differs by corporation. Second, extract only the properties in the same region and the same category as your own. A portfolio-wide average is a product of mix, not a market level. Third, the ADR REITs disclose is a settled rate excluding consumption tax. The estimated settled ADR in this article is aligned to the same tax-excluded basis, but neither can be compared directly with tax-inclusive listed prices.
Choosing Between GOPPAR and TRevPAR, and the RevPAR Index (MPI / ARI / RGI)
RevPAR is not a universal tool. The denominator stays the same — available room nights — but changing what goes in the numerator produces three metrics with different jobs.
| Metric | Numerator | What it measures | Where it fits | A / B from Table 2 |
|---|---|---|---|---|
| RevPAR | room revenue | revenue efficiency of the rooms division | pricing and inventory decisions, daily management at rooms-focused properties | ¥8,000 / ¥8,000 |
| TRevPAR | total revenue (rooms + F&B + other) | revenue efficiency of the whole property | full-service properties and ryokan with F&B, banqueting and retail | ¥8,450 / ¥8,720 |
| GOPPAR | GOP (gross operating profit) | profit efficiency of the operation | management-agreement fee design, investment decisions, cross-category comparison | ¥2,375 / ¥1,592 |
Source: compiled by the HotelBank Editorial Team (the A / B column uses the Table 2 model, including on-property spend)
The right-hand column captures the difference in character between the three metrics succinctly. On RevPAR the two properties tie; on TRevPAR B is ahead; on GOPPAR A is ahead — the same two properties change places simply by changing the metric. As a practical rule of thumb: run daily operations on RevPAR at rooms-focused properties, add TRevPAR where the F&B share is high, and make investment and management-agreement decisions on GOPPAR.
RevPAR Index — positioning a property against its competitive set
An absolute RevPAR figure loses meaning once the market changes. Putting RevPAR ¥12,000 in Tokyo alongside ¥6,000 in a regional city tells you nothing about how well either is run. That is where the RevPAR Index comes in — a value relative to the competitive set (compset). Three indices work as a set.
MPI = own OCC ÷ compset OCC × 100
ARI = own ADR ÷ compset ADR × 100
RGI = own RevPAR ÷ compset RevPAR × 100 ≒ MPI × ARI ÷ 100
MPI (Market Penetration Index) shows how much share a property captures on occupancy, ARI (Average Rate Index) shows where it sits on rate, and RGI (Revenue Generation Index) — the product of the two — shows its share of total room revenue. 100 means parity with the compset; above 100 means earning more than the market. Applied to real data, it looks like the example below, with the compset set as “business hotels nationwide” and the subject as “business hotels in Ishikawa Prefecture (N=110 properties)”.
| Metric | Ishikawa | Nationwide (compset) | Index | Reading |
|---|---|---|---|---|
| Room occupancy rate | 79.3% | 74.5% | MPI 106.4 | 6.4% above the market on occupancy |
| Estimated settled ADR | ¥8,750 | ¥7,561 | ARI 115.7 | 15.7% above the market on rate |
| RevPAR | ¥6,939 | ¥5,633 | RGI 123.2 | 23.2% above the market on room revenue |
Source: MetroEngines Research (estimated settled ADR, May 2026) and Japan Tourism Agency, “Overnight Travel Statistics Survey”, May 2026 (second preliminary figures); compiled by the HotelBank Editorial Team
MPI 106.4 × ARI 115.7 ÷ 100 = 123.1, which matches RGI 123.2 to within rounding. What makes the decomposition useful is that when RGI falls below 100, it separates whether the cause sits on the occupancy side or the rate side. ARI of 110 with MPI of 85 gives RGI 93.5 — a diagnosis of holding rate but losing ground to the market on occupancy. Conversely, MPI of 110 with ARI of 85 says occupancy is there but rate still has headroom. Tracking movements in RevPAR alone hides that binary. For the boundary between rate-setting practice and rules-based automation, see Revenue Management vs Dynamic Pricing: 19,365 Hotels, Median 4 Moves.
A note on operating practice as well. With the RevPAR Index, the definition of the compset is everything. Unless it is built from properties in the same trade area, of the same grade and serving the same customer base, the index reflects nothing more than how the compset was chosen. In practice it is usual to build a set of three to eight properties, anchored on those that have demonstrably taken bookings away from you or whose pricing moves in step with yours. The index also has the advantage of not importing seasonality: because the market and the property face the same seasonal swing in both peak and trough, the index tracks operating performance more stably than a year-on-year comparison does. On how demand accumulates ahead of the stay date, see Booking Curves Across 47 Prefectures: +4.1pt Median Pickup from T-45.
Frequently Asked Questions
Q1. How does RevPAR differ from ADR?
The denominator. ADR divides room revenue by rooms sold, so vacancies never enter the calculation. RevPAR divides by rooms available for sale (total rooms × days), so vacancies are in the denominator. RevPAR is therefore always less than or equal to ADR, and the ratio between them is the occupancy rate (RevPAR ÷ ADR = OCC). At ADR ¥12,000 and RevPAR ¥7,200, occupancy is 60%.
Q2. What is a typical or average RevPAR?
It varies so much by category and region that a single national average is not an appropriate yardstick. This article’s estimates (May 2026) put business hotels at about ¥5,600, city hotels about ¥6,800, resort hotels about ¥9,600 and ryokan about ¥5,600. Even within business hotels, prefecture-level figures span about ¥3,600 to about ¥12,600 — a 3.5x range. Start any assessment of your own property against the level for the same category in the same prefecture.
Q3. Is it better to raise ADR or to raise OCC?
The contribution to RevPAR is the same for the same percentage change, but the contribution to profit is not. Lifting occupancy by 1% means more rooms sold and therefore more housekeeping, linen and consumables, all of which scale with rooms sold. Lifting ADR by 1% adds only the revenue-based distribution commission. In this article’s 100-room model, holding RevPAR equal still left the high-ADR pattern with 1.81x the GOP. That said, the ranking reverses once the high-ADR property’s fixed costs exceed 1.24x those of the high-occupancy property, so the calculation has to be run with your own variable unit costs and fixed-cost base.
Q4. Should I be looking at RevPAR or GOPPAR?
Use them for different purposes. RevPAR shows the efficiency of room revenue, which suits daily decisions on price and inventory. GOPPAR shows profit efficiency after costs, which suits management-fee design, investment decisions and comparison across categories. At properties where food, beverage, banqueting and retail carry significant weight, RevPAR — which sees only room revenue — can understate the property’s true strength, so use TRevPAR alongside it.
Q5. How do I calculate RevPAR in a month when rooms are closed for renovation?
Under the Japan Tourism Agency’s aggregation definition, available room nights are the number of physically existing rooms × days, so rooms taken out of service for renovation are in principle included in the denominator. An internal RevPAR that counts only rooms in service will not line up when placed alongside external statistics or REIT disclosures. There is nothing wrong with using a renovation-excluded basis for internal management, but the recommended practice is to maintain two series — one for external comparison and one for internal management — and always state which definition is in use. Monthly disclosures from listed hotel REITs also treat renovation closures differently by corporation, so check the stated scope of each disclosure.
Q6. Among MPI, ARI and RGI in the RevPAR Index, which matters most?
RGI (share of room revenue) is the final assessment, but MPI and ARI are what isolate the cause. When RGI falls below 100, a low MPI points to the occupancy side (selling capability, inventory allocation, lead-time management) and a low ARI to the rate side (pricing, plan structure, channel strategy). Because RGI ≒ MPI × ARI ÷ 100 holds, looking at all three at once makes structures such as “holding rate but losing on occupancy” readable at a glance. As a precondition, the compset must be built from the same trade area and the same grade.
Q7. Does RevPAR include consumption tax?
The ADR and RevPAR listed hotel REITs disclose are based on settled rates excluding consumption tax. The estimated settled ADR in this article is aligned to the same tax-excluded basis. Prices published on OTAs and similar channels, by contrast, are shown tax-inclusive, and averaging them as they stand does not give a RevPAR basis. When calculating for your own property, the standard approach is to put accounting room revenue (tax-excluded, with the treatment of accommodation tax and service charges stated) in the numerator.
Conclusion — RevPAR Is a Metric for Comparing on a Level Basis
The value of RevPAR lies in folding two metrics with different units — ADR and occupancy — onto a single axis, so that properties of different scale and category can be compared on the same footing. That ryokan and business hotels landed at almost the same RevPAR in the May 2026 estimates is exactly that folding at work. A structure in which a 1.77x gap in rate is almost entirely offset by a 33-point gap in occupancy is invisible without going through RevPAR.
At the same time, the same RevPAR does not deliver the same profit. In the 100-room model, one RevPAR of ¥8,000 split into annual GOP of ¥76.8mn and ¥42.3mn — and which of the two comes out ahead reverses depending on the fixed-cost level. RevPAR is a common language for comparison, not an answer to a decision. Getting to an answer means carrying variable unit costs, fixed-cost levels and on-property spend through to GOPPAR, and measuring position against the market with the RevPAR Index. Those three steps are what it takes to use RevPAR fully in practice.
* On the nature of these estimates: The RevPAR estimates in this article multiply MetroEngines Research’s estimated settled ADR (an estimate derived by applying category-specific adjustment factors to OTA listed prices) by the official room occupancy rates in the Japan Tourism Agency’s “Overnight Travel Statistics Survey”. The two come from surveys with different populations, and the result does not match the accounting RevPAR of any individual property. Please use them as reference values for reading relative differences in level across categories and regions.
Related Reading
- What Is Hotel ADR? Settled Rates 34-57% of Listed Prices, 2026
- Revenue Management vs Dynamic Pricing: 19,365 Hotels, Median 4 Moves
- Booking Curves Across 47 Prefectures: +4.1pt Median Pickup from T-45
- June 2026 Occupancy 56.2%: Guest-Nights per Room in 47 Prefectures
- Snow as Cost or Asset: Winter RevPAR 53% vs Winter ADR 2.66x
References and Sources
■ Data sources
Estimated settled ADR is MetroEngines Research data on a May 2026 settled (historical) basis; the national level is the median of the medians for each of the 47 prefectures × 4 categories (N=17,063 properties). Room occupancy rates are the official prefecture- and category-level figures from the Japan Tourism Agency’s “Overnight Travel Statistics Survey”, May 2026 (second preliminary figures). Monthly REIT results are quoted as disclosed by each investment corporation for June 2026.
■ Model assumptions
RevPAR by category was calculated as estimated settled ADR × official room occupancy rate. The 100-room P&L (Tables 2, 3 and 8) uses common assumptions of 36,500 available room nights a year, ¥3,150 per room sold in variable costs that scale with rooms sold (housekeeping and linen ¥2,400 + consumables ¥350 + variable utilities ¥400), distribution commissions at 4% of revenue, and fixed costs of ¥146.0mn; Table 8 varies only ADR and occupancy on those same assumptions. On-property spend is set at ¥900 per room sold with a 60% gross margin.
■ Limitations and caveats
The RevPAR estimates draw the numerator (ADR) and the occupancy rate from separate surveys, and do not match the accounting RevPAR of any individual property. Estimated settled ADR is an estimate derived by applying category-specific adjustment factors to OTA listed prices; cross-checked against REIT disclosures, the median error is 6.6%. Ryokan, minshuku and simple lodgings that do not list on OTAs are outside the ADR population. Because the official occupancy rate and the OTA-inventory-based estimated occupancy rate have different populations and different denominators, the two are never mixed within a single table or chart here. All figures in the 100-room model rest on model assumptions and are not the results of any specific property.
■ Government statistics
- Japan Tourism Agency, “Overnight Travel Statistics Survey (May 2026 second preliminary figures; June 2026 first preliminary figures)” (published 31 July 2026)
- Japan Tourism Agency, “Overnight Travel Statistics Survey” (survey outline and historical tables)
■ Monthly REIT disclosures
- Invincible Investment Corporation, “Notice Concerning Operating Status for June 2026” (24 July 2026)
- Japan Hotel REIT Investment Corporation, monthly operating status (June 2026)
- Ichigo Hotel REIT Investment Corporation, “Monthly Operating Results” (published 27 July 2026)
■ Market data
- MetroEngines Research — estimated settled ADR (May 2026, 47 prefectures × 4 categories, N=17,063 properties) and OTA-inventory-based estimated occupancy (N=22,212 properties, 1,351,342 rooms)