

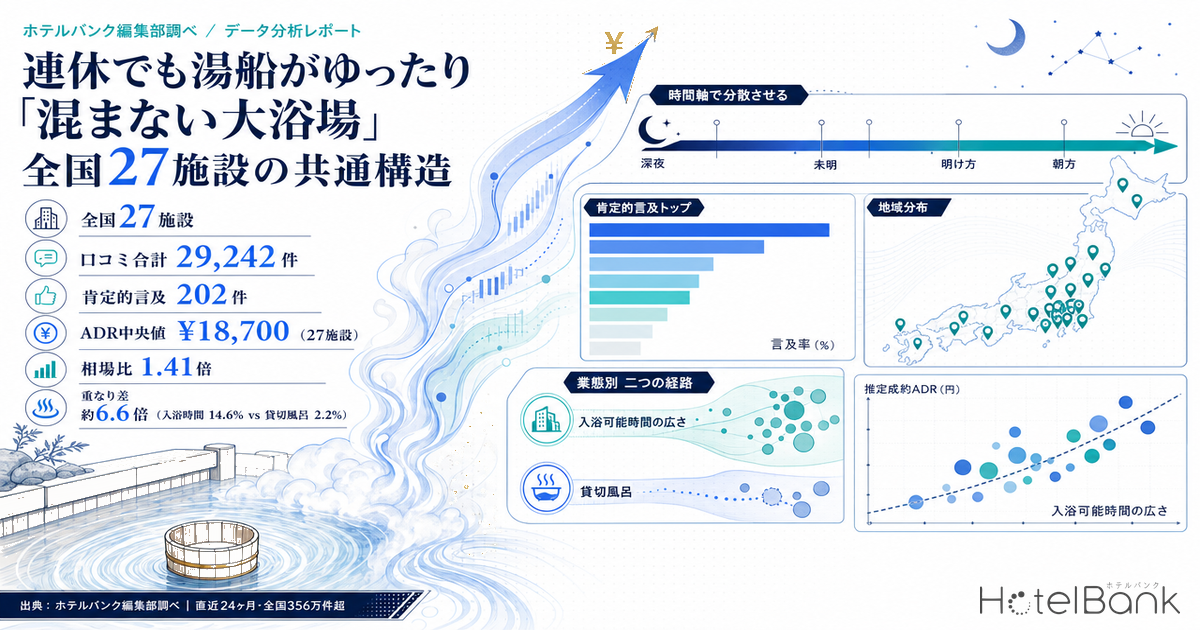
When choosing a hotel for a long weekend, one question ranks alongside price and cuisine: will the large public bath be crowded? Yet the absence of crowding appears neither in the facility list nor in the rate table. For this analysis we applied semantic analysis to guest reviews and extracted, from across Japan, the properties spoken of positively — “it was empty,” “we could soak at our leisure.” We then layered in mentions of bathing hours, private baths and the large bath itself to structure what actually creates that sense of space.
Metric Definitions Used in This Article
- Mention rate: the share of a property’s total reviews that touch on the theme in question. Mention rate is not a rating score. It measures how often something is talked about, which is a different indicator from star ratings or satisfaction.
- Positive mention: among remarks about crowding, those that describe the margin of space in positive terms — “it was empty,” “we could soak at our leisure.” Negative mentions are tallied separately.
- ADR (average daily rate): an estimated settled rate (tax-exclusive equivalent) derived by applying a category-specific adjustment coefficient to the lowest publicly listed plan level on OTAs and similar channels (two guests per room, per-room rate, tax included). Cross-checked against property-level results disclosed by listed hotel REITs (91 properties, most recent three months), the median error is approximately 7%. It is an estimate and differs from each property’s actual transacted price or accounting figures. Area-level ADR is the median across the target properties.
- Aggregation period: reviews posted over the most recent 24 months. This is not a tally restricted to long weekends or peak season (see “Limits of This Analysis” below).
- — 41 properties nationwide were spoken of positively for an uncrowded large bath. After excluding 14 properties where negative mentions ran neck and neck, the published list narrows to 27 properties.
- — The 27 listed properties drew 29,242 reviews in total, of which 202 were positive mentions of low crowding. Mention rates cluster around 1%, making this a theme that is rarely raised in the first place.
- — What overlaps with the sense of spaciousness is not the private bath but the breadth of bathing hours. Of the 41 properties ranked nationally for bathing hours, 6 also appear here; for private baths, only 2 of 90 do.
- — The 27 split into 19 onsen-resort-type and 8 urban-type properties. The onsen type has a median of 111 rooms and a median ADR of roughly ¥26,200; the urban type, 185 rooms and roughly ¥11,100 — two different characters.
- — Median ADR across the 27 is about ¥18,700, or 1.41x the median for the same prefecture and same category. Low crowding functions as a non-price driver that does not rely on discounting.
Counting the population first — 41 properties nationwide are described as “empty”
The starting point of the analysis is to count, exhaustively and nationwide, the properties that have accumulated a meaningful number of positive mentions about crowding. Aggregating prefecture by prefecture, and limiting the field to properties with at least 20 total reviews, we extracted those with five or more positive mentions of low crowding. The result was 41 properties nationwide.
That figure of 41 is itself instructive. Running the same procedure for properties spoken of positively about the breadth of bathing hours yields 41 properties; for private baths, 90. In other words, “it wasn’t crowded” is a strikingly rare way for guests to talk about the bathing experience. Equipment can be named; an uncrowded state is harder to name.
On the coverage of the population, one point should be stated plainly. For 46 prefectures we were able to enumerate every qualifying property, but the tally did not complete for Nagano Prefecture alone. That said, we have confirmed that the prefecture has zero properties with six or more positive mentions, so the likelihood of a top-ranking property being missed is limited. No prefecture hit the extraction ceiling, so no counts were truncated.
| Step | Condition | Properties |
|---|---|---|
| 1. Scope | Properties with 20+ reviews in the most recent 24 months | Nationwide |
| 2. Extraction | 5+ positive mentions of low crowding | 41 properties |
| 3. Exclusion | Properties where negative mentions rival positive ones | −14 properties |
| 4. Published | Properties where positives clearly outweigh negatives | 27 properties |
Source: HotelBank Editorial Team research
Counting positives and negatives together — why 27, not 30
This is the most important step in the analysis. If you count only positive mentions and rank on them, however many negative mentions have piled up against the same property remains invisible. Re-tallying both sides, we found that among the 41 properties, 14 had negative mentions equal to or greater than positive ones. Some carried nearly three times as many negatives as positives.
Listing those as “properties where you can bathe at your leisure” would be inaccurate for readers and for the properties alike. We therefore kept only properties where positive mentions account for at least 60% of the total, and the published list came to 27. The original intent was 30, but we prioritized what the data supports. The 14 excluded properties are reported as a count only, without names.
Whether or not this step is applied changes the lineup substantially. Larger properties collect more reviews overall, so positive mentions accumulate naturally, and a ranking built on positives alone carries a bias favoring big-box properties. Looking at the negative side at the same time cancels much of that bias.
27 properties nationwide where the bath feels unhurried
Below are the final 27 properties, ordered primarily by number of positive mentions and, where tied, by mention rate. The 27 drew 29,242 reviews in total, of which 202 were positive mentions touching on low crowding.
Source: HotelBank Editorial Team research
| # | Property | Prefecture | Category | Rooms | Pos. | Neg. | Mention rate | ADR | Also ranked nationally for |
|---|---|---|---|---|---|---|---|---|---|
| 1 | Gero Onsen Suimeikan (下呂温泉 水明館) | Gifu | Ryokan | 264 | 28 | 5 | 1.00% | ¥21,913 | Bath hours / Large bath |
| 2 | Arima Gyoen (有馬御苑) | Hyogo | Ryokan | 65 | 17 | <4 | 1.81% | ¥32,407 | — |
| 3 | Asaya Hotel (あさやホテル) | Tochigi | Ryokan | 192 | 13 | 5 | 0.57% | ¥33,862 | — |
| 4 | Gensen Yu-no-Yado Sen-no-Tani (源泉湯の宿 千の谷) | Gunma | Ryokan | 110 | 9 | <3 | 1.14% | ¥14,306 | Bath hours |
| 5 | Ooedo Onsen Monogatari Premium Hotel New Shiobara (大江戸温泉物語Premium ホテルニュー塩原) | Tochigi | Ryokan | 271 | 8 | <3 | 1.14% | ¥14,733 | — |
| 6 | Kinugawa Onsen Hotel (鬼怒川温泉ホテル) | Tochigi | Ryokan | 162 | 8 | <3 | 0.81% | ¥26,197 | — |
| 7 | Nagoya Crown Hotel (名古屋クラウンホテル) | Aichi | Business | 613 | 8 | 5 | 0.40% | ¥8,579 | Bath hours / Large bath |
| 8 | Hyoe Koyokaku (兵衛 向陽閣) | Hyogo | Ryokan | 125 | 7 | <4 | 0.85% | ¥42,245 | — |
| 9 | Urabandai Lake Resort Geihinkan Nekoma Rikyu (裏磐梯レイクリゾート 迎賓館 猫魔離宮) | Fukushima | Resort | 83 | 6 | 2 | 1.64% | ¥16,074 | — |
| 10 | Ochanomizu Hotel Shoryukan (お茶の水ホテル 昇龍館) | Tokyo | Ryokan | 42 | 6 | <4 | 1.35% | ¥8,987 | — |
| 11 | Super Hotel Premier Osaka Hommachi Ekimae (スーパーホテル Premier大阪本町駅前) | Osaka | Business | 170 | 6 | <4 | 1.09% | ¥13,078 | — |
| 12 | Hotel Route Inn Grand Tokyo Asakusabashi (ホテルルートインGrand東京浅草橋) | Tokyo | Business | 200 | 6 | <4 | 0.74% | ¥11,815 | — |
| 13 | Hotel & Spa Anda Resort Izukogen (ホテル&スパ アンダリゾート伊豆高原) | Shizuoka | Resort | 68 | 6 | <3 | 0.74% | ¥35,319 | Private bath |
| 14 | Spa Hotel Alpina Hida Takayama (スパホテルアルピナ飛騨高山) | Gifu | Business | 119 | 6 | <2 | 0.60% | ¥10,451 | — |
| 15 | Grandia Housen (グランディア芳泉) | Fukui | Ryokan | 111 | 6 | <2 | 0.55% | ¥40,920 | — |
| 16 | Tenseien (天成園) | Kanagawa | Ryokan | 198 | 6 | <3 | 0.49% | ¥26,580 | Bath hours |
| 17 | Kurokawa Onsen Yukyo-no-Hibiki Yusai (黒川温泉 湯峡の響き 優彩) | Kumamoto | Ryokan | 55 | 6 | <3 | 0.46% | ¥31,595 | Private bath |
| 18 | Hotel Tenbo (ホテル天坊) | Shizuoka | Ryokan | 53 | 5 | <3 | 1.34% | ¥23,130 | — |
| 19 | Old England Dogo Yamanote Hotel (オールドイングランド 道後山の手ホテル) | Ehime | City | 70 | 5 | <2 | 1.27% | ¥16,934 | — |
| 20 | Kutsurogi-no-Yado Shintaki (くつろぎ宿 新滝) | Fukushima | Ryokan | 81 | 5 | <2 | 1.00% | ¥18,746 | — |
| 21 | Sanco Inn Nagoya Nishiki Shiki-no-Yu (三交イン名古屋錦~四季乃湯~) | Aichi | Business | 149 | 5 | <3 | 0.91% | ¥10,430 | — |
| 22 | Spaland Hotel Naito (スパランドホテル内藤) | Yamanashi | Business | 206 | 5 | <2 | 0.85% | ¥9,862 | — |
| 23 | Yumekaiyu Awajishima (夢海游 淡路島) | Hyogo | Ryokan | 101 | 5 | <4 | 0.56% | ¥20,591 | — |
| 24 | Hotel Zuiho (ホテル瑞鳳) | Miyagi | Ryokan | 117 | 5 | <3 | 0.41% | ¥32,394 | — |
| 25 | Marumine (丸峰) | Fukushima | Ryokan | 119 | 5 | <2 | 0.36% | ¥18,616 | — |
| 26 | Yumoto Fujiya Hotel (湯本富士屋ホテル) | Kanagawa | Ryokan | 149 | 5 | <3 | 0.27% | ¥27,612 | — |
| 27 | APA Hotel & Resort Nishi-Shinjuku Gochome Eki Tower (アパホテル&リゾート〈西新宿五丁目駅タワー〉) | Tokyo | Business | 710 | 5 | <4 | 0.19% | ¥15,195 | — |
Entries such as “<3” in the “Neg.” column indicate that the figure falls below the prefecture’s complete-tally threshold (for example, “<3” means fewer than three negative mentions). “Also ranked nationally for” indicates that the property is in the national top group for the bathing-hours, private-bath or large-bath theme. Hotel Tenbo (ホテル天坊) is located in Izu-Nagaoka, Shizuoka Prefecture.
Source: HotelBank Editorial Team research
Bathing hours beat private baths — what the overlaps reveal
So what produces the sense of spaciousness? Comparing the properties that rank highly for low crowding with those that rank nationally on other bath-related themes produces a clear-cut difference.
Forty-one properties rank nationally for the breadth of bathing hours, and 6 of them also rank for low crowding. By contrast, 90 properties rank nationally for private baths, yet only 2 overlap with low crowding. The theme with a population more than twice as large produces only a third of the overlap — an inversion.
The reading is straightforward. A private bath is an experience for the single group that managed to reserve it; it does not change how crowded the large bath itself is. Extending bathing hours, by contrast, spreads the same number of users across a longer window. Round-the-clock bathing, or opening late at night and early in the morning, directly lowers density at peak times. The sense of spaciousness, in other words, is tied far more strongly to widening the time axis than to adding tubs. The value of private baths on their own axis is a separate matter — their role in lowering the barrier to bathing for inbound guests is a distinct question from crowding.
Source: HotelBank Editorial Team research
Note that mentions of bathing hours account for just 0.087% of the more than 3.56 million reviews nationwide (2,010 properties), making it an infrequently discussed theme to begin with. The overlap tells us it is rarely talked about, but consequential when it is.
Onsen-resort type and urban type — two routes to the same result
By category, the 27 break down into 17 ryokan, 7 business hotels, 2 resorts and 1 city hotel. Onsen-resort type (ryokan and resorts) accounts for 19 properties and urban type (business and city hotels) for 8 — two groups of distinctly different character.
The onsen-resort type has a median of 111 rooms and a median ADR of roughly ¥26,200. Being smaller, it carries fewer guests relative to bath capacity — a structural margin. The urban type, by contrast, has a median of 185 rooms and a median ADR of roughly ¥11,100: larger in scale, more modest in rate. That guests still describe it as “empty” is likely because bathing times are dispersed. On business trips, return times to the hotel vary, and late-night or early-morning use is common. This is precisely where breadth of bathing hours pays off. A comparable inversion — urban business hotels overtaking onsen ryokan on bathing-facility sentiment — also shows up in review data on sauna-related praise.
By region: Kanto 9, Chubu 8, Kansai 4, Hokkaido and Tohoku 4, Kyushu 1, Chugoku and Shikoku 1. Kanto and Chubu together account for 60% of the total, reflecting the depth of the onsen destinations near the Tokyo metropolitan area (Kinugawa, Shiobara, Hakone) and those in Chubu (Gero, Hida-Takayama, Izu).
Source: HotelBank Editorial Team research
Source: HotelBank Editorial Team research
The relationship with price — what “non-price driver” precisely means
Calling an uncrowded large bath a non-price driver requires care. It does not mean “the appeal of a cheap hotel.” Median ADR across the 27 properties is about ¥18,700. Against comparable groups in the same prefecture and the same category, that sits at 1.41x the median. Properties described as places you can soak at leisure are, if anything, being chosen at rates above the market.
The precise formulation is therefore this: low crowding is an element that lifts satisfaction without lowering price, and it can substitute for discount competition. Causation, however, cannot be asserted. Properties able to leave slack in their baths are properties able to invest in bath area per room in the first place, and that shows up in rate as well — a common underlying factor could explain both. We limit ourselves here to describing a relationship in which the sense of spaciousness and a price premium coexist.
At the same time, the 8 urban-type properties have a median ADR of roughly ¥11,100, and it is worth noting that the result is achievable without a high rate. Room remains to get there through operational design.
Implications for operators — headroom to convert into stay value
The structure above can be organized as upside for the property side. Each of these builds on existing strengths rather than replacing them.
| Action | Data behind it | Expected effect |
|---|---|---|
| Extend bathing hours | 6 of the 41 properties ranked nationally for bathing hours (14.6%) also rank for low crowding; for private baths, only 2 of 90 (2.2%) | Lowers density at peak times and raises perceived value with no capital investment |
| Add private-bath slots | 2 of the 27 properties also rank nationally for private baths; the standalone contribution is limited | Effective for anniversary and family demand. Design it separately from crowding relief |
| Add changing-room lockers and wash stations | Perceived crowding arises more readily from waiting at the changing room and wash stations than at the tub | Clears congestion without enlarging the bath — a capital-efficient option |
| Make occupancy visible | Reviews of top-ranked properties include remarks to the effect that current occupancy of the bath is visible | Encourages natural dispersal of use; compounds with wider time windows |
Source: HotelBank Editorial Team research
Extending bathing hours is especially capital-efficient because it can be done without enlarging the bath. Redesigning overnight cleaning windows and reworking staff shifts are required, but there is room to compete on the “you can bathe at your leisure” axis with no additional construction spend. The tighter the location’s ceiling on rate — as with urban hotels — the greater that room.
Limits of This Analysis
For readers weighing the findings, the following should be stated explicitly.
- This is not a long-weekend-only tally. It covers all reviews from the most recent 24 months and is not a measurement of crowding restricted to major holiday periods or peak season. Actual crowding during a long weekend may be governed by factors outside this ranking.
- Mention rate is not a rating score. Being talked about often and being rated highly are different things.
- Results are influenced by review volume. Excellent properties with few reviews may fall outside the scope for failing to meet the conditions.
- The tally for Nagano Prefecture is incomplete. We have, however, confirmed that it has zero properties with six or more positive mentions.
- Where negative mention counts fall below a prefecture’s complete-tally threshold, only the upper bound is shown.
Conclusion
An uncrowded large bath appears in neither the facility sheet nor the rate card, yet guests do put it into words. Twenty-seven properties nationwide met the conditions, splitting into two routes: small and mid-sized ryokan in onsen destinations, and large urban hotels.
The common factor bridging them is the breadth of bathing hours. Rather than the “exclusive use” answer of the private bath, the answer of widening the time axis and dispersing usage is what correlates strongly with the sense of spaciousness. It is a lever available without expanding the bath, and it is where the headroom lies to raise stay value without lowering price.
For travelers who want an unhurried soak over a long weekend, and for operators thinking about how to protect the guest experience on high-occupancy dates, “breadth of time” looks like the shared key.
Related Reading
References and Sources
■ Data sources
Semantic analysis of guest reviews (most recent 24 months, more than 3.56 million reviews nationwide). Four themes — crowding, bathing hours, private baths and the large bath — were aggregated at the prefecture level, and per-property mention counts, mention rates and the positive/negative breakdown were calculated. ADR uses each property’s estimated settled rate (monthly average of results from July 2025 to June 2026).
■ Assumptions
The extraction conditions are “20 or more total reviews in the most recent 24 months” and “five or more positive mentions of low crowding.” From that set, only properties where positive mentions account for at least 60% of positives plus negatives were published. The ADR comparison (1.41x) uses the median of the property group in the same prefecture and same category as its benchmark. The category and regional breakdowns are based on the composition of the 27 published properties.
■ Limits and caveats
This is not a tally restricted to long weekends or peak season; it covers all reviews from the most recent 24 months. Mention rate is not a rating score but an indicator of how often something is discussed. The tally for Nagano Prefecture did not complete (we have confirmed it has zero properties with six or more positive mentions). Where negative mentions fall below a prefecture’s complete-tally threshold, only the upper bound is shown. ADR is an estimate and differs from actual transacted prices.
■ Review analysis
- HotelBank Editorial Team research — semantic analysis of guest reviews (covering more than 3.56 million reviews nationwide over the most recent 24 months; 29,242 reviews in total across the 27 published properties)
■ Price data
- MetroEngines Research — estimated settled ADR (monthly average of results from July 2025 to June 2026); benchmark by prefecture and category
■ Public statistics