

Kasumigaseki Capital (TSE: 3498) announced on Friday, August 21, 2026 that it had acquired all shares of Wakayama Marina City Co., Ltd. through its consolidated subsidiary fav hospitality group. The target company operates, as a single business, the all-ocean-view Wakayama Marina City Hotel (和歌山マリーナシティホテル), Kuroshio Market (黒潮市場), known for its live tuna-carving shows, the natural hot spring Kishu Kuroshio Onsen (紀州黒潮温泉), one of the largest yacht clubs in the Kansai region, and the theme park Porto Europa (ポルトヨーロッパ). This is not the purchase of a single hotel: it is a share deal that takes over an entire man-made island resort together with all of its visitor attractions.
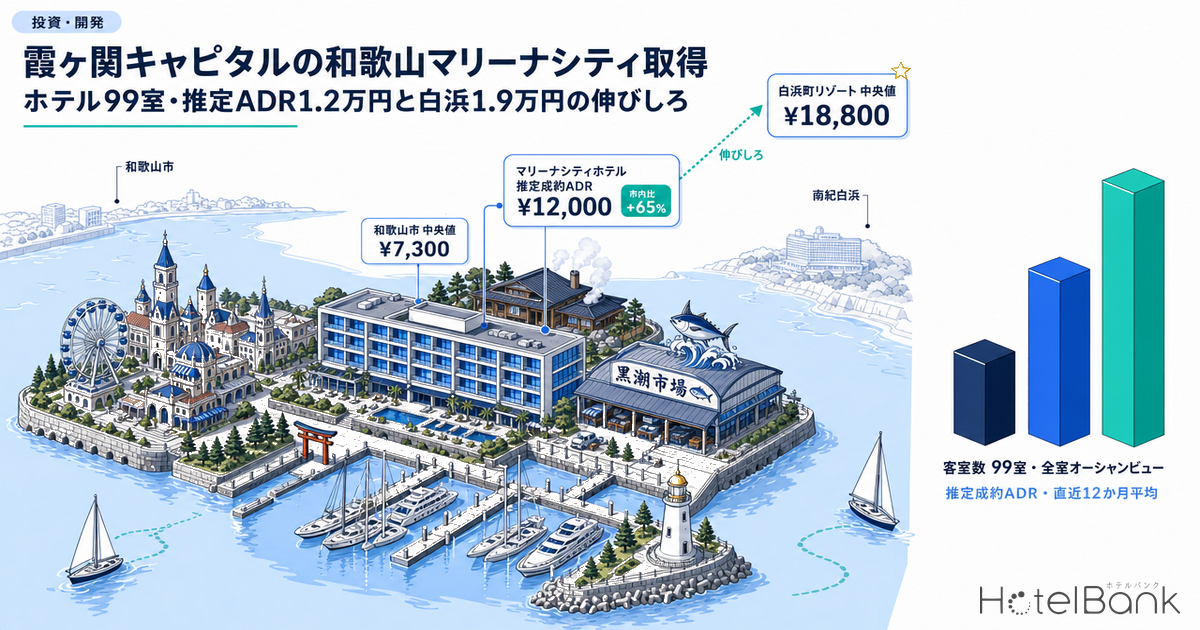
In this article we set out the structure of this “all-in-one” acquisition, place the estimated settled ADR of the 99-room hotel alongside Wakayama City and the Nanki-Shirahama resort belt, and estimate how much headroom there is in room rates. To give the conclusion first: Marina City Hotel’s estimated settled ADR averaged about ¥12,000 over the last 12 months, 65% above the Wakayama City median of about ¥7,300. Meanwhile, the median for resort hotels in Shirahama Town is about ¥18,800, and the gap to that level is the upside in room revenue. For 99 rooms, moving the rate up to the Shirahama resort band would add about ¥120M a year in room revenue at the same occupancy. The acquisition price and the target company’s results have not been disclosed, and we do not estimate them here.
How this differs from our earlier coverage: We have covered a Kasumigaseki Capital acquisition once before, a ryokan rebrand in Uji, but that deal involved a single ryokan. For Wakayama Prefecture, we have looked at the prefecture-wide rate hierarchy, including a comparison of the Kumano side with Shirahama and our prefecture investment maps. This article differs in that it focuses on a single deal in which an entire company running a mixed-use resort, including a theme park, hot springs and retail, is acquired, and reads the relationship between visitor attractions and room rates.
Metric Definitions Used in This Article
- ADR (average daily rate): an estimated settled rate (tax-excluded equivalent), calculated by applying a property-type correction factor to the lowest-priced plan level each property publishes on OTAs and similar channels (two guests per room, per-room rate, tax included). Checked against property-level results disclosed by listed hotel REITs (91 properties, most recent 3 months), the median error is about 7%. These are estimates and differ from each property’s actual settled prices and accounting figures. Area-level ADR is the median of the properties covered (the level of a typical property in the area).
- OCC (occupancy rate): in this article’s scenarios, we use the room occupancy rate (final figures) from the Japan Tourism Agency’s Overnight Travel Statistics Survey as the assumption. We do not calculate or report the occupancy of individual properties.
- RevPAR: ADR × OCC (revenue per available room).
- Data sources: MetroEngines Research, Japan Tourism Agency, Ministry of Land, Infrastructure, Transport and Tourism (MLIT)
- — Acquired all shares of the operating company — On August 21, 2026, Kasumigaseki Capital made Wakayama Marina City Co., Ltd., which runs a 99-room hotel together with a hot spring, seafood market, theme park and marina, a subsidiary. The acquisition price was not disclosed
- — Estimated settled ADR of ¥12,025 (Sep 2025–Aug 2026 average) is about 1.65 times the Wakayama City property median of ¥7,274 (N=42–45), placing it in the resort price band within the city
- — Shirahama Town resort-hotel median of ¥18,758 (N=19–22) is about ¥6,700 away. Monthly figures range from ¥9,010 in June to ¥15,567 in August; lifting the off-season months is the headroom
- — 22 properties / 780 rooms within 5 km (2026): this is the only resort of 99-room scale, sitting between the corporate-demand business hotels and the small ryokan of Wakaura
- — Moving the rate up to the Shirahama resort band lifts annual room revenue from ¥221M to ¥345M (occupancy fixed at the 2025 figure for resort hotels in Wakayama Prefecture). Each ¥1,000 added to ADR is worth about ¥18.4M a year
Buying the island’s operator, not just a hotel — the structure of the deal
This acquisition took the form of buying 100% of the operating company’s shares, rather than buying the assets (real estate) alone. In a share acquisition, the land and buildings held by the target company, the business licences of each facility, employment relationships with staff and contracts with business partners are all carried over with the company. Licence succession and tax burden vary by lodging acquisition scheme; the great advantage of a share acquisition is that the business can be taken over without suspending operations.
Wakayama Marina City is a man-made island in Wakayama Bay, developed as the main venue of the World Resort Expo held in 1994. The island has lodging, a hot spring, a market, a marina and a theme park, arranged so that each supports the others’ visitor traffic. Lining up the facilities included in this acquisition shows that only one building, the hotel, has guest rooms; all the rest are attractions that also draw day visitors.
| Facility | Function | Effect on room rates (expected pathway) |
|---|---|---|
| Wakayama Marina City Hotel (和歌山マリーナシティホテル) | Lodging (99 rooms, all ocean view) | Room revenue itself. The view underpins the rate |
| Kishu Kuroshio Onsen (紀州黒潮温泉) | Natural hot spring (open to day visitors) | Positions the property as a “resort with hot springs”; can be built into stay plans |
| Kuroshio Market (黒潮市場) | Seafood market, tuna-carving show | Core draw for day visits; a path that connects the food experience to overnight stays |
| Porto Europa (ポルトヨーロッパ) | Theme park | Reason for families to visit; room to design stay plans that include park admission |
| Yacht club | Marina (one of the largest in Kansai) | Harbour-view scenery asset; a touchpoint with affluent guests and members |
The Kasumigaseki Capital group has developed and operated hotels under brands such as “fav” and “seven x seven”. In this announcement, it said it would bring its know-how in digital-driven operational improvement and design-led spaces, and expand its business beyond lodging into running large mixed-use resorts that include theme parks and tourist facilities. Unlike the turnaround of a stand-alone hotel, the defining feature of this acquisition is that one company can design pricing and visitor flows for lodging, hot springs, food and leisure at the same time.
65% above the Wakayama City median, just short of the Shirahama resort band — the estimated settled ADR hierarchy
So where does Marina City Hotel’s room rate sit within the prefecture? According to MetroEngines Research data, on a 12-month average from September 2025 to August 2026, the estimated settled ADR (property median) for Wakayama City as a whole was ¥7,274, and ¥6,031 for business hotels. Wakayama City’s monthly values stayed within a range of ¥6,360–¥8,316, with little swing across the year, which suggests a market centred on urban business demand.
By contrast, Marina City Hotel’s estimated settled ADR averaged about ¥12,000 over the same period (¥9,000–¥15,600 by month). That is about 1.65 times the Wakayama City median and about twice the city’s business-hotel median, placing it clearly in the resort price band within the city. Turning to Nanki (southern Kii), Shirahama Town as a whole comes to ¥14,825, Shirahama resort hotels alone to ¥18,758, Tanabe City to ¥11,995 and Nachikatsuura Town to ¥12,857. Marina City Hotel is roughly level with the Kumano/Katsuura side, and about ¥6,700 short of the Shirahama resort-hotel band.
| Area / segment | Estimated settled ADR (12-month average) | Properties covered (monthly) | Ratio to hotel |
|---|---|---|---|
| Wakayama City, business hotels | ¥6,031 | N=26–27 | 0.50x |
| Wakayama City, all | ¥7,274 | N=42–45 | 0.60x |
| Tanabe City, all | ¥11,995 | N=28–30 | 1.00x |
| Wakayama Marina City Hotel | ¥12,025 | Single property | — |
| Nachikatsuura Town, all | ¥12,857 | N=15 | 1.07x |
| Shirahama Town, all | ¥14,825 | N=54–59 | 1.23x |
| Shirahama Town, resort hotels | ¥18,758 | N=19–22 | 1.56x |
Laid out month by month, the structure of the gap becomes clearer. The Shirahama resort-hotel median holds in the ¥16,000s even in off-season months and rises to ¥24,618 in August. Marina City Hotel also climbs into the ¥15,500s in January and August, so it already has the ability to raise rates in peak periods. In June, however, it falls to ¥9,010, and lifting the off-season months emerges as the headroom in room rates.
The only 100-room-class resort within 5 km — surrounding supply and positioning
Lodging supply within a 5 km radius of the hotel grew from 17 properties / 520 rooms in 2018 to 22 properties / 780 rooms in 2026, according to the MetroEngines Research property master (properties open and not yet closed at the end of each year). Most of the increase came from a single 248-room business hotel that opened in front of Kainan Station in 2024, i.e. supply on the business-demand side. The properties within the same radius that operate as resorts or ryokan are mainly small inns in Wakaura, across the bay.
Plotting the 10 properties within the radius for which estimated settled ADR could be calculated in every one of the last 12 months on two axes, room count and rate, the market splits into two clusters. One is the corporate-demand business hotels around Kainan Station and Kimiidera (5 properties / 466 rooms, median estimated settled ADR ¥6,791); the other is the small ryokan and resorts of Wakaura (4 properties / 99 rooms, median about ¥22,100). Marina City Hotel is the only property with a 99-room scale in the rate band between them, and within 5 km, this hotel alone occupies the seat of “a resort with a meaningful room count”.
| Property (anonymised except the hotel) | Type | Rooms | Distance | Estimated settled ADR |
|---|---|---|---|---|
| Wakayama Marina City Hotel (和歌山マリーナシティホテル) | Resort | 99 rooms | — | ¥12,025 |
| Business hotel A near Kainan Station | Business | 248 rooms | 3.2km | ¥7,390 |
| Business hotel B in Kimiidera | Business | 100 rooms | 3.3km | ¥6,791 |
| Business hotel C in Kainan | Business | 62 rooms | 2.9km | ¥6,239 |
| Business hotel D in Kimiidera | Business | 35 rooms | 3.6km | ¥4,619 |
| Business hotel E in Kainan | Business | 21 rooms | 2.8km | ¥7,667 |
| Ryokan F in Wakaura | Ryokan | 36 rooms | 3.9km | ¥34,272 |
| Ryokan G in Wakaura | Ryokan | 20 rooms | 4.5km | ¥29,669 |
| Resort H in Wakaura | Resort | 28 rooms | 4.0km | ¥14,450 |
| Ryokan I in Wakaura | Ryokan | 15 rooms | 4.0km | ¥11,357 |
How lodging with its own attractions supports room rates — all-in-one versus hotel-only acquisitions
When a hotel is acquired on its own, the ceiling on its room rate is set by its location and the pulling power of its surroundings. A buyer can change the design of rooms, food and beverage and sales, but cannot reach “the reason to come to that place” itself. Acquire the theme park, hot spring and market as well, and the operator can control the very motive for visiting. Designing stay products that bundle park admission, hot-spring access and meals, converting day visitors into overnight guests, and extending length of stay on the assumption that guests will circulate around the island: these levers give the room rate a footing that a hotel-only acquisition does not.
The rate hierarchy data are consistent with this view. Behind the Shirahama resort-hotel band holding a high level within the prefecture is, we believe, the layered presence of local attractions such as Shirarahama beach, the hot-spring town and Adventure World. Wakayama City, by contrast, has a city median within a level centred on corporate demand. That Marina City Hotel achieves a rate well above the city median can be read as the result of already carrying the island’s hot spring, market and theme park on its back. Rate gaps have several causes, including property grade and room mix, and cannot be explained by attractions alone, but an all-in-one acquisition buys the “machinery that supports the rate” along with the hotel.
Guest ratings show this strength clearly. Analysing 835 guest reviews from the last 24 months compiled by the HotelBank Editorial Team, 194 reviews (23.2%) mentioned the view from the room, and 189 of them were positive. Hot springs were mentioned in 217 (26.0%) and meals in 230 (27.5%), with positive comments making up the large majority in each case. Comments such as “…we could relax while looking out over the yacht harbour…” and “…the marina and Kuroshio Onsen are within walking distance…” show that the view and the proximity of the island’s facilities are valued as part of the stay. Some guests also praised the use of local ingredients at breakfast, and the food appeal of an operator that owns Kuroshio Market is strong material for adding to the room rate.
The view as a fixed asset
All-ocean-view rooms and the harbour-view scenery are hard to replicate. In reviews, 97% of mentions of the view are positive, which gives a basis for designing price differences by room type.
Hot spring and food packages
Building Kishu Kuroshio Onsen and Kuroshio Market into stay products lets the same room be priced as a “stay experience”. It is a design made possible precisely because the facilities are run as one.
Lifting the off-season months
Monthly rates span a wide range, from the ¥9,000s in June to the ¥15,000s in peak periods. Creating reasons to visit in off-season months through theme-park events and seasonal hot-spring programmes would add headroom to the annual average.
Location assessment — a mainly commercial-zoned man-made island; tsunami inundation projections mostly in the 2–5 m bands
Checking the man-made island against the zoning data in MLIT’s Real Estate Information Library, most of the island is designated a Commercial Zone (floor area ratio 400%), with a Quasi-Industrial Zone (FAR 200%) around the hotel and a Category 1 Residential Zone (FAR 200%) over the block with residential buildings. As the island is mainly commercial-zoned, it is a location with relatively high freedom to reconfigure, extend or remodel lodging, retail and leisure facilities. There is no official land-price (Chika Koji) point on the island, but a commercial site about 3 km to the north near Kimiidera Station (Minami-Maehama, Kimiidera) was valued at ¥115,000 per m² in the 2026 official land prices, up 2.7% year on year.
On disaster risk, we checked the same library’s tsunami inundation projections (set by Wakayama Prefecture) across the zoned area on and around the island. Tallied over 4,901 points at roughly 10 m intervals, the 2 m to under 3 m inundation-depth band accounts for about 52% and the 3 m to under 5 m band for about 41%. These bands assume a maximum-class tsunami, such as one from a Nankai Trough megathrust earthquake, and are typical of waterfront areas facing Wakayama Bay and the Kii Channel. For a waterfront resort, closeness to the sea is the flip side of its view value. Within the same area, by contrast, no point fell inside a flood inundation zone (assumed maximum-scale river flooding). Evacuation planning, the tsunami resistance of buildings and business-continuity preparations should be treated as items within the resort’s operating plan.
Development scenarios — moving the 99 rooms’ rate up to the resort band lifts room revenue by up to 1.6x
From here we estimate how annual room revenue for the 99 rooms would change if the hotel’s rate moved up to the prefecture’s resort band. This does not estimate the target company’s results; it is a sensitivity analysis combining room count, estimated settled ADR and occupancy from public statistics. ADR has three levels (A: the hotel’s last-12-month average of ¥12,025; B: the Shirahama Town median of ¥14,825; C: the Shirahama resort-hotel median of ¥18,758), and OCC three levels (50.9%, the 2025 final figure for resort hotels in Wakayama Prefecture; 56.9%, the same figure for resort hotels nationwide; and 65.0% as an upper case).
| ADR scenario | OCC 50.9% (Jan–Dec 2025, Wakayama Prefecture resorts) | OCC 56.9% (Jan–Dec 2025, resorts nationwide) | OCC (assumption) 65.0% (upper case) |
|---|---|---|---|
| A. ¥12,025 (current level) | ¥221M RevPAR ¥6,121 | ¥247M RevPAR ¥6,842 | ¥282M RevPAR ¥7,816 |
| B. ¥14,825 (Shirahama Town, all) | ¥273M RevPAR ¥7,546 | ¥305M RevPAR ¥8,435 | ¥348M RevPAR ¥9,636 |
| C. ¥18,758 (Shirahama resort band) | ¥345M RevPAR ¥9,548 | ¥386M RevPAR ¥10,673 | ¥441M RevPAR ¥12,193 |
Keeping occupancy fixed at the Wakayama Prefecture resort-hotel level (50.9%) and moving only the rate up to the Shirahama resort band, annual room revenue rises from ¥221M to ¥345M, an increase of about ¥124M (+56%). In the case where rate and occupancy both approach the national resort level at the same time (C × 56.9%), it reaches ¥386M, about 1.7 times the current level. Put as sensitivities, at this scale each ¥1,000 added to ADR is worth about ¥18.4M a year, and each 1-point improvement in OCC about ¥4.3M a year in room revenue (both starting from A × 50.9%). In a mid-sized 99-room property, rate gives more leverage on revenue than occupancy does.
The routes to raising the rate overlap with the use of the attractions discussed above. Packaging that bundles the hot spring, food and theme park; room-type pricing built around the view; and lifting off-season months with event programming are all measures that are hard to pursue with a hotel-only acquisition. In addition, these estimates exclude revenue from the hot spring, market, theme park and marina. A rise in room rates goes hand in hand with growth in spending across the whole island stay, and the value of an all-in-one acquisition extends beyond room revenue.
⚠ Note on estimates: The estimated settled ADR in this article uses only monthly values for settled months (September 2025 to August 2026), and does not use listed prices for future dates after the survey date. Estimated settled ADR is an estimate (median error of about 7% against REIT-disclosed results) and differs from each property’s actual settled prices. The occupancy rates used in the scenarios are prefecture and national averages from public statistics, not the property’s actual figures.
Summary — buying the machinery means buying the rate headroom
Kasumigaseki Capital’s acquisition of Wakayama Marina City takes over, in a single company, a 99-room hotel plus a set of visitor attractions: a hot spring, a market, a theme park and a marina. Marina City Hotel’s estimated settled ADR averaged about ¥12,000 over the last 12 months, 65% above the Wakayama City median of about ¥7,300, already placing it in the resort price band within the city. Within 5 km it is the only 100-room-class resort; the surrounding market splits into corporate-demand business hotels and the small ryokan of Wakaura.
The gap to the Shirahama resort-hotel median of about ¥18,800 is about ¥6,700, and even with occupancy left at the prefecture average, simply moving the rate up would add about ¥120M a year in room revenue. Guests’ high ratings for the view, hot spring and food show that the material to close that gap is already on the island. On location, it is a mainly commercial-zoned man-made island, and its tsunami inundation projections fall mostly in the 2–5 m bands common to waterfront areas. The new owner has not yet set out its turnaround plan, but an operating structure that can design lodging and visitor attractions as one arguably holds greater rate potential than the turnaround of a stand-alone hotel.
Frequently Asked Questions
Q. How did Kasumigaseki Capital acquire Wakayama Marina City?
A. According to the announcement on August 21, 2026, it acquired all shares of the operating company, Wakayama Marina City Co., Ltd., through its consolidated subsidiary fav hospitality group. The acquisition price has not been disclosed.
Q. Which facilities are included in the acquisition?
A. The facilities the target company runs as one: Wakayama Marina City Hotel (all ocean view), Kuroshio Market, Kishu Kuroshio Onsen, the yacht club and the theme park Porto Europa. The hotel has 99 rooms according to the MetroEngines Research property master.
Q. What level are Wakayama Marina City Hotel’s room rates?
A. Its estimated settled ADR (tax-excluded equivalent) for September 2025 to August 2026 averaged ¥12,025, about 1.65 times the Wakayama City median of ¥7,274 and about 0.64 times the Shirahama Town resort-hotel median of ¥18,758.
Q. How much would room revenue change if the rate moved up to the Shirahama resort band?
A. For 99 rooms, with occupancy fixed at 50.9%, the annual (January–December 2025, final) figure for resort hotels in Wakayama Prefecture, annual room revenue rises from about ¥221M to about ¥345M, an increase of about ¥124M. Each ¥1,000 added to ADR is worth about ¥18.4M a year.
Q. What are the tsunami inundation projections for Marina City?
A. Checking the zoned area on the island against the tsunami inundation projections (set by Wakayama Prefecture) in MLIT’s Real Estate Information Library, about 52% falls in the 2 m to under 3 m inundation-depth band and about 41% in the 3 m to under 5 m band, bands common to waterfront areas under a maximum-class tsunami scenario.
References and Sources
■ Data sources
Municipal estimated settled ADR is the 12-month average of monthly values (property medians) from September 2025 to August 2026. Properties covered: Wakayama City 42–45, Shirahama Town 54–59 (of which resort hotels 19–22), Tanabe City 28–30, Nachikatsuura Town 15. The hotel figure is the simple average of its monthly estimates over the same period. Supply within 5 km is properties open and not yet closed at the end of each year in our property master; positioning uses the 10 properties with estimated settled ADR available in all of the last 12 months. Reviews: 835 from the last 24 months (compiled by the HotelBank Editorial Team, NLP analysis).
■ Scenario assumptions
Annual room revenue = 99 rooms × ADR × OCC × 365 days. ADR: A ¥12,025 (the hotel’s 12-month average), B ¥14,825 (Shirahama Town median), C ¥18,758 (Shirahama resort-hotel median). OCC: 50.9% for resort hotels in Wakayama Prefecture and 56.9% for resort hotels nationwide, from the 2025 final figures of the Japan Tourism Agency’s Overnight Travel Statistics Survey, plus an upper case of 65.0%. All figures are tax-excluded room revenue only and exclude food and beverage, hot-spring and theme-park revenue, costs and the acquisition price.
■ Limitations
Estimated settled ADR is an estimate (median error of about 7% against REIT-disclosed properties), and in segments with few properties, differences in composition tend to show up as rate differences. The scenarios are not an estimate of the target company’s results. Tsunami inundation projections are bands assuming a maximum-class event and do not indicate damage to or the safety of individual buildings.
■ Market data
- MetroEngines Research & Consulting — municipal and property-level estimated settled ADR (Sep 2025–Aug 2026), property master (room counts, locations, opening years)
■ Government statistics and public data
- Japan Tourism Agency, Overnight Travel Statistics Survey, 2025 final figures (Table 8, room occupancy rate) (in Japanese)
- MLIT Real Estate Information Library — zoning, tsunami inundation projections, flood inundation zones, official land prices (in Japanese)
- Wakayama Prefecture, “World Resort Expo” (in Japanese)
■ Company disclosures and official information
- Kasumigaseki Capital Co., Ltd., “Notice concerning the acquisition of shares of Wakayama Marina City Co., Ltd.” (August 21, 2026) (in Japanese)
- Wakayama Marina City official website, “About Marina City” (in Japanese)
■ News and media
- Travel Voice, “Kasumigaseki Capital acquires all shares of Wakayama Marina City, moves into running a mixed-use resort including a theme park” (August 21, 2026) (in Japanese)
- Strike, “Kasumigaseki Capital makes Wakayama Marina City, operator of a theme park and hotel business, a subsidiary” (August 21, 2026) (in Japanese)