

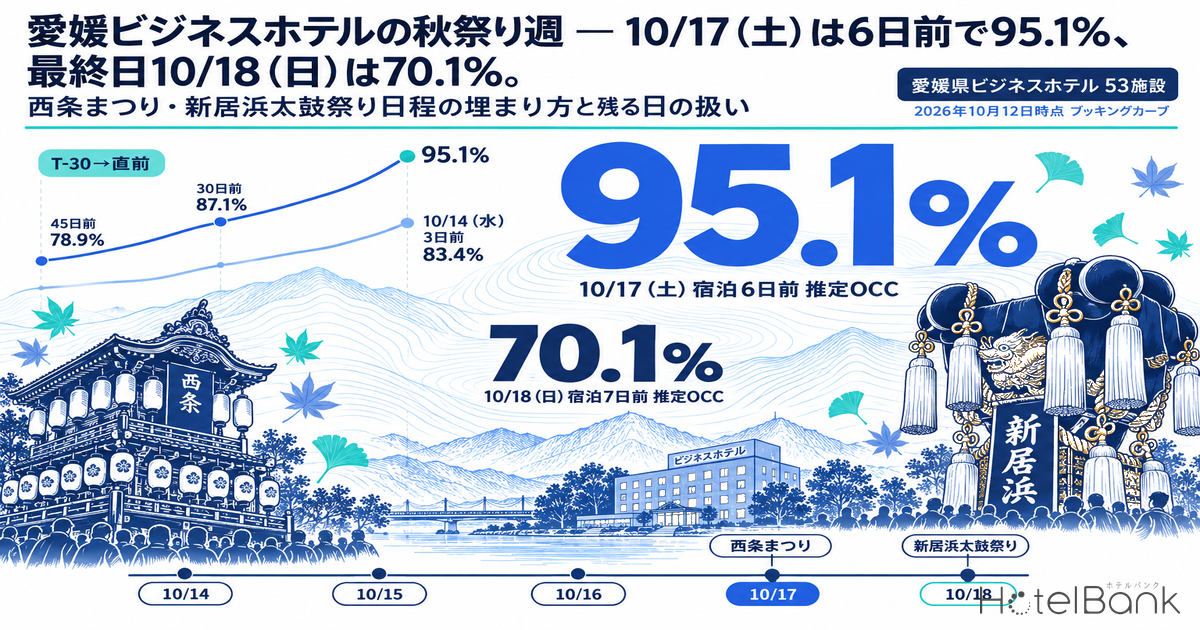
Across 53 business hotels in Ehime Prefecture (5,789 rooms, based on listings on major booking sites), we checked booking pace for mid-October — when the Saijo Festival (西条まつり, October 14–17) and the Niihama Taiko Festival (新居浜太鼓祭り, October 15–18) overlap — using booking curves as of October 12, 2026. Saturday, October 17 had reached an estimated OCC (OTA-listed-inventory basis) of 95.1% six days before the stay date, up 16.2 points from 78.9% at 45 days out. By contrast, Sunday, October 18, the final day of the festivals, stood at only 70.1% at seven days out, and Wednesday, October 14, the opening day, was at 83.4% at three days out — rising late, exactly as the day-of-week pattern would suggest. This article lines up the curves for the five festival days and for a comparison date, Saturday, October 24, reads the shape of the pace — “weekends fill first, weekdays and the final day remain” — and sets out how to handle the days that remain from T-30 through the last few days before arrival.
Scope: business hotels in Ehime Prefecture, N=53 properties (5,789 rooms, based on listings on major booking sites; for October 24, N=52 properties and 5,779 rooms). The price metric in this article is estimated settled ADR (the settled price level estimated from OTA and other sales data, tax-exclusive equivalent), and occupancy is an estimate based on OTA-listed inventory. Both are defined at the end of the article. Data as of October 12, 2026.
- — Saturday, October 17 was at an estimated OCC of 95.1% six days out (78.9% at 45 days out → 87.1% at 30 days out). The weekend’s shape was largely set by its level at 30 days out, and the gain after that was limited to +8.0pt (Ehime business hotels, N=53 properties, 5,789 rooms).
- — Weekdays rise late. Wednesday, October 14 went from 58.0% at 30 days out to 83.4% at three days out (+25.4pt), and Thursday, October 15 from 68.1% to 85.1% at four days out (+17.0pt) — in line with the day-of-week pattern.
- — The final day, Sunday, October 18, was at 70.1% seven days out. That is within range of the average Sunday final level of 72.3% (August–September 2026); it is better designed as “a Sunday” — with extended stays from October 17 — than as a festival finale.
Festival Schedule and Scope — A Week of Five Straight Autumn Festival Days in Eastern Ehime
First, the schedule. According to Saijo City’s official guide (updated October 2, 2026), the Saijo Festival begins with Kamo Shrine (嘉母神社, October 10–11), followed by Iwaoka Shrine (石岡神社) on October 14–15, Isono Shrine (伊曽乃神社) on October 15–16 and Iizumi Shrine (飯積神社) on October 16–17; the dates for the Iwaoka, Isono and Iizumi shrines are fixed every year. Niihama City’s official page (updated September 29, 2026) publishes the 2026 (Reiwa 8) parade schedule of the Niihama Taiko Festival for four days — October 15, 16, 17 and 18. For the five days from Wednesday, October 14 through Sunday, October 18, festival floats and taiko-dai drum floats are therefore on the move somewhere in Toyo (eastern Ehime) every day.
That said, the data in this article aggregates business hotels across all of Ehime Prefecture, including properties in Matsuyama City. Whether the festivals are the direct cause cannot be established from a prefecture-level aggregate; what we read here is strictly the shape of the pace — “within the festival dates, which days are filling and which remain.” Note also that over the three-day weekend just before (October 10–12; the 12th was Sports Day), Saturday, October 10 had built to 97.6% one day out and Sunday, October 11 to 91.8%. Autumn weekend demand is strong in its own right, and that should be kept in mind as the backdrop.
Daily Booking Curves — Sat Oct 17 at 95.1% Six Days Out, Sun Oct 18 at 70.1% Seven Days Out
The chart below overlays estimated OCC for the five festival days and the comparison date, Saturday, October 24, from 45 days before the stay date to the latest observation. The days already differed in height at 45 days out: Saturday the 17th at 78.9%, Friday the 16th at 70.2%, Thursday the 15th at 60.0%, Sunday the 18th at 54.9% and Wednesday the 14th at 53.2% — the closer to the weekend, the higher the starting point.
Source: MetroEngines Research; compiled by the HotelBank Editorial Team
Looking at the build-up to 30 days out, Saturday the 17th gained +8.2pt (78.9% → 87.1%), Friday the 16th and Thursday the 15th both gained +8.1pt, Wednesday the 14th gained +4.8pt and Sunday the 18th gained +3.6pt — the three days nearest the weekend moved first. At 30 days out, Saturday the 17th had already reached 87.1%, which can be read as only 12.9% of inventory being left at that point.
From 30 days out to the latest observation, the order reverses. Wednesday the 14th rose from 58.0% to 83.4% at three days out (+25.4pt) and Thursday the 15th from 68.1% to 85.1% at four days out (+17.0pt) — the weekdays gained sharply — while Saturday the 17th rose from 87.1% to 95.1% at six days out (+8.0pt) and Friday the 16th from 78.3% to 87.5% at five days out (+9.2pt), a slower gain for the days that filled first. It is the natural consequence of less inventory left meaning less room to grow, but over the whole span from 45 days out to the latest observation, the weekdays — +30.2pt for the 14th and +25.1pt for the 15th — outpaced the 17th (+16.2pt) and the 16th (+17.3pt).
| Stay date | Festival schedule | 45 days out | 30 days out | Latest observation | 45 days out → latest |
|---|---|---|---|---|---|
| Oct 13 (Tue) | — | 49.5% | 54.7% | 79.6% 2 days out | +30.1pt |
| Oct 14 (Wed) | Saijo Festival: Iwaoka Shrine (opening day) | 53.2% | 58.0% | 83.4% 3 days out | +30.2pt |
| Oct 15 (Thu) | Saijo Festival: Iwaoka, Isono / Niihama Taiko Festival: opening day | 60.0% | 68.1% | 85.1% 4 days out | +25.1pt |
| Oct 16 (Fri) | Saijo Festival: Isono, Iizumi / Niihama Taiko Festival | 70.2% | 78.3% | 87.5% 5 days out | +17.3pt |
| Oct 17 (Sat) | Saijo Festival: Iizumi Shrine (final day) / Niihama Taiko Festival | 78.9% | 87.1% | 95.1% 6 days out | +16.2pt |
| Oct 18 (Sun) | Niihama Taiko Festival: final day | 54.9% | 58.5% | 70.1% 7 days out | +15.2pt |
| Oct 24 (Sat) | Comparison date (Saturday of the following week) | 84.4% | 87.2% | 92.7% 13 days out | +8.3pt |
Source: MetroEngines Research; compiled by the HotelBank Editorial Team
The remaining question is Sunday the 18th. At 54.9% at 45 days out, 58.5% at 30 days out and 70.1% at seven days out, it is the only one of the five days still in the 70% range, and its gain to the latest observation, +15.2pt, is also the smallest. It is the final day of the Niihama Taiko Festival, but a Sunday-night stay leads into Monday, so it is not a day that weekend demand flows into naturally. The comparison date, Saturday, October 24, started high at 84.4% at 45 days out and had reached 92.7% at 13 days out (N=52 properties, 5,779 rooms). The fact that the Saturday after the festivals is filling at the same level as the festival-week Saturday indicates that “strong weekends, with Sundays and weekdays left over” is the basic shape for the prefecture’s business hotels this autumn, festivals or not. Our look back from T-45 and T-30 at the same prefecture’s five-day holiday in September, Ehime Silver Week: Sep 21 Ryokan 99.9%, Business 91.9%, Sep 23 Flat, likewise found the final day, September 23, staying at the level of an ordinary Wednesday; the last day of a holiday or festival reverting to its day-of-week pattern is not unique to this week.
Fixed Checkpoints and the Day-of-Week Pattern — Weekdays Rise Late, Sundays Never Fully Fill
Lining up the festival week at three points — 45 days out, 30 days out and the latest observation — shows at a glance which days “filled first” and which “rise late.” The chart below adds, as a reference line, the monthly average of 79.7% for September 2026, which is finalized as elapsed-month actuals (N=49–54 properties, varying by day).
Source: MetroEngines Research; compiled by the HotelBank Editorial Team
To check the day-of-week pattern, the next table averages by day of week the 61 days of August and September 2026, for which elapsed-month actuals are complete. Tuesday at 85.1%, Thursday at 84.1%, Saturday at 83.6% and Wednesday at 83.4% — midweek days and Saturday finish at almost the same height — while Friday at 77.3% and Sunday at 72.3% are low. For Ehime’s business hotels, business-travel weekdays and leisure-driven Saturdays sit at the same level, and Sunday is the weakest. Even on the Saturday side, the build-up after 45 days out differs widely by month, as shown in our comparison of four Saturdays in August and September, Ehime Saturday Booking Curves: Aug +14.7pt, Sep Flat at +1.2pt.
| Day of week | Mon | Tue | Wed | Thu | Fri | Sat | Sun |
|---|---|---|---|---|---|---|---|
| Estimated OCC (average of elapsed-month actuals) | 80.1% | 85.1% | 83.4% | 84.1% | 77.3% | 83.6% | 72.3% |
Source: MetroEngines Research; compiled by the HotelBank Editorial Team
Setting the festival week’s latest observations against this pattern, Wednesday the 14th at 83.4% already matches the average Wednesday final level of 83.4%, and Thursday the 15th at 85.1% is above the Thursday average of 84.1% with four days still to go. Friday the 16th at 87.5% exceeds the Friday average of 77.3% by more than 10pt at five days out; the festival-week Friday is clearly filling differently from a normal Friday. Sunday the 18th at 70.1%, on the other hand, has not yet reached the Sunday average of 72.3% at seven days out, but allowing for the gain over the remaining week, it is at a level from which a typical Sunday finish can be expected. Being the final day of a festival has not made the Sunday unusually strong; the reading at this point is that the day-of-week pattern is simply showing through.
The weekdays of the following week are also informative. Wednesday, October 21 and Thursday, October 22 had both reached 83.3% at 10 and 11 days out respectively — the same level as the 83.4% that Wednesday the 14th reached at three days out, but a week earlier. Weekday demand in late October is off to a stronger start than in the festival week. That the festival-week weekdays look relatively “left over” is less a sign that the festivals are failing to lift weekday demand than a reflection of the prefecture-wide pattern in which weekdays fill at the last minute.
Estimated Settled ADR Levels — October 2025 at ¥5,960, +4.6% YoY; November Is the Autumn High
As a price yardstick, we overlaid by year the estimated settled ADR (tax-exclusive equivalent) of Ehime’s business hotels. In finalized months, October 2025 was ¥5,960 (N=100 properties), +4.6% against ¥5,700 in October 2024, and September 2026 was ¥6,085 (N=101 properties), +3.5% against ¥5,880 in September 2025 — both above the same month a year earlier. Within autumn, November is high: November 2025 was ¥6,279 (N=100 properties), +11.1% from ¥5,652 in November 2024, on a par with January (¥6,292 in January 2026), the highest level of the year. As the chart below shows, Ehime’s business hotels have stayed above the same month of the prior year in every finalized month of 2026 so far.
Source: MetroEngines Research; compiled by the HotelBank Editorial Team
| Month | Estimated settled ADR | N= | Basis | Same month a year earlier (finalized) | YoY |
|---|---|---|---|---|---|
| Sep 2025 | ¥5,880 | 101 | Finalized | ¥5,568 | +5.6% |
| Oct 2025 | ¥5,960 | 100 | Finalized | ¥5,700 | +4.6% |
| Nov 2025 | ¥6,279 | 100 | Finalized | ¥5,652 | +11.1% |
| Sep 2026 | ¥6,085 | 101 | Finalized | ¥5,880 | +3.5% |
| Oct 2026 | ¥9,206 | 98 | Estimate based on current sales status | ¥5,960 | (to be compared once finalized) |
Source: MetroEngines Research; compiled by the HotelBank Editorial Team
The ¥9,206 for October 2026 (N=98 properties) is an estimate based on the current sales status and will move as sales progress during the month. Because it reflects the mix of inventory still on sale, a simple comparison with last year’s finalized ¥5,960 should wait until the figure is finalized at month-end. The price benchmarks used in this article are the finalized ones: last year’s levels of ¥5,960 for October and ¥6,279 for November, and ¥6,085 for September, the most recent finalized month.
For Revenue Managers Running Business Hotels in Ehime — Implications and Action Plan
Insights from an Operator’s Perspective
1. Check your own festival-week curve in two parts: “the level at 30 days out” and “the late gain.” On the prefecture curve, Saturday the 17th was at 87.1% and Friday the 16th at 78.3% at 30 days out; for the weekend, the outcome was decided by the level at that point. If your own 17th was not in the 80% range at 30 days out, the late gain alone (+8.0pt for the prefecture) is unlikely to close the gap, and you are at the stage of tilting the remaining inventory toward rate. Conversely, the weekdays of the 14th and 15th rose +17 to +25pt in the final three to four days from 58.0% and 68.1% at 30 days out, so weekday pace that looks slow is no reason to rush into cutting prices.
2. Treat Sunday the 18th as “a Sunday,” not as “the festival finale.” The prefecture’s latest 70.1% (seven days out) is almost the same level as the average Sunday final level of 72.3%, and there is no sign of the festival lifting the Sunday. Sunday weakness is structural for Ehime’s business hotels; rather than setting a special rate in the festival’s name, it makes more sense to design for extended stays from the 17th and for business travelers checking in on Sunday and out on Monday.
3. Anchor the price yardstick to last year’s finalized values. Last year’s finalized ¥5,960 for October and ¥6,279 for November, together with the most recent finalized ¥6,085 for September, are the prefecture’s baseline. In 2025, November came in above October (¥5,960 → ¥6,279), whereas in 2024 the two were almost flat at ¥5,700 for October and ¥5,652 for November. Festival-week pricing belongs at the October level, and there is room to bring forward the rate-revision calendar for November, after the festivals are over.
4. What the Saturday after the festivals (October 24) tells us. From 84.4% at 45 days out to 92.7% at 13 days out, autumn Saturdays are filling early with or without a festival. Rather than singling out the festival week’s Saturday inventory, the realistic approach is to treat all October Saturdays alike as “days to tighten the remaining inventory and capture rate.”
Action Plan
| Timeline | Action | Decision trigger (figures in this article) | Aim |
|---|---|---|---|
| Today–Oct 13 (for Oct 14–15) | Keep the weekday inventory for the festival’s first and second days open to catch last-minute demand, and relax minimum-stay and prepayment conditions | Your pace for Oct 14 and Oct 15 is short of the prefecture’s latest observations (83.4% and 85.1%) | Do not miss the demand that arrives late, as the day-of-week pattern implies |
| Today–Oct 13 (for Oct 17) | Shift remaining inventory toward higher room categories and consecutive nights (Oct 16–17), and stop discounting single rooms | Your Oct 17 has filled to a level close to the prefecture’s latest 95.1% | Allocate near-sell-out inventory to higher-rate demand |
| Oct 14–16 (for Oct 18) | For the final day, Oct 18, encourage extended stays from Oct 17 with “second-night discount” and “Sunday check-in, Monday check-out” messaging | Your Oct 18 is stuck around the prefecture’s 70.1% (seven days out) and the gap with Oct 17 is 20pt or more | Channel weekend demand into the final day |
| Oct 14–16 (for Oct 18) | Rather than filling Oct 18 by cutting rates, estimate where it will finish against the day-of-week pattern, i.e. the Sunday average of 72.3% | The gain on Oct 18 over its final three days falls short of the late build-up Oct 14 showed (58.0% at 30 days out → 83.4% at three days out) | Separate structural Sunday weakness from the festival finale when making the call |
| From Oct 19 (for Oct 24) | For Oct 24, which started high at 84.4% at 45 days out, tighten the remaining inventory and protect rate | Your Oct 24 is level with the prefecture’s latest 92.7% (13 days out) | Go after rate on Saturdays that fill early |
| Looking to next month (November) | Set the festival week’s daily build-up (around +16pt on the weekend, +25 to +30pt on weekdays) beside your own records and use it as the basis for the November rate-revision calendar | Your finalized ADR is still below the prefecture’s finalized ¥6,279 for November 2025 (N=100) heading into the autumn peak | Get revisions in place in time for the autumn month when rates rise most easily |
* The decision triggers in each row are based on the prefecture-level aggregates in this article; the appropriate level varies with your property’s size, location and channel mix.
Summary — Three Yardsticks for Reading the Festival Week
The first is the level at 30 days out. With Saturday the 17th at 87.1% and Friday the 16th at 78.3%, the weekend’s shape was largely set by 30 days out, and the gain after that was limited to +8 to +9pt. The second is the size of the late gain. Wednesday the 14th rose +25.4pt from 58.0% at 30 days out to 83.4% at three days out, and Thursday the 15th +17.0pt; weekday pace moves all at once in the final three to four days. The third is the gap against the day-of-week pattern. Friday the 16th at 87.5% is 10pt above the Friday average of 77.3% at five days out, whereas Sunday the 18th at 70.1% is within range of the Sunday average of 72.3%; the festival finale has not broken out of the day-of-week pattern.
Applying these three points to your own curve organizes the decisions: “how to sell the inventory left on a weekend that has filled,” “whether you can wait on the weekdays that remain,” and “whether to treat the final Sunday as a festival day or as a day of the week.” Even in a week that carries festival names, the day-of-week pattern is the backbone of pace for Ehime’s business hotels, and the festivals sit on top of it, lifting Friday and Saturday a little higher — that is the reading as of October 12, 2026.
Frequently Asked Questions
Q. Is estimated OCC the same as actual room occupancy?
A. No. Estimated OCC is an inventory-depletion metric back-calculated from the number of rooms still listed on OTAs and similar channels. Because rooms not listed are counted as sold, it tends to run higher than actual occupancy. It is a metric suited to comparing days and reading the shape of pace.
Q. Is it fair to conclude that the festivals lifted occupancy?
A. Because this is a prefecture-wide aggregate, this article does not assert causation. Friday the 16th is clearly higher than a normal Friday, while Sunday the 18th remains at an average Sunday level; we think the reasonable reading is that the day-of-week pattern is the backbone of pace and the festivals sit on top of it.
Q. Can the estimated settled ADR of ¥9,206 for October 2026 be used as it is?
A. It is an estimate based on the current sales status and will move as sales progress during the month. As price benchmarks, refer to the finalized values of ¥5,960 for October 2025, ¥6,279 for November 2025 and ¥6,085 for September 2026, and we recommend checking the finalized October value again after month-end.
About the Data
• Estimated OCC (OTA-listed-inventory basis): OTA-listed-inventory occupancy = 100 − 100 × rooms still listed on OTAs ÷ total rooms. The scope is a fixed cohort of properties that list 30% or more of their total rooms on OTAs (the same set of properties for each stay date; the number of properties is given as N= in the text). It is an estimate based on the depletion of inventory sold on OTAs, and its definition differs from actual room occupancy (it runs higher because rooms not listed are counted as sold).
• Booking curves: based on observations from 45 days before the stay date to the latest. The fixed checkpoints are 45 days out, 30 days out and the latest observation (2 to 13 days out, depending on the stay date).
• Estimated OCC by day of week: elapsed-month actuals for August and September 2026 (daily, N=48–54 properties), averaged by day of week.
• Estimated settled ADR: the settled price level (tax-exclusive equivalent) estimated from OTA and other sales data (lowest-plan level × coefficient by property type, ensembled across multiple channels). Past months are finalized values; the current and future months are estimates based on the current sales status. Median error of 6.6% when checked against published operating results.
• Scope: business hotels in Ehime Prefecture. Booking curves cover N=53 properties and 5,789 rooms (for October 24, N=52 properties and 5,779 rooms; based on listings on major booking sites). Estimated settled ADR covers N=94–103 properties depending on the month.
• Data as of: October 12, 2026 (the latest booking-curve observation date is October 11). Sales status and inventory change daily, so the figures in this article are a snapshot at the time of retrieval.
References and Sources
• Saijo City, “Guide to the Saijo Festival” (updated October 2, 2026): https://www.city.saijo.ehime.jp/site/kanko/maturi.html
• Niihama City, “Niihama Taiko Festival” (updated September 29, 2026; 2026 parade schedule): https://www.city.niihama.lg.jp/soshiki/kankou/taikomatsuri.html