


Within the scope tracked by MetroEngines Research, 56 accommodation facilities with 3,406 rooms opened in Osaka Prefecture in 2026 (including one hotel scheduled to open in December). Of these, 16 facilities with 1,689 rooms were “rebrands” that reopened existing buildings after renovation or renaming, while 40 facilities with 1,717 rooms were new builds or new conversions, splitting the room count almost exactly in half. This article breaks down the openings by type, size and location, overlays the sites where five international brands with 1,101 rooms clustered and the rate levels in October 2026, the year after Expo 2025 Osaka, Kansai, and assesses from an investor and operator perspective how much room the market has to absorb supply from 2027 onward.
• ADR (average daily rate) = an estimated settled rate (tax-excluded equivalent) calculated by applying a segment-specific adjustment factor to each property’s lowest published OTA plan (per room, double occupancy, tax included). Benchmarked against property-level actuals disclosed by listed hotel REITs (91 properties, most recent three months), the median error is about 7%. These are estimates and differ from each property’s actual settled rates and accounting figures.
• ADR at the area level (prefecture, city or ward) is the median of the estimated settled rates of the properties covered (the level of a typical property in the area).
• Where published prices are cited, they are per-room rates for double occupancy (tax included).
• OCC (occupancy) = rooms sold as a share of total rooms in the area (an estimate based on OTA sales inventory).
• Source: MetroEngines Research (continuously tracks published OTA prices for approx. 168,000 properties in Japan, of which approx. 27,000 are confirmed active)
Room stock in this article covers accommodation facilities with 10 or more rooms (excluding leisure/love hotels) within a 1,000m radius of THE GATE HOTEL Osaka by HULIC; “active” means a sales price was confirmed on major booking sites in the last three months (September to November 2026) (as of November 11, 2026, compiled by MetroEngines Research). (This article aggregates 1,000m-radius circles around five sites under the same conditions.) LT (lead time) = days until check-in.
- — 56 hotels, 3,406 rooms — new openings in Osaka Prefecture in 2026 (including one scheduled for December). The 11 hotels with 100+ rooms account for 62.5% of rooms
- — Rebrands: 1,689 rooms (49.6%) — all five international-brand hotels (1,101 rooms) are conversions of existing buildings. New builds total 40 facilities and 1,717 rooms
- — 88.8% in three wards — Chuo, Naniwa and Nishinari host 36 facilities and 3,025 rooms. The supply belt runs south from Shinsaibashi to Shin-Imamiya, where land prices at the southern end are about 1/50 of the city center
- — Chuo Ward ADR ¥12,985 (October 2026) — −21.5% vs October of the Expo year, but +11.2% vs pre-Expo October 2024 (estimated settled ADR, N=193 properties)
- — Gap at ¥25,000–40,000 × 100+ rooms — of the 27 properties opened in 2026 with available ADR, 19 are clustered at ¥15,000 or below
Osaka Prefecture’s 2026 Openings: 56 Hotels, 3,406 Rooms — 11 Properties with 100+ Rooms Hold 60% of Supply
Start with the overall picture. Of the 56 openings, hotels (business, city and resort categories) number 33 with 2,986 rooms, or 87.7% of rooms, followed by 9 hostels with 327 rooms and 14 small properties such as vacation rentals and whole-house rentals with 93 rooms. By count, hostels and small properties together exceed 40%, but by rooms the six properties with 200+ rooms alone provide 1,483 rooms, and widening to the 11 properties with 100+ rooms brings the total to 2,130 rooms (62.5%). The supply impact is concentrated in a small number of large projects.
Room counts prioritize each operator’s published figures, and hostels are counted by rooms rather than beds. For example, GRAND HOSTEL LDK Osaka Shinsekai (GRAND HOSTEL LDK大阪新世界), which opened on June 18, is a large hostel with capacity for 252 guests, but it is counted here as 42 rooms. The table below crosses property type with size.
| Type | 200+ rooms | 100–199 rooms | 50–99 rooms | 10–49 rooms | Under 10 rooms | Total |
|---|---|---|---|---|---|---|
| Hotels | 6 / 1,483 rooms | 5 / 647 rooms | 8 / 531 rooms | 11 / 308 rooms | 3 / 17 rooms | 33 / 2,986 rooms |
| Hostels | — | — | 3 / 186 rooms | 3 / 124 rooms | 3 / 17 rooms | 9 / 327 rooms |
| Vacation rentals, whole-house rentals, etc. | — | — | — | 2 / 81 rooms | 12 / 12 rooms | 14 / 93 rooms |
| Total | 6 / 1,483 rooms | 5 / 647 rooms | 11 / 717 rooms | 16 / 513 rooms | 18 / 46 rooms | 56 / 3,406 rooms |
Arranging openings by month reveals two peaks, in spring and summer. In March and April alone, 14 facilities with 1,199 rooms opened, followed by 24 facilities with 1,165 rooms from June to August. The first half (January–June) accounted for 2,194 rooms, or 64.4% of the year, suggesting many projects were prepared for the first spring after the Expo closed.
New Build or Rebrand? Half of New Rooms Are Reopened Existing Buildings, and All Five International Brands Are Conversions
Next, we classify what the supply actually consists of. Checking each property against operator releases and press coverage, and against whether a predecessor of similar size operated at the same address, shows that 16 of the 56 openings with 1,689 rooms were rebrands that reopened existing buildings after renovation or renaming. The remaining 40 facilities with 1,717 rooms are new builds or new conversions (no predecessor identified), and it is these that genuinely expanded the area’s room stock.
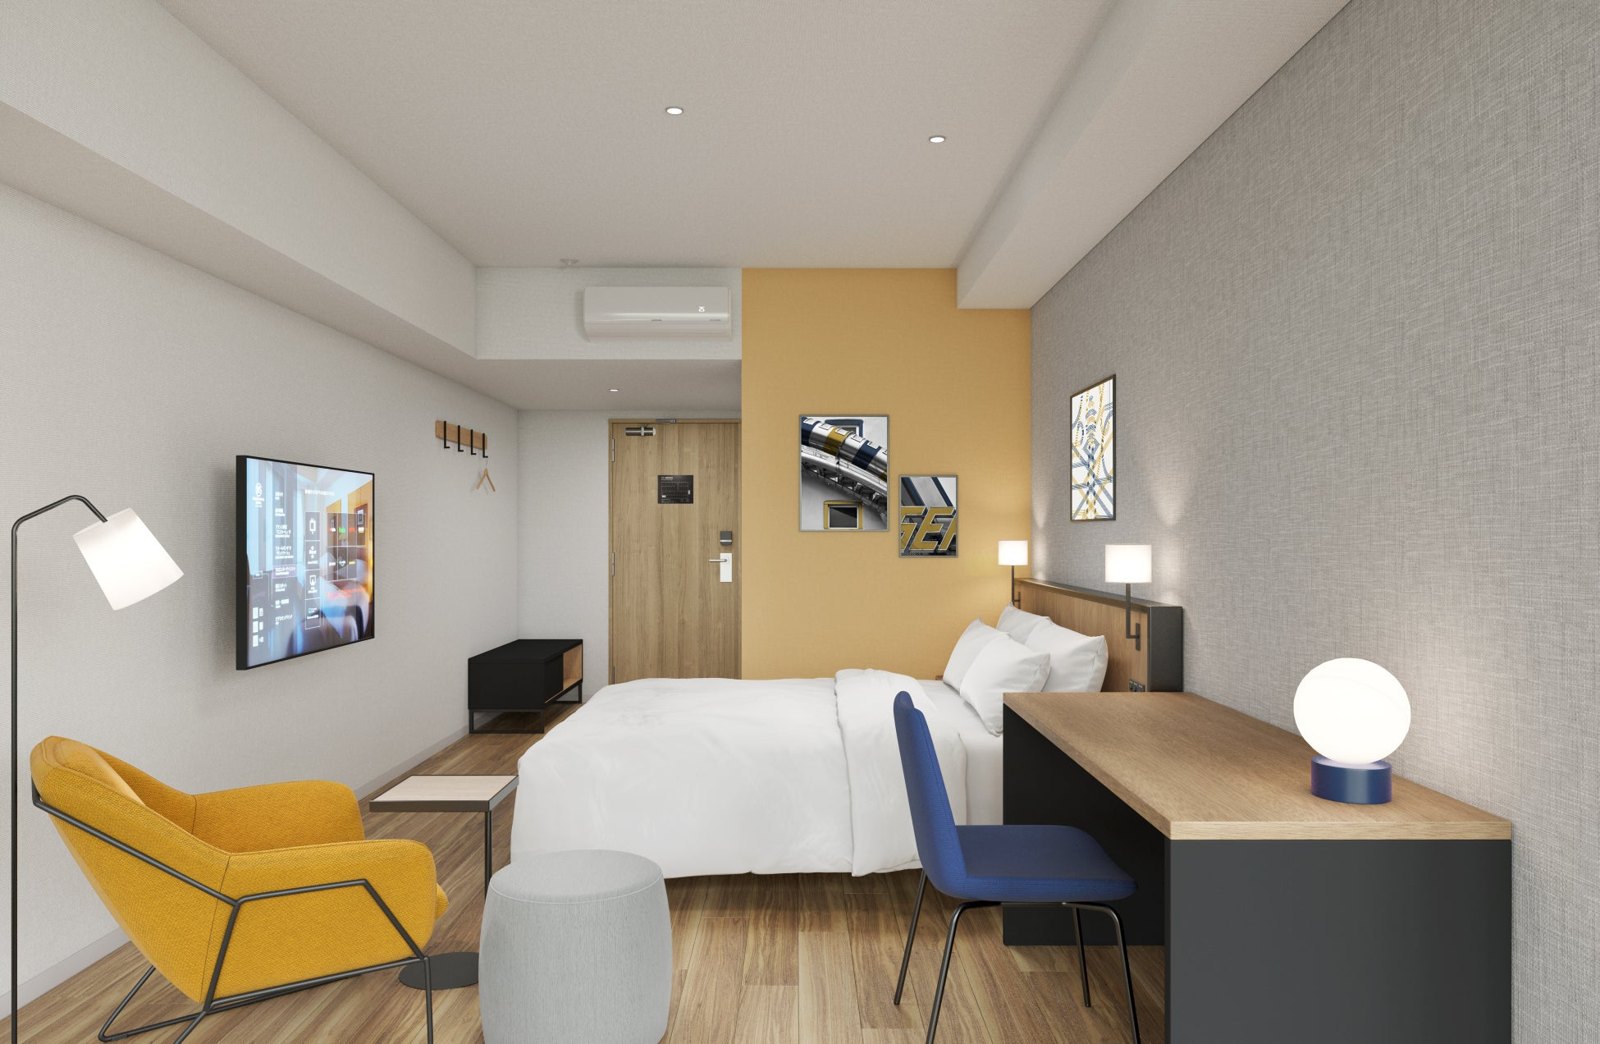
The moves by international brands stand out. Travelodge Osaka Shinsaibashi (トラベロッジ大阪心斎橋, 302 rooms), Centara Life Namba Hotel Osaka (センタラライフなんばホテル大阪, 300 rooms), Sugata Hotel Osaka Shinsaibashi, Series by Marriott (スガタ ホテル 大阪心斎橋 シリーズ by マリオット, 256 rooms), and City Express by Marriott’s Osaka Namba Minami (143 rooms) and Osaka Shin-Imamiya (100 rooms) — five hotels with 1,101 rooms — are all conversions of existing buildings. These five account for 65.2% of the 1,689 rebranded rooms, confirming a pattern in which, amid rising construction costs, foreign operators are choosing to rebrand existing stock rather than build new as their way to enter and expand in Japan. How ownership, operation and brand layers are swapped while the building stays in place is covered in the three-layer structure of a rebrand opening and measured 2026 cases.
| Property | Ward | Rooms | Opening date | Type | Basis / overview |
|---|---|---|---|---|---|
| Travelodge Osaka Shinsaibashi | Chuo | 302 | Aug 1 | Rebrand | Opened after full renovation (company release) |
| Centara Life Namba Hotel Osaka | Naniwa | 300 | Apr 6 | Rebrand | Took over an existing hotel (press reports) |
| Sugata Hotel Osaka Shinsaibashi, Series by Marriott | Chuo | 256 | Mar 31 | Rebrand | First in Japan for the conversion-focused collection brand |
| THE GATE HOTEL Osaka by HULIC | Chuo | 223 | Jun 15 | New build | Floors 16–28 of a building directly connected to Shinsaibashi Station |
| Solaria Nishitetsu Hotel Osaka Honmachi | Chuo | 202 | Dec 18 (scheduled) | New build | 13-story mixed-use building directly connected to Honmachi Station |
| Anchored by Rihga Osaka Namba | Naniwa | 200 | Apr 3 | New build | Developed by Tokyu Land; first property of a new brand |
| Rita Hotel Namba | Nishinari | 159 | March | New conversion | Walking distance from JR Imamiya Station |
| City Express by Marriott Osaka Namba Minami | Nishinari | 143 | May 7 | Rebrand | Rebranded an existing hotel (press reports) |
| Hotel Geometic Osaka Umeda | Kita | 132 | Jul 16 | New conversion | Directly connected to the underground mall; rooms on floors 3–11 |
| Compass Hotel Osaka Honmachi | Chuo | 113 | Oct 1 | Rebrand | Predecessor of similar size at the same address |
| City Express by Marriott Osaka Shin-Imamiya | Nishinari | 100 | May 7 | Rebrand | Rebranded an existing hotel (press reports) |
Limiting the view to the 11 properties with 100+ rooms (2,130 rooms), rebrands account for 6 properties with 1,214 rooms and new builds for 5 properties with 916 rooms. Solaria Nishitetsu Hotel Osaka Honmachi is scheduled to open on December 18 as announced by the Nishitetsu Group, and with its 202 rooms the year’s net additions should be essentially complete. Among the 45 properties with fewer than 100 rooms, by contrast, new builds are the majority at 35 properties with 801 rooms, and rebrands number only 10 with 475 rooms. A two-tier structure — conversions at the large end, new builds at the small and mid-size end — characterizes Osaka’s 2026 supply.
Location: 88.8% in Chuo, Naniwa and Nishinari — the Center of Gravity Shifts South from Shinsaibashi to Shin-Imamiya
So where did the supply land? By municipality, Chuo Ward leads with 14 facilities and 1,488 rooms, followed by Naniwa Ward with 12 facilities and 870 rooms and Nishinari Ward with 10 facilities and 667 rooms. These three wards alone account for 36 facilities and 3,025 rooms, or 88.8% of the prefecture, and widening to the whole of Osaka City brings the total to 51 facilities and 3,360 rooms (98.6%). Kita Ward saw only 2 facilities with 172 rooms: 2026’s new supply went to Minami rather than Kita, concentrated in a roughly 3km north–south belt from Shinsaibashi and Nagahoribashi down to Ebisucho and Shin-Imamiya.
Behind this lies the land price gradient. Taking the nearest commercial benchmark sites to the large projects in the Ministry of Land, Infrastructure, Transport and Tourism’s (MLIT) 2026 official land prices, Shinsaibashi on Midosuji reaches ¥14.1 million per ㎡ and Honmachi ¥10.6 million, while Nagahoribashi is ¥3.14 million, Imamiya-Ebisu ¥796,000, Ebisucho ¥680,000 and Shin-Imamiya ¥282,000 — the level steps down as you move south. Year-on-year changes are all upward at +8.9% to +15.6%, and Imamiya-Ebisu (+15.0%) and Ebisucho (+13.1%) in particular are rising at the same pace as the city center. Land at a fraction — down to a few percent — of central values, combined with remaining contiguous commercial zones with a 600% floor area ratio, appears to make economy-to-midscale projects easier to pencil out.
| Site (representative property) | Zoning / designated FAR | Nearest benchmark site | 2026 official land price (¥/㎡) | YoY |
|---|---|---|---|---|
| Shinsaibashi (THE GATE HOTEL Osaka) | Commercial, 1,000% | Minami-Semba 4-chome | 14,100,000 | +15.6% |
| Honmachi (Solaria Nishitetsu Hotel) | Commercial, 1,000% | Bingomachi 3-chome | 10,600,000 | +15.0% |
| Nagahoribashi (Travelodge / Sugata) | Commercial, 800% | Minami-Semba 2-chome | 3,140,000 | +12.1% |
| Imamiya-Ebisu (Centara Life) | Commercial, 600% | Ebisu-Honmachi 1-chome | 796,000 | +15.0% |
| Ebisucho (Anchored) | Commercial, 600% | Ebisu-Higashi 1-chome | 680,000 | +13.1% |
| Shin-Imamiya (City Express) | Commercial, 600% | Haginochaya 2-chome | 282,000 | +8.9% |
How large, then, is 2026’s new supply relative to existing stock? Looking at 1km-radius circles centered on the five large properties, rooms opened in 2026 (10+ rooms) equal 4.6–5.7% of active rooms in the Shinsaibashi, Nagahoribashi and Honmachi circles, versus 9.1% in the Ebisucho circle and 9.3% in the Imamiya-Ebisu circle — nearly double. Excluding rebrands and counting only new builds, however, the ratios fall to 2.5% in Shinsaibashi, 1.7% in Nagahoribashi, 2.5% in Honmachi, 4.5% in Ebisucho and 5.0% in Imamiya-Ebisu. Net additions are smaller than the headline numbers suggest; even in the south, the realistic picture is an increment of around 5% on existing stock.
| Center (1km radius) | Active properties / rooms | 2026 openings (10+ rooms) | Of which new build | Of which rebrand | Share of active rooms | New build only |
|---|---|---|---|---|---|---|
| Shinsaibashi (THE GATE HOTEL Osaka by HULIC) | 164 / 23,283 rooms | 9 / 1,319 rooms | 573 rooms | 746 rooms | 5.7% | 2.5% |
| Nagahoribashi (Travelodge Osaka Shinsaibashi) | 157 / 22,289 rooms | 9 / 1,197 rooms | 371 rooms | 826 rooms | 5.4% | 1.7% |
| Honmachi (Solaria Nishitetsu Hotel Osaka Honmachi) | 91 / 17,198 rooms | 4 / 794 rooms | 425 rooms | 369 rooms | 4.6% | 2.5% |
| Ebisucho (Anchored by Rihga Osaka Namba) | 113 / 11,610 rooms | 13 / 1,062 rooms | 522 rooms | 540 rooms | 9.1% | 4.5% |
| Imamiya-Ebisu (Centara Life Namba Hotel Osaka) | 120 / 12,679 rooms | 13 / 1,174 rooms | 634 rooms | 540 rooms | 9.3% | 5.0% |
Rates: −21.5% vs the Expo Month, +11.2% vs October 2024
How did rates move in a year of rising supply? Estimated settled ADR in Osaka City’s Chuo Ward was ¥13,000 in October 2026 (N=193 properties). Compared with ¥16,500 the previous October (N=188 properties), that is −21.5% YoY, but October 2025 fell within Expo 2025 Osaka, Kansai (April 13 – October 13, 2025), so this should be read as a “comparison against an Expo month.” Pre-Expo October 2024 was ¥11,700 (N=189 properties), and October 2026 exceeds it by +11.2%. Using 2024, rather than the Expo year, as the baseline is also discussed in detail in Osaka’s settled September estimated ADR.
The annual trend confirms the same picture. Chuo Ward’s January–October average was ¥11,000 in 2024, ¥14,400 in 2025 and ¥11,100 in 2026: 2026 returned to roughly the pre-Expo 2024 trajectory, then pulled ahead from autumn. In other words, 2026 rates landed at a normal post-boom level while absorbing 3,406 new rooms.
| Area | Oct 2024 | Oct 2025 (Expo month) | Oct 2026 | YoY | vs Oct 2024 | Properties (Oct 2026) |
|---|---|---|---|---|---|---|
| Chuo Ward | ¥11,679 | ¥16,534 | ¥12,985 | -21.5% | +11.2% | 193 |
| Naniwa Ward | ¥10,581 | ¥14,518 | ¥12,406 | -14.5% | +17.2% | 57 |
| Nishinari Ward | ¥3,286 | ¥4,049 | ¥5,112 | +26.3% | +55.6% | 33 |
| Kita Ward | ¥10,168 | ¥14,956 | ¥11,575 | -22.6% | +13.8% | 74 |
| Osaka Prefecture total | ¥9,440 | ¥13,392 | ¥10,580 | -21.0% | +12.1% | 661 |
Looking at the wards where openings concentrated, Naniwa Ward was ¥12,400 in October 2026 (N=57 properties), +17.2% vs October 2024, and Kita Ward was ¥11,600 (N=74 properties), +13.8% on the same basis. Nishinari Ward stands out: although its absolute level is low at ¥5,100 (N=33 properties), it is up +26.3% even against the Expo month of the previous October and +55.6% vs October 2024. The entry of international and lifestyle brands is widening the ward’s rate range itself, a sign of the area’s growth potential.
Absorption is also progressing on the supply–demand side. Osaka Prefecture’s occupancy in October 2026 (OTA-listed inventory basis, estimated) was 89.5% (459 properties / 63,152 rooms, based on major booking-site listings), with business hotels at 89.1% (301 properties / 49,245 rooms) and city hotels at 92.3% (41 properties / 9,590 rooms). These are estimates based on how OTA-sold inventory is being taken up and differ from properties’ actual overall occupancy, but they confirm that inventory sell-through remained high in October even with new supply added.
Price Bands of the Five International Brands: Clustered at ¥10,000–14,000, About Twice the Ward Median in Nishinari
| Property | Ward | Rooms | Estimated settled ADR (Oct 2026) | Ward estimated settled ADR (same month) |
|---|---|---|---|---|
| Travelodge Osaka Shinsaibashi | Chuo | 302 | ¥10,278 | ¥12,985 |
| Sugata Hotel Osaka Shinsaibashi, Series by Marriott | Chuo | 256 | ¥10,393 | ¥12,985 |
| Centara Life Namba Hotel Osaka | Naniwa | 300 | ¥14,414 | ¥12,406 |
| City Express by Marriott Osaka Shin-Imamiya | Nishinari | 100 | ¥11,730 | ¥5,112 |
| City Express by Marriott Osaka Namba Minami | Nishinari | 143 | ¥10,430 | ¥5,112 |
The five international-brand hotels’ estimated settled ADR in October 2026 fell within a range of ¥10,300–14,400. The two in Chuo Ward sit in the low ¥10,000s, using their scale of 302 and 256 rooms to thicken the ward’s economy tier. In Naniwa Ward, Centara Life at ¥14,400 is above the ward median of ¥12,400, while the two City Express hotels in Nishinari Ward sell at ¥10,400 and ¥11,700, about twice the ward median of ¥5,100. Even within the same “international conversion” category, these hotels play different roles — volume in the center, the top price tier within the area in the south — an instructive point when thinking about the positioning of rebrand projects.
Positioning: New Supply Clusters at ¥15,000 and Below; ¥25,000–40,000 × 100+ Rooms Is Empty
Bringing this together on two axes, price and size: the chart below plots the 27 properties opened in 2026 with 10+ rooms and an available October 2026 estimated settled ADR, by room count and rate. Of the 27, 19 are clustered at ¥15,000 or below, and only two properties with 100+ rooms exceed ¥20,000: Anchored by Rihga Osaka Namba (¥23,500) and THE GATE HOTEL Osaka by HULIC (¥45,300).
Dense Crowded segment
Up to ¥15,000 × 10–300 rooms
19 of 27 properties. The five international conversions also sit in or near this band, which has become the main battleground for supply.
WS1 Upper-midscale, mid-to-large
¥25,000–40,000 × 100–300 rooms
No 2026 openings. There is room for extended-stay concepts with large public baths or lounges.
WS2 High-end, large
Over ¥40,000 × 150+ rooms
Only one property, directly connected to Shinsaibashi Station. Sites combining a direct station connection and high-floor rooms are limited and scarce.
Two white spaces emerge. One is the upper-midscale band of ¥25,000–40,000 × 100–300 rooms, with no 2026 openings. The other is large properties above ¥40,000, where a single property directly connected to Shinsaibashi Station stands alone. Because most new supply went to economy-to-midscale, competition in the price tiers above has not increased in relative terms — which can also be read as an environment in which owners of existing full-service and upper-midscale hotels continue to find it easier to hold or grow rates.
Pipeline from 2027: 220 Rooms in Dojimahama in February, 817 Rooms Next to USJ in 2029
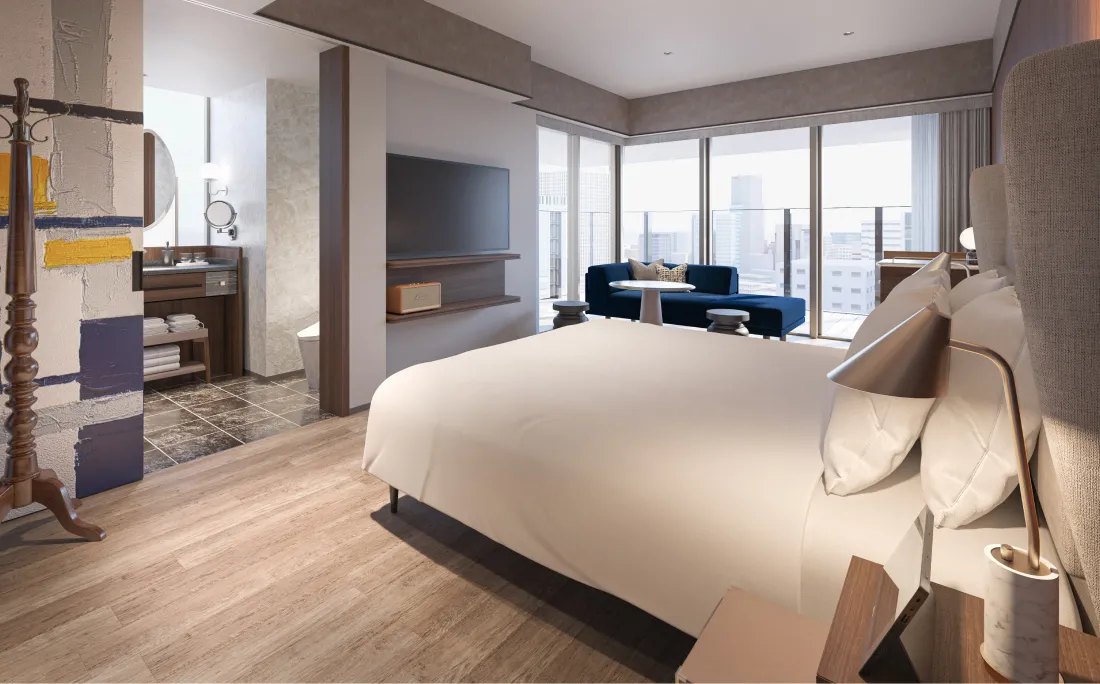
Finally, the future pipeline. Drawing 100+ room projects in Osaka Prefecture from MLIT’s Building Starts Statistics (building-permit basis), two projects with 337 rooms are scheduled for completion or opening in 2027 or later. A 220-room hotel in a supertall mixed-use tower in Dojimahama, Kita Ward, has been announced by the Mitsui Fudosan group as Mitsui Garden Hotel Osaka Dojimahama Premier (三井ガーデンホテル大阪堂島浜プレミア), opening February 26, 2027. In Honmachi 1-chome, Chuo Ward, a new 117-room, 13-story project is progressing toward completion in August 2028 (for how this project fits within its 1km radius, see our evaluation of the Osaka Honmachi hotel plan for 2028).
| Location | Rooms | Timing (as stated in source) | Overview |
|---|---|---|---|
| Dojimahama 2-chome, Kita Ward, Osaka City | 220 | Opening Feb 26, 2027 | Floors 25–31 of a supertall mixed-use tower; Mitsui Garden Hotel Osaka Dojimahama Premier |
| Honmachi 1-chome, Chuo Ward, Osaka City | 117 | Completion Aug 2028 | New 13-story hotel project |
| Osaka City (next to USJ) | 817 | Opening 2029 | Three-brand complex by IHG Hotels & Resorts (company announcement / press reports) |
In addition, IHG Hotels & Resorts has announced plans to open a three-brand, 817-room hotel complex next to Universal Studios Japan in 2029. Building permit applications, however, are usually filed one to two years before opening, so the count for 2028 and beyond will rise as new applications come in. The current figures do not mean “few plans”; they should be treated as the lower bound of the confirmed pipeline. Given that half of the 3,406 rooms observed in 2026 were rebrands, it is reasonable to expect a steady flow of rebrand-type supply that rarely shows up in the statistics to continue from 2027.
Investment Implications: Conversion Exits, Southern Land Prices and the Empty Price Band
Based on the above, we offer three perspectives for investors, operators and lenders searching for land or existing assets in Kansai. First, converting existing hotels has become a strong option. In 2026 there were six rebrands of 100+ rooms totaling 1,214 rooms, five of them international brands. They show that even aging 250–300-room properties can be brought back to market by pairing them with an international brand’s distribution network, making them reference cases when considering exit strategies for owned assets or operator changes.
Second, the location potential of southern Minami. Ebisucho, Imamiya-Ebisu and Shin-Imamiya have land prices at a fraction of the center or less, yet official land prices rose +8.9% to +15.0% YoY, and Nishinari Ward’s estimated settled ADR has grown +55.6% vs October 2024. Although the new-build share within the 1km radius is higher than on the central side at 4.5–5.0%, land and assets acquired early tend to be revalued when a ward’s rate range is widening. The transit-hub character, where Nankai, JR and subway lines intersect, also supports medium- to long-term valuations.
Third, the gap in price bands. 2026’s new supply is heavy at ¥15,000 and below, with nothing at ¥25,000–40,000 × 100+ rooms. Given a rate level just over 10% above pre-Expo October 2024 and prefecture-wide inventory sell-through of 89.5% in October 2026 (OTA-listed inventory basis, estimated, as above), upper-midscale extended-stay concepts merit consideration as a segment with ample room for differentiation. Note that this analysis is a market overview based on public data, and individual projects require a detailed feasibility study.
Sensitivity of the Empty Price Band: The Range of Room Revenue by ADR × Occupancy
To put numbers to the third perspective, we estimated room revenue for entering the empty ¥25,000–40,000 band at 100–300 rooms, across combinations of ADR and occupancy. The base case (¥30,000, 80%) yields RevPAR of ¥24,000, versus ¥18,750 in the downside case (¥25,000, 75%) and ¥29,750 in the upside case (¥35,000, 85%). If ADR falls below the band’s floor to ¥20,000, RevPAR stays at ¥18,000 even at 90% occupancy (full-year assumption), below the downside case. The viability of this band depends more on holding rates than on occupancy.
| Scenario | Estimated settled ADR | Occupancy (full-year assumption) | RevPAR | Annual room revenue per room | 150-room equivalent |
|---|---|---|---|---|---|
| Downside | ¥25,000 | 75% | ¥18,750 | ¥6.84M | ¥1.03B |
| Base | ¥30,000 | 80% | ¥24,000 | ¥8.76M | ¥1.31B |
| Upside | ¥35,000 | 85% | ¥29,750 | ¥10.86M | ¥1.63B |
| Estimated settled ADR \ Occupancy | 70% | 75% | 80% | 85% | 90% |
|---|---|---|---|---|---|
| ¥20,000 (below band floor) | ¥14,000 | ¥15,000 | ¥16,000 | ¥17,000 | ¥18,000 |
| ¥25,000 | ¥17,500 | ¥18,750 | ¥20,000 | ¥21,250 | ¥22,500 |
| ¥30,000 | ¥21,000 | ¥22,500 | ¥24,000 | ¥25,500 | ¥27,000 |
| ¥35,000 | ¥24,500 | ¥26,250 | ¥28,000 | ¥29,750 | ¥31,500 |
| ¥40,000 | ¥28,000 | ¥30,000 | ¥32,000 | ¥34,000 | ¥36,000 |
Estimate: HotelBank Editorial Team (RevPAR = estimated settled ADR × occupancy; annual room revenue = RevPAR × 365 days). The ADR band is the white space on this article’s positioning map (¥25,000–40,000 × 100–300 rooms); the base case assumes the band midpoint of ¥30,000 and 80% occupancy (full-year assumption). These are assumptions, not plans or forecasts for any specific property. The prefecture-wide 89.5% for October 2026 is a single-month estimate on an OTA-listed inventory basis, so it is not used as a full-year assumption; a range of 70–90% is shown instead. F&B and ancillary revenue, operating costs, rent, NOI and yields are not included.
Summary
Osaka Prefecture’s 2026 new openings totaled 56 facilities and 3,406 rooms; 1,689 rooms, or 49.6%, were rebrands of existing buildings, and new builds accounted for 1,717 rooms. Supply concentrated 88.8% in three wards — Chuo, Naniwa and Nishinari — and all five international-brand hotels (1,101 rooms) are conversions lined up along the belt from Shinsaibashi to Shin-Imamiya. Chuo Ward’s estimated settled ADR was −21.5% against the previous October, an Expo month, but +11.2% vs pre-Expo October 2024, absorbing new supply while returning to a normal level. Confirmed plans from 2027 are limited for now, but because rebrand-type supply appears before it shows up in the statistics, the survey-date figures should be treated as a lower bound and monitored on an ongoing basis.
Related Articles
- Osaka Hotel Investment Map 2026: ADR by Ward, 55% in Chuo & Kita
- New Hotel Openings in Japan 2026 by City: 1,433 Hotels, 36,986 Rooms
- Japan-Debut Hotel Brands 2026: 5 Brands, 6 Hotels, 857 Rooms
- Naniwasuji & Haneda Access Lines 2031: Hotel Investment Timelines
- Centara’s 2 Osaka Hotels, 815 Rooms: Namba Supply, ADR Down 34.7%
- Osaka Honmachi Hotel 2028: 117 Rooms vs 17,600 in 1km, ¥10,600 ADR
- What Is a Hotel Rebrand Opening? 3 Layers and 3 Measured 2026 Cases
- Osaka Sep 2026 Settled ADR: Business −34.0%, City −21.8% vs Expo Year
References and Sources
■ Data sources
New openings are facilities in Osaka Prefecture opened in 2026 whose OTA listings were confirmed by MetroEngines Research (N=56, including one scheduled to open in December). Room counts prioritize operators’ published figures, and hostels are counted by rooms rather than beds. Estimated settled ADR is the median of covered properties by municipality (tax-excluded equivalent); room stock within 1km covers properties with sales prices confirmed in the last three months; land prices and zoning are from the MLIT Real Estate Information Library; and the future pipeline is from Building Starts Statistics (building-permit basis) and company announcements.
■ Estimation assumptions
Rebrands were identified property by property based on whether a predecessor of similar size existed at the same location (within about 45m) and on operator releases and press reports. The 1km-radius ratio is 2026 openings (10+ rooms) ÷ active rooms. The sensitivity of the empty price band is simple arithmetic — RevPAR = estimated settled ADR × occupancy, annual room revenue = RevPAR × 365 days — and ADR and occupancy are assumptions.
■ Limitations
Because opening data is based on confirmed OTA listings, facilities not yet listed (particularly November–December openings) may increase. Estimated settled ADR and occupancy are estimates from public OTA information and differ from each property’s actual settled rates and actual occupancy. The pipeline from 2027 is a lower bound on a building-permit basis, and rebrand-type supply rarely shows up in the statistics. The sensitivity estimate is intended as a market overview and does not represent a business plan or investment decision for any specific property.
■ Market data
| MetroEngines Research & Consulting — new opening data (based on confirmed OTA listings, N=56 properties), estimated settled ADR (by municipality), room stock within 1km, occupancy (OTA-listed inventory basis, estimated) |
■ Government statistics and public data
| MLIT Real Estate Information Library — Official Land Prices (2026) and Zoning |
| MLIT Building Starts Statistics (Construction Starts) |
■ News and press releases