

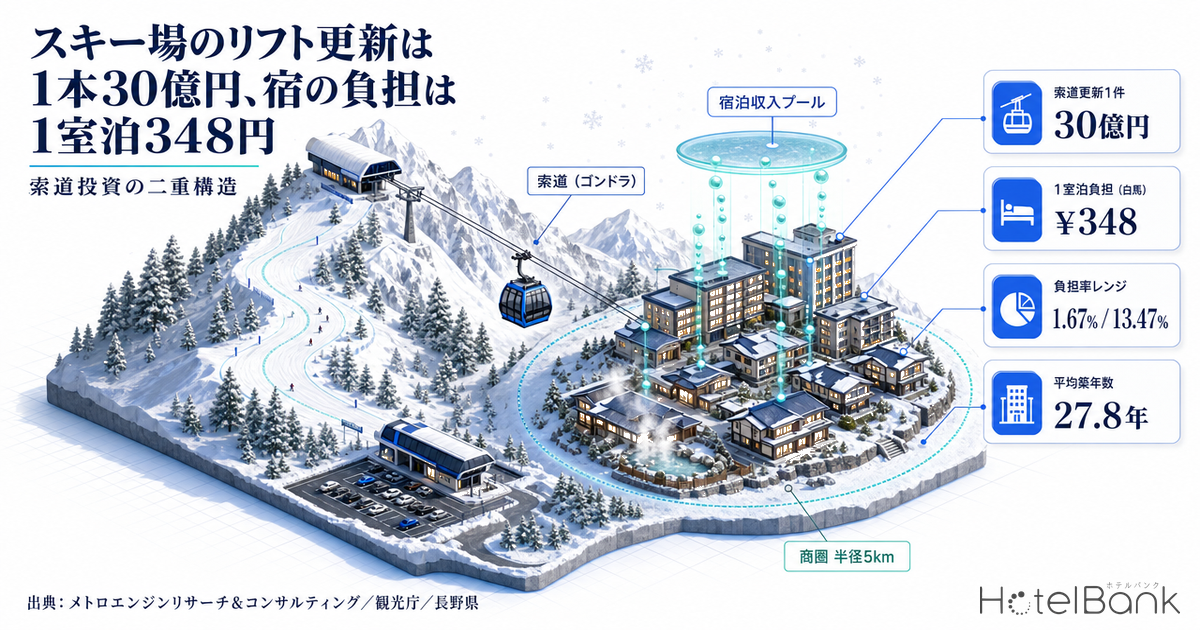
What moves room rates at a ski resort sits outside the hotel. Lifts and gondolas — legally classified in Japan as sakudo, or aerial ropeways — are the foundation of a snow resort’s ability to draw visitors and to set prices. Yet these assets are owned by entirely different companies from the hotels, and their renewal costs sit on entirely different books. This article quantifies that two-tier asset structure using both the publicly disclosed capital expenditure on ropeway renewals and our own aggregated room-rate data for the surrounding areas.
First, how this differs from our earlier work. Our analysis of room stock within 3km of Japan’s 30 major ski resorts treated ski areas as a source of demand and counted how much room inventory had accumulated around them. Individual resort pieces such as Niseko’s Top Tier: Just 2 Hotels, 75 Rooms — Where Fairmont’s 165 Fit focused on operators and room counts, and did not touch the capital spending on the ropeway side. This article shifts the object of analysis from guest rooms to the ropeways themselves, and puts the amount, cycle and payback horizon of their renewal investment at the centre. Room stock is recounted here only as far as it is needed to serve as the denominator in the amortisation calculation.
Metric Definitions Used in This Article
- ADR (average daily rate): an estimated settled rate (tax-excluded equivalent) derived by applying a segment-specific adjustment coefficient to the lowest published plan level for each property (double occupancy, per-room price, tax-included). Cross-checked against property-level actuals disclosed by listed hotel REITs (91 properties, trailing three months), the median error is approximately 7%. These are estimates and differ from each property’s actual transaction prices and accounting figures. Area-level ADR is the median across the properties in scope (the level of a typical property in that area).
- Room count: the total number of guest rooms at lodging facilities located within a 5km radius of each ski area’s base ropeway station (based on our hotel master; because it does not screen for confirmed operation, it is an upper-bound figure for rooms actually on sale).
- Ropeway renewal burden ratio: an original metric of this article. Taking one standard ropeway renewal as ¥3.0bn and dividing it across the room-nights in the catchment, the resulting “burden per room-night” is expressed as a share of that area’s ADR. The formula is ¥3.0bn ÷ (rooms × 100 winter nights × 60% occupancy (an assumed winter-season value applied against the January 2026 ADR; not a measured occupancy rate) × 15-year amortisation) ÷ ADR.
- Sakudo (ropeway): the term used in Japan’s Railway Business Act and Ropeway Regulations, covering chairlifts, gondolas and aerial tramways collectively.
- Data sources: MetroEngines Research & Consulting (lodging side) / company disclosures, the Japan Tourism Agency and Nagano Prefecture (ropeway side)
- — One ropeway renewal costs ¥0.85bn to over ¥10bn — even a single chairlift runs ¥850m, and replacing a gondola is a ¥3bn-class project. That is comparable to the construction cost of an entire mid-sized regional hotel.
- — Average age 27.8 years, 80% over 21 years — the renewal wave has already begun. Against a 30-year asset life, lenders want repayment in 10 to 15 years: a structural gap.
- — The burden ratio ranges from 0.70% to 13.47% — a 19-fold spread — the same ¥3.0bn works out anywhere from ¥430 per room-night (Niseko) to ¥2,227 (Appi Kogen), depending on the depth of the catchment’s lodging revenue pool.
- — In Hakuba, one year of rate growth equals 86% of a ¥3.2bn gondola — the +¥4,954 ADR increase from January 2025 to January 2026 generated roughly ¥2.75bn of additional revenue across the catchment, equivalent to an asset the ropeway side repays over 30 years.
- — Not an unaffordable sum, but a sum where the payer and the beneficiary are misaligned — ropeway credit needs to be reframed around the lodging revenue pool the ropeway supports, not the ropeway’s own P&L.
The ropeway: a capital asset outside the hotel, and heavier than it
Start by fixing the order of magnitude. At Happo-One ski resort in Hakuba Village, Nagano, Hakuba Kanko Kaihatsu and Happo-One Kaihatsu are jointly building a new gondola linking the base to the mid-mountain “Usagidaira” area, together with a centre house and car park. The line is 2,180m long with 652m of vertical, speed rises from 4m to 6m per second, and capacity from 1,350 to 2,400 people per hour. Total investment is ¥3.2bn, with construction started in November 2024 and opening scheduled for December 2027.
The Nagasaka gondola at Nozawa Onsen Village, Nagano, is 3,129m long with 789m of vertical and 80 ten-person cabins. The village replaced it at a project cost of approximately ¥3.0bn from FY2017, completing the work in November 2020. In Kutchan, Hokkaido, Tokyu Land, Niseko Tokyu Resort and Tokyu Resorts & Stay are running a multi-year programme exceeding ¥10bn, beginning with the renewal of the “Ace Gondola”; the new gondola entered service in November 2024, with lift renewals following through the 2026-27 season.
Even standalone chairlifts sit in the same order of magnitude. At the municipal Bibai ski area in Hokkaido, installing a fixed-grip quad chairlift cost ¥850m (excluding tax), and at Cupid Valley in Joetsu, Niigata, the winning bid to remove an existing quad of roughly 1,000m and extend it to about 1,600m was reported at ¥1.4bn. In other words, a ropeway is a piece of equipment whose unit cost matches or exceeds that of building an entire mid-sized regional hotel.
| Project | Location | Scope | Investment | Timing |
|---|---|---|---|---|
| Hakuba Happo-One: new gondola + centre house + car park | Hakuba Village, Nagano | 2,180m line, 652m vertical; capacity 1,350 → 2,400 people/hour | ¥3.2bn | Started Nov 2024 / opening Dec 2027 |
| Nozawa Onsen: Nagasaka gondola replacement | Nozawa Onsen Village, Nagano | 3,129m line, 789m vertical; 80 ten-person cabins | ¥3.0bn | Began FY2017 / completed Nov 2020 |
| Niseko Tokyu Grand Hirafu “Ace Gondola” and multi-year plan | Kutchan, Hokkaido | Converting the highest-volume lift to a gondola, with further lift renewals to follow | ¥10.0bn | In service Nov 2024 / phased through the 2026-27 season |
| Cupid Valley: new No.2 quad chairlift | Joetsu, Niigata | Removing an existing ~1,000m lift and extending to ~1,600m | ¥1.4bn | — |
| Bibai municipal ski area: fixed-grip quad chairlift | Bibai, Hokkaido | New installation of the entire lift including towers | ¥850m | — |
Renewal is not “coming” — it is already overdue: an average age of 27.8 years
What makes these amounts heavy is the renewal cycle. According to a Japan Tourism Agency survey of ski area operators, the average age of ropeway installations nationwide is 27.8 years, and more than 80% have been in place for 21 years or longer. Materials from the Nagano Prefecture Ropeway Operators Council (as of FY2022) show that 90% of the prefecture’s ropeway installations are more than 20 years old. With an equipment life of 30 to 40 years, the renewal wave has already begun.
Nagano Prefecture’s “Policy on Future Ski Area Promotion”, published in March 2024, sets out why renewal investment is not happening, based on interviews with 26 operators and organisations. Maintaining existing equipment and replacing parts alone costs tens of millions to hundreds of millions of yen a year, making it hard to build reserves for renewal; the manufacturers and contractors for ropeways and snowmaking equipment are few, and this oligopoly keeps the cost of new installations and repairs elevated; and for municipally owned ski areas, renewals costing hundreds of millions to billions of yen force consideration of depopulation-countermeasure and remote-area bonds because of the limits of local fiscal capacity.
One line in that policy matters most for readers of this article. “Investment in ropeway facilities is a payback plan spanning more than 30 years, which does not match the business-plan horizon of financial institutions seeking repayment in 10 to 15 years.” That is the operators’ own view, but read from the lender’s side it means that structuring a 15-year repayment on the ropeway’s standalone cash flow rarely produces a workable plan. A gap of roughly 15 years sits structurally between a ropeway’s asset life and the normal repayment horizon for equipment finance.
Public support is not large enough to close that gap either. The Japan Tourism Agency’s “Programme to Promote Internationally Competitive Snow Resorts” (FY2026 application guidelines, published 23 March 2026) sets the subsidy for ski area infrastructure at up to 50% of cost, with a ceiling of ¥300m per individual project plan. The project period is, in principle, a single fiscal year running from the grant decision to 12 February 2027. Against a ¥3.2bn gondola, a ¥300m ceiling covers just under 10% of the total.
What happened on the lodging side: winter rates across 11 major areas
Against that heavy burden on the ropeway side, it is the lodging side that has actually been able to pass the benefit through into price. For the 11 major snow resort areas we track, we compared each municipality’s January estimated settled ADR between 2023 and 2026. The scope is properties within each municipality: 437 properties in total as of January 2026 (N=437), and 574 properties in January 2023.
Growth over the three years has been anything but uniform. Niseko (measured on Kutchan) went from ¥27,979 to ¥61,574, +120.1%, and Hakuba Village from ¥11,180 to ¥21,490, +92.2% — both close to a doubling — while most areas landed in the +30% to +40% range. An important caveat: this gap cannot be read as something ropeway investment “caused”. Inbound demand concentration, the weak yen and the share of repeat visitors from Australia and Asia are among several factors that pushed prices up, and the result cannot be reduced to a single cause.
One thing can be stated as fact, however. The areas where large disclosed ropeway renewals are under way overlap with the areas where rates have risen most. Niseko, with more than ¥10bn of investment in progress, and Hakuba, with a ¥3.2bn gondola due to open in 2027, are the top two areas. Whether the investment created the rate growth or the rate growth made the investment possible cannot be settled from the data — but the fact that both cluster in the same places is itself material to capital allocation decisions.
Reducing the two-tier structure to a single number: the ropeway renewal burden ratio
We introduce a metric that links the ropeway’s renewal cost directly to the income of its beneficiaries on the lodging side. Fixing one standard ropeway renewal at ¥3.0bn, we divide it across the room-nights in each area’s catchment (a 5km radius). Assuming 100 winter nights, 60% occupancy (an assumed winter-season value) and a 15-year amortisation, the resulting “burden per room-night” and its share of that area’s ADR give the ropeway renewal burden ratio.
| Area | Municipality | Properties within 5km | Rooms | Jan 2023 ADR | Jan 2026 ADR | 3-year change | Per room-night | Burden ratio |
|---|---|---|---|---|---|---|---|---|
| Niseko (Hirafu / Village) | Kutchan & Niseko, Hokkaido | 684 | 7,747 | ¥27,979 | ¥61,574 | +120.1% | ¥430 | 0.7% |
| Hakuba Happo-One | Hakuba Village, Nagano | 1,020 | 9,263 | ¥11,180 | ¥21,490 | +92.2% | ¥360 | 1.67% |
| Tsugaike Kogen | Otari Village, Nagano | 346 | 4,267 | ¥9,984 | ¥13,744 | +37.7% | ¥781 | 5.68% |
| Naeba | Yuzawa, Niigata | 85 | 2,606 | ¥16,330 | ¥23,164 | +41.8% | ¥1,279 | 5.52% |
| Nozawa Onsen | Nozawa Onsen Village, Nagano | 347 | 3,073 | ¥13,591 | ¥16,582 | +22.0% | ¥1,085 | 6.54% |
| Shiga Kogen | Yamanouchi, Nagano | 66 | 3,099 | ¥11,340 | ¥15,048 | +32.7% | ¥1,076 | 7.15% |
| Akakura & Myoko | Myoko, Niigata | 299 | 3,448 | ¥9,842 | ¥13,162 | +33.7% | ¥967 | 7.34% |
| Furano | Furano, Hokkaido | 164 | 2,319 | ¥11,861 | ¥16,025 | +35.1% | ¥1,437 | 8.97% |
| Zao Onsen | Yamagata City, Yamagata | 122 | 1,842 | ¥9,873 | ¥17,042 | +72.6% | ¥1,810 | 10.62% |
| Sugadaira Kogen | Ueda, Nagano | 182 | 2,959 | ¥7,613 | ¥10,242 | +34.5% | ¥1,127 | 11.0% |
| Appi Kogen | Hachimantai, Iwate | 66 | 1,497 | ¥11,104 | ¥16,529 | +48.9% | ¥2,227 | 13.47% |
The result ranges from 0.70% to 13.47% — a 19-fold spread. Niseko carries ¥430 per room-night, or 0.70% of ADR; Hakuba ¥360, or 1.67%. In areas whose catchment holds only 1,500 to 2,000 rooms, by contrast, the same ¥3.0bn works out at ¥1,800 to ¥2,200 per room-night, more than 10% of ADR. The price of a ropeway is broadly the same anywhere in Japan, but the size of the lodging revenue pool supporting it differs by more than tenfold — that is what the two-tier asset structure really amounts to.
Two caveats attach to this metric. First, because the 5km yardstick is applied uniformly across all areas, places where lodging is dispersed over a wide area — Shiga Kogen and Appi Kogen among them — have their catchments understated, so their burden ratios skew to the high side. Second, the 60% occupancy assumption (a winter-season value) is common to all areas; where actual occupancy runs higher, the burden ratio falls further. This metric is therefore designed to read relative weight between areas rather than to be precise in absolute terms.
Investment scenarios: whose income repays a ¥3.2bn gondola?
Take Hakuba Happo-One’s ¥3.2bn and work it through in detail. The 5km catchment holds 9,263 rooms across 1,020 properties; at 100 winter nights and 60% occupancy, one season yields 555,780 room-nights. Multiplied by the January 2026 estimated settled ADR of ¥21,490, the catchment’s lodging revenue pool for a single season works out at roughly ¥11.94bn. The ¥3.2bn represents 26.8% of that.
Push further and a more telling number appears. Hakuba Village’s January ADR rose from ¥16,536 in 2025 to ¥21,490 in 2026, an increase of +¥4,954 per room-night. Applying that increase alone to the catchment’s room-nights gives roughly ¥2.75bn — meaning the additional revenue generated by one year of rate growth equals 86% of a single ¥3.2bn gondola. An asset the ropeway side repays over 30 years is, on this arithmetic, matched almost entirely by a single season’s price increase on the lodging side.
Running the same calculation for Niseko (7,747 rooms in the Hirafu and Village 5km catchments), the seasonal lodging revenue pool comes to roughly ¥28.62bn, and the multi-year investment of more than ¥10bn represents 34.9% of it. The year-on-year rate increase (+¥13,623) generated roughly ¥6.33bn of additional revenue, so a ¥10bn investment equals 1.6 seasons of that uplift. At Nozawa Onsen (3,073 rooms), by contrast, the pool is about ¥3.06bn, so a ¥3.0bn gondola is almost exactly one season of lodging revenue. The same “one gondola” means something entirely different depending on the depth of the catchment.
Three amortisation scenarios
A Ropeway repays alone
15 years at 60% occupancy (assumed, winter season): equivalent to ¥348 per room-night
If the ropeway operator alone amortises ¥2.9bn (after deducting a ¥300m subsidy) over 15 years, principal repayment runs ¥193m a year (before interest). Converting the catchment’s guest-nights at double occupancy to 1.11 million person-nights, an increase in ropeway revenue of ¥174 per person per night would cover it. Pricing headroom on the ropeway side is in fact moving: at one resort, an adult day pass went from ¥6,200 in 2021 to ¥14,500 in 2025, roughly a 2.4x increase.
B Beneficiary pays (lodging side)
12.8 years on projected lodging tax revenue
Hakuba Village introduced a lodging tax on 1 June 2026 and projects annual revenue of a little over ¥250m. Were all of it applied to ropeway renewal, ¥3.2bn would be recovered in about 12.8 years (in practice the revenue is earmarked for tourism promotion, environmental conservation and similar purposes; there is no scheme allocating it to ropeway renewal). The required burden against room rates is ¥348 per room-night, or 1.62% of ADR — the same order of magnitude as existing lodging tax levels.
C Subsidy plus longer tenor
30-year amortisation: ¥174 per room-night, 0.81% of ADR
Applying the ¥300m subsidy (9.4% of the total) and amortising the remaining ¥2.9bn over 30 years to match the asset life brings the burden down to ¥174 per room-night. Aligning the repayment horizon with the ropeway’s physical life — as the 27.8-year average age suggests it actually is — is what lightens the burden most. How to arrange long-tenor, low-cost funding is the practical question this scenario raises.
Sensitivity analysis: occupancy and amortisation period
| Hakuba, ¥2.9bn (net of subsidy): burden per room-night | 15-year | 20-year | 30-year |
|---|---|---|---|
| 45% occupancy (downside) | ¥464 (2.16%) | ¥348 (1.62%) | ¥232 (1.08%) |
| 60% occupancy (base) | ¥348 (1.62%) | ¥261 (1.21%) | ¥174 (0.81%) |
| 75% occupancy (upside) | ¥278 (1.29%) | ¥209 (0.97%) | ¥139 (0.65%) |
The range the sensitivity analysis produces is narrow. Even the harshest combination (45% occupancy, an assumed value, with 15-year amortisation) stops at ¥464 per room-night, or 2.16% of ADR, and the loosest conditions bring it down to 0.65%. ¥3.2bn is a large number in absolute terms, but as a ratio to the catchment’s lodging revenue it is a 1-2% world. The problem is not the amount itself; it is that no mechanism exists for the ropeway operator to receive that 1-2%.
Investment summary and risk factors
From the perspective of a fund or corporate buyer, the practical criteria for evaluating a snow resort converge on three points.
| Criterion | What to look at | Implication from this article’s data |
|---|---|---|
| Remaining ropeway life | Installation year of the main ropeways and the renewal spend required over the next decade | National average age 27.8 years, 80% over 21 years. Budget conservatively for a ¥3bn-class renewal envelope separate from the acquisition price |
| Catchment lodging revenue pool | What the ropeway renewal burden ratio (this article’s metric) works out at | A 19-fold spread, 0.70% to 13.47%. Areas below 5% can absorb ropeway capex through price growth in the catchment |
| Path for capturing the benefit | The capital relationship between ropeway and lodging, and the design of lodging tax and area management schemes | The dividing line is whether ropeway and lodging can be placed under common ownership, or a local beneficiary-pays scheme can be designed |
For regional banks and other lenders, the focus of credit assessment shifts. Structuring a 15-year repayment on a ropeway operator’s standalone P&L is hard to reconcile with the horizon, exactly as Nagano Prefecture’s policy recorded from operators. At the same time, a ropeway renewal represents only a 1-2% burden against the catchment’s lodging revenue pool. Whether ropeway credit can be reframed around the lodging revenue of the whole catchment the ropeway supports, rather than the ropeway alone, is the practical dividing line. Kutchan’s allocation of ¥286.3m of lodging-tax-funded spending in FY2024, directed to road heating and similar works in the Niseko Hirafu district, shows that mechanisms for recycling lodging revenue into local infrastructure are already operating.
Risk factors
| Category | Description | Impact on these estimates |
|---|---|---|
| Climate | Declining maximum annual snow depth and number of snowfall days (Nagano’s mean annual temperature has risen roughly 1.3°C per century) | A shorter operating season strikes directly at the “100 winter nights” assumption. Snowmaking investment is added as further capex |
| Demand mix | Where inbound demand is the main driver of rate growth, sensitivity to exchange rates and international air capacity is high | If ADR falls, the burden ratio rises proportionately. The 45% occupancy scenario (an assumed winter-season value) should be read alongside |
| Procurement cost | Manufacturing and installation of ropeways and snowmaking equipment is oligopolistic, keeping costs elevated (from operator interviews in Nagano’s policy) | The ¥3.0bn assumption itself could prove too low. Bundling multiple units or multiple years creates negotiating room |
| Policy | National subsidies are, in principle, 50% of cost, capped at ¥300m, and single-fiscal-year | For large ropeways this covers around 10% of the total. Funding plans premised on subsidies rarely stand up |
| Catchment size | In areas with fewer than 2,000 rooms the burden ratio exceeds 10% | Rather than standalone renewal, wide-area cooperation, ropeway consolidation and year-round operation to enlarge the denominator become the realistic options |
Conclusion
A snow resort is built on two layers that belong to entirely separate sets of books: the ropeway, a capital-intensive fixed asset, and the lodging assets clustered around it. Ropeway renewal is a ¥3bn-class undertaking, the average installation is 27.8 years old so the renewal wave has already begun, lenders want repayment in 10 to 15 years against a 30-year asset life, and the national subsidy ceiling is ¥300m per project. Viewed from the ropeway side alone, this investment is plainly heavy.
Divide the same amount by the lodging revenue of the catchment the ropeway supports, however, and it becomes ¥360 to ¥2,227 per room-night, or 0.70% to 13.47% of ADR. In Hakuba, the additional revenue from one year of rate growth alone reaches 86% of a ¥3.2bn gondola. Ropeway capex is not “an amount nobody can pay”; it is “an amount where the payer and the recipient are misaligned” — that is this article’s conclusion, and equally where the investment opportunity lies.
So whether the position is acquisition, lending or management contract, the starting point for analysis should not be the ropeway’s standalone P&L but the depth of the catchment as measured by the ropeway renewal burden ratio. Where the ratio is below 5%, ropeway renewal sits comfortably within what price growth on the lodging side can absorb. Where it exceeds 10%, the options are to integrate ropeway and lodging under common ownership, to design a local beneficiary-pays scheme through a lodging tax or area management, or to thicken the denominator itself through year-round operation. In every case, it takes a mindset that brings capital spending outside the hotel into the hotel’s own income plan.
Further Reading
References and Sources
■ Data sources
On the lodging side: municipality-level estimated settled ADR based on OTA published prices and inventory data we collect (January 2023 N=574 properties / January 2025 / January 2026 N=437 properties, all January, median), together with property and room counts within a 5km radius of each base ropeway station from our hotel master. On the ropeway side: capital expenditure figures from operator and municipal disclosures and press reports, and installation age and policy information from Japan Tourism Agency and Nagano Prefecture publications.
■ Calculation assumptions
The ropeway renewal burden ratio fixes “one standard ropeway renewal = ¥3.0bn” and allocates it across the room-nights of the catchment (5km radius) on a principal-only basis, assuming 100 winter operating nights, 60% occupancy (an assumed winter-season value applied against the January 2026 ADR; not a measured occupancy rate) and 15-year amortisation, excluding interest and maintenance costs. The lodging revenue pool is rooms × 100 winter nights × 60% occupancy × that year’s January estimated settled ADR. The sensitivity analysis runs a 3×3 grid of 45/60/75% occupancy (all assumed winter-season values) × 15/20/30-year amortisation. The Hakuba-specific scenarios take ¥2.9bn as the target amount, net of the ¥300m national subsidy.
■ Limitations and caveats
(1) ADR is an estimate and differs from each property’s actual transaction prices and accounting figures (median error approximately 7% when cross-checked against property-level disclosures by listed hotel REITs). (2) Because the catchment is set at a uniform 5km radius, areas where lodging is dispersed over a wide area — Shiga Kogen and Appi Kogen among them — have their catchments understated, so their burden ratios skew to the high side. (3) Occupancy is a single assumption applied to all areas and is not based on actual occupancy statistics. (4) Ropeway investment amounts are on a disclosed or reported basis, and some projects include items beyond the ropeway itself, such as centre houses and car parks. (5) The co-occurrence of rate growth and ropeway investment is noted as a correlation only and does not demonstrate causation. This article aims at comparing relative weight between areas rather than precision in absolute terms.
■ Market data
- MetroEngines Research & Consulting — municipality-level estimated settled ADR (January 2023 / January 2026, N=437 and N=574 properties), and property and room counts within a 5km radius from the hotel master
■ Government and municipal materials
- Japan Tourism Agency, “FY2026 Programme to Promote Internationally Competitive Snow Resorts: Application Guidelines” (23 March 2026) — subsidy rate up to 50%, ceiling ¥300m
- Nagano Prefecture Tourism Department, “Policy on Future Ski Area Promotion, Following the Roundtable on the Future of Nagano’s Ski Areas” (March 2024) — average age 27.8 years, 90% of the prefecture’s ropeways over 20 years old, interviews with 26 operators and organisations
- Japan Tourism Agency, “Developing Internationally Competitive Snow Resorts” (list of policies and support programmes)
- Japan Tourism Agency, Committee on Promoting Internationally Competitive Snow Resorts: final report (March 2026)
- Japan Tourism Agency, Committee on Promoting Internationally Competitive Snow Resorts: summary (March 2026)
- Town of Kutchan, “Projects funded by the lodging tax” — ¥286.3m allocated in FY2024
- Town of Kutchan, “About Kutchan’s lodging tax” — a 3% ad valorem rate from 1 April 2026
- Town of Niseko, “Lodging tax”
■ Primary sources and press coverage on ropeway investment
- Hakuba Happo-One Ski Resort, “Full details announced for the new Happo-One gondola, opening December 2027”
- Shinano Mainichi Shimbun, “¥3.2bn total investment: new gondola to be built at Happo-One ski resort, Hakuba Village” (28 November 2024)
- Nikkei, “Hakuba Happo-One ski resort to invest ¥3.2bn in a new gondola and car park” (December 2024)
- Nikkei, “Nozawa Onsen ski resort completes new gondola lift” (December 2020) — project cost approximately ¥3.0bn
- Tokyu Land, “Value up NISEKO road to 2030 project, phase one”
- Tokyu Resorts & Stay, “Investment of over ¥10bn to raise the experience value of an international mountain resort”
- Niseko Village Co., Ltd., “A new gondola arrives at Niseko Village in winter 2026”
- Ski Dekoboko Laboratory, “A fixed-grip quad chairlift costs ¥850m — Bibai municipal ski area”
- Ski Dekoboko Laboratory, “2026/2027 ski area owners, operators and name changes, new and retired lifts”
- Sanin Chuo Shimpo, “Ski areas fall to a record low of 417, down 40% from the 1999 peak”
- NBS Nagano Broadcasting Systems, “Hakuba Village’s draft lodging tax scheme projects annual revenue of a little over ¥250m”
- Travel Watch, “Hakuba Village starts its lodging tax: ¥200 to ¥1,900 per person per night” (June 2026)