

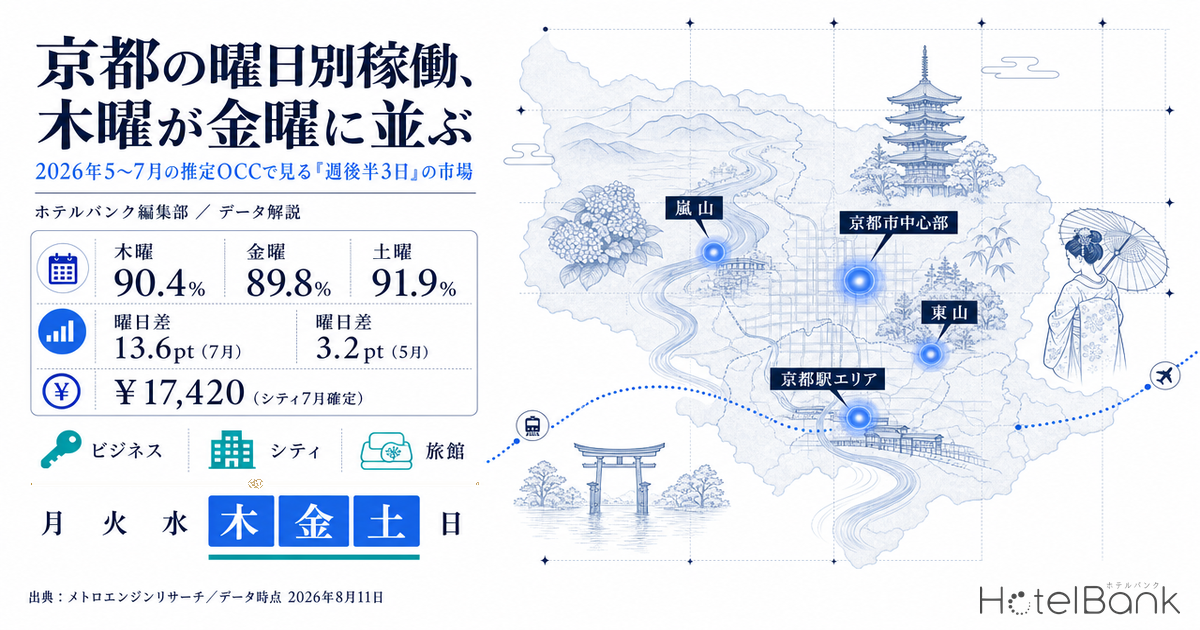
Aggregating daily data for Kyoto Prefecture over May–July 2026 (elapsed months, actuals) by day of week shows business hotels at an estimated OCC of 90.4% on Thursdays (elapsed-month actuals for May–July 2026, N=272–293 properties), slightly ahead of Friday’s 89.8%. City hotels show almost no gap either, with Thursday at 89.3% and Friday at 89.9%. The weakest days, by contrast, are Monday and Sunday at 86.8% for city hotels, Monday at 83.6% for business hotels, and Thursday at 84.0% for ryokan. The day-of-week spread (highest day minus lowest day) is 5.6pt for city hotels, 8.3pt for business hotels, and 6.2pt for ryokan — this is not a market where Saturday alone spikes. That spread, however, changes considerably by month: in May it stayed within 3.2pt for business hotels, while in July it widened to 13.6pt. The more a property runs day-of-week pricing on a fixed annual calendar, the more room it has to capture this month-to-month expansion and contraction of the day-of-week spread.
Scope: Kyoto Prefecture — city hotels N=51–56 properties / business hotels N=272–293 properties / ryokan N=110–182 properties. The price metric in this article is the estimated settled ADR (the transaction price level estimated from OTA and other sales data, tax-exclusive equivalent), and occupancy is an estimate based on OTA-listed inventory. Definitions for both are given at the end of the article. Data as of August 11, 2026.
- — Thursday’s 90.4% tops Friday’s 89.8% — Business hotels in Kyoto Prefecture run flat at around 90% across the three later days of the week (Thu–Sat). City hotels show almost no gap either, at 89.3% Thursday and 89.9% Friday.
- — The day-of-week spread is 5.6pt for city, 8.3pt for business, 6.2pt for ryokan — Aggregated from 92 days of elapsed-month actuals for May–July 2026, weighted by room count. This is not a market where Saturday alone spikes.
- — The spread is a function of the month: 3.2pt in May → 13.6pt in July — The stronger demand is in a given month, the flatter the week becomes; the softer the month, the more Monday–Tuesday and Sunday get cut first.
- — Even the trough sits in the high 80s — Across the three months, the lowest day is 86.8% for city hotels, 83.6% for business hotels, and 84.0% for ryokan. Being a trough is not the same as having inventory to spare.
- — The peak sits in a different place by property type — Ryokan follow a “Sat–Sun” shape at 90.2% Saturday and 87.0% Sunday, while city and business hotels follow a “later-week” shape across Thu–Sat. Mixing property types into one compset blurs day-of-week judgment.
Kyoto’s Estimated OCC by Day of Week — Saturday Peaks, but Thursday Draws Level with Friday
Elapsed-month actuals for Kyoto Prefecture (May 1 – July 31, 2026, 92 days of daily values) were aggregated by day of week and weighted by room count. Saturday is the highest day in all three property types, but the shape of the days leading into it differs by type.
Source: Compiled by the HotelBank Editorial Team from MetroEngines Research data
City hotels (N=51–56) peak at 92.4% on Saturday, followed by Friday at 89.9% and Thursday at 89.3%, with Wednesday 87.9%, Tuesday 87.0%, Monday 86.8%, and Sunday 86.8% at the bottom. The gap between highest and lowest is 5.6pt, and even the trough of the week holds in the 86% range. Business hotels (N=272–293) run at 91.9% on Saturday, while Thursday at 90.4% comes in 0.6pt above Friday’s 89.8% — the three later days of the week sit flat at around 90%. Monday at 83.6% and Sunday at 84.4% are clear troughs, and the 8.3pt spread is the widest of the three types. Ryokan (N=110–182) have their two strongest days at Saturday 90.2% and Sunday 87.0%, with Friday at 85.4% barely above Wednesday 84.8% and Monday 84.5%. Ryokan alone peak on “Sat–Sun” rather than “Fri–Sat.” The pattern of Thursday drawing level with Friday is not unique to Kyoto — the same skeleton of a Sunday trough and a Thursday peak turns up in other regional business-hotel markets as well.
| Day | City (N=51–56) | Business (N=272–293) | Ryokan (N=110–182) |
|---|---|---|---|
| Mon | 86.8% | 83.6% | 84.5% |
| Tue | 87.0% | 85.0% | 84.1% |
| Wed | 87.9% | 86.2% | 84.8% |
| Thu | 89.3% | 90.4% | 84.0% |
| Fri | 89.9% | 89.8% | 85.4% |
| Sat | 92.4% | 91.9% | 90.2% |
| Sun | 86.8% | 84.4% | 87.0% |
| Spread (high − low) | 5.6pt | 8.3pt | 6.2pt |
Estimated OCC (based on OTA-listed inventory) for Kyoto Prefecture, May–July 2026 (elapsed-month actuals, 92 days), aggregated by day of week and weighted by room count / Source: Compiled by the HotelBank Editorial Team from MetroEngines Research data
On a monthly average basis, city hotels ran 92.4% in May, 87.4% in June, and 86.1% in July; business hotels 92.9%, 85.8%, and 83.4%; and ryokan 88.5%, 86.0%, and 83.1%. All three types peak in May and step down through July. The highest single day for both city and business hotels was Saturday, May 23, 2026, at 98.4% and 99.3% respectively.
The Spread “Disappears in Strong Months” — 3.2pt in May, 13.6pt in July
A day-of-week profile that lumps three months together is an average picture of the market, but what matters operationally is the month-to-month expansion and contraction. Splitting business hotels’ estimated OCC by day of week into individual months changes the shape markedly.
Source: Compiled by the HotelBank Editorial Team from MetroEngines Research data
In May, business hotels ran Monday 93.6%, Tuesday 93.3%, Wednesday 91.5%, Thursday 93.7%, Friday 91.7%, Saturday 94.7%, and Sunday 91.6% — a gap between highest and lowest of just 3.2pt. Day of week had all but ceased to function as an axis. June ranges from Sunday 79.5% to Saturday 91.0%, an 11.5pt spread, and July widens to 13.6pt, from Monday 75.7% to Thursday and Saturday at 89.3%. In other words, the more total demand falls away, the more it is Monday and Tuesday at the front of the week and Sunday that get cut first, while the three days from Thursday to Saturday hold their level. In July, business hotels’ Thursday at 89.3% matched Saturday exactly and came in above Friday’s 87.9%.
| Type / Month | Highest day | Lowest day | Spread |
|---|---|---|---|
| City / May 2026 | Sat 94.0% | Sun 91.2% | 2.8pt |
| City / June 2026 | Sat 91.9% | Sun 83.7% | 8.2pt |
| City / July 2026 | Sat 90.9% | Mon 83.2% | 7.7pt |
| Business / May 2026 | Sat 94.7% | Wed 91.5% | 3.2pt |
| Business / June 2026 | Sat 91.0% | Sun 79.5% | 11.5pt |
| Business / July 2026 | Thu & Sat 89.3% | Mon 75.7% | 13.6pt |
| Ryokan / May 2026 | Sat 91.5% | Tue & Fri 86.3% | 5.2pt |
| Ryokan / June 2026 | Sat 91.0% | Tue 84.0% | 7.0pt |
| Ryokan / July 2026 | Sat 88.1% | Thu 81.8% | 6.3pt |
Estimated OCC (based on OTA-listed inventory) for Kyoto Prefecture, May–July 2026 (elapsed-month actuals) / Source: Compiled by the HotelBank Editorial Team from MetroEngines Research data
City hotels move in the same direction: a spread that opened only 2.8pt in May widened to 8.2pt in June and 7.7pt in July. Ryokan run 5.2pt in May, 7.0pt in June, and 6.3pt in July — the smallest month-to-month swing of the three types. With a weekend-led demand structure that is strong to begin with, changes in total volume are less able to reshape the day-of-week profile. Other markets show the same day-of-week metric taking a different form entirely — a “Saturday spike plus a weekday plateau” with two troughs back to back — and that pattern is broken down in Saitama Business Hotels: Sat 77.2% vs Sun 70.1%, Gap Widens to 11pt.
The Pricing Context — May Beat Last Year, June and July Down Double Digits (Confirmed Months Compared Like for Like)
Price cannot be brought into the day-of-week discussion directly. The estimated settled ADR is a metric whose canonical granularity is monthly, so it cannot serve as a basis for arguing price levels by day of week. That said, price movement within the same month is important background for reading which months the day-of-week spread opened up in. Below is Kyoto Prefecture’s estimated settled ADR, comparing confirmed values with confirmed values year over year.
Source: Compiled by the HotelBank Editorial Team from MetroEngines Research data
| Month | 2025 (confirmed) | 2026 (confirmed) | YoY |
|---|---|---|---|
| City / May (N=57) | ¥24,956 | ¥25,867 | +3.7% |
| City / June (N=57) | ¥20,768 | ¥17,738 | −14.6% |
| City / July (N=58) | ¥20,926 | ¥17,420 | −16.8% |
| Business / May (N=329) | ¥13,820 | ¥15,278 | +10.5% |
| Business / June (N=324) | ¥10,659 | ¥9,616 | −9.8% |
| Business / July (N=325) | ¥11,752 | ¥10,230 | −13.0% |
Kyoto Prefecture, estimated settled ADR (tax-exclusive equivalent), confirmed values compared like for like. N = number of properties / Source: Compiled by the HotelBank Editorial Team from MetroEngines Research data
In May, when the day-of-week spread had all but vanished, the estimated settled ADR came in above the prior year at +3.7% for city hotels (¥24,956 → ¥25,867) and +10.5% for business hotels (¥13,820 → ¥15,278). In June and July, when the spread opened up, the figures turned negative by roughly double digits — −14.6% and −16.8% for city hotels, −9.8% and −13.0% for business hotels. The months with a “flat” day-of-week occupancy profile coincide with the months in which price beat the prior year. Note that from August 2026 onward the figures are not confirmed values but estimates based on the current state of sales; city hotels at ¥16,100 and business hotels at ¥9,900 (both August, current estimates) may move with sales going forward, and a simple comparison against last year’s confirmed values is best left until month-end confirmation. How the year-on-year decline in June played out by property type is broken down month by month in Kyoto Hotel ADR Falls YoY in June 2026: City −14.6%, Business −9.8%.
For Revenue Managers Running City and Business Hotels in Kyoto — Implications and an Action Plan
(1) If you are working from the assumption that “Thursday is a weekday,” start by checking it against your own actuals. In the market, business hotels sit at essentially the same level on Thursday (90.4%) and Friday (89.8%), and in July alone Thursday’s 89.3% matched Saturday and came in above Friday’s 87.9%. If your own day-of-week actuals show Thursday below Friday, that may be the shape of how you sell rather than the shape of the market. It is worth checking whether any practice of treating Thursday as an extension of the early week still remains.
(2) Treat the day-of-week spread not as a fixed value but as a variable that expands and contracts by month. For business hotels the spread runs 3.2pt in May, 11.5pt in June, and 13.6pt in July. If you apply the same “Saturday premium” year-round, you are under-valuing the early week in flat months like May and over-valuing it in months like July. There is room to redesign day-of-week coefficients so they switch by month.
(3) Even in the week’s trough the market is in the high 80s — question the premise of across-the-board weekday discounting. Across the three months the lowest day is 86.8% for city hotels, 83.6% for business hotels, and 84.0% for ryokan. The market as a whole is not sitting on a large surplus of inventory. Reaching first for price to fill the trough risks taking demand that would have come in anyway at a discount. Consider levers other than price first — length-of-stay conditions, arrival-day combinations, and the like.
(4) In Kyoto the peak sits in a different place by property type. Revisit the composition of your compset. Ryokan follow a “Sat–Sun” shape at 90.2% Saturday and 87.0% Sunday, while business and city hotels are strongest across Thu–Sat. Because the relevant market shape differs even within Kyoto Prefecture, mixing properties of a different type into your compset will blur day-of-week judgment.
| Horizon | Move | Decision trigger (figures from this article) | Objective |
|---|---|---|---|
| Today – this week | Re-sort your own day-of-week occupancy for the last three months across the three days Thu, Fri, and Sat | The market (business) runs Thu 90.4%, Fri 89.8%, Sat 91.9%. If your Thursday falls 3pt or more below Friday, it warrants a closer look | Redefine where Thursday sits, using actual data |
| Today – this week | Take stock of which days your standing weekday discounts and weekday-only plans apply to | The market’s weekly trough is 86.8% for city and 83.6% for business. Check whether the depth of your discounting is consistent with a trough that sits in the high 80s | Avoid taking demand at a discount that would have come in anyway |
| Within two weeks | Draft a plan to break day-of-week coefficients out from “one set year-round” into monthly sets | The business-hotel spread goes from 3.2pt in May to 13.6pt in July. If your coefficients are fixed year-round, there is room to break them out | Sell differently in flat months and in months when the spread opens |
| Within two weeks | Re-set your compset, separated by property type | Ryokan follow a “Sat–Sun” shape at Sat 90.2% and Sun 87.0%, while city and business hotels follow a Thu–Sat shape. Check whether yours are mixed | Reduce noise in day-of-week judgment |
| Looking to next month | Build the “Monday and Sunday trough” into your rate-revision calendar as a separate slot | In July, business hotels ran Monday 75.7%, 13.6pt below Thursday and Saturday at 89.3%. The depth of the trough changes by month | Handle the early week month by month rather than uniformly |
| Looking to next month | Compare your own monthly rate against the market’s estimated settled ADR range | The market’s confirmed July 2026 figures are ¥17,420 for city and ¥10,230 for business. If you sit well below that while running high occupancy, it is a candidate for a rate increase | Look for headroom in rate rather than occupancy |
Source: Compiled by the HotelBank Editorial Team from MetroEngines Research data
How Much Does the Weekly Average Move If You Move a Day? — A Conversion Using Only the Published Figures
The figures up to this point are day-of-week levels in their own right, but many properties manage to a “weekly average” as their operating metric. A weekly average is the mean of seven day-of-week values, so moving any single day by 1pt necessarily moves the weekly average by one seventh of that. What follows is not a forecast, but a unit conversion using only the day-of-week values published in this article. It contains no new estimation or extrapolation.
Splitting the week into two shapes first: the gap between the three-day average for Thu–Sat and the four-day average for Mon, Tue, Wed, and Sun is 3.4pt for city hotels (90.5% vs 87.1%), 5.9pt for business hotels (90.7% vs 84.8%), and 1.4pt for ryokan (86.5% vs 85.1%). Business hotels show the largest gap between the three later days and the four earlier days, while ryokan — being a Sat–Sun market — show little difference when grouped as Thu–Sat.
| Type | Weekly avg (current) | Case A: one trough day | Case B: two lowest days | Case C: every day below Saturday |
|---|---|---|---|---|
| City | 88.6% | Mon to Saturday’s 92.4% (+5.6pt) Weekly avg +0.80pt → 89.4% | Mon and Sun to Saturday’s 92.4% (+11.2pt) Weekly avg +1.60pt → 90.2% | Mon, Tue, Wed, Thu, Fri, Sun to Saturday’s 92.4% (+26.7pt) Weekly avg +3.81pt → 92.4% |
| Business | 87.3% | Mon to Saturday’s 91.9% (+8.3pt) Weekly avg +1.19pt → 88.5% | Mon and Sun to Saturday’s 91.9% (+15.8pt) Weekly avg +2.26pt → 89.6% | Mon, Tue, Wed, Thu, Fri, Sun to Saturday’s 91.9% (+32.0pt) Weekly avg +4.57pt → 91.9% |
| Ryokan | 85.7% | Thu to Saturday’s 90.2% (+6.2pt) Weekly avg +0.89pt → 86.6% | Tue and Thu to Saturday’s 90.2% (+12.3pt) Weekly avg +1.76pt → 87.5% | Mon, Tue, Wed, Thu, Fri, Sun to Saturday’s 90.2% (+31.4pt) Weekly avg +4.49pt → 90.2% |
Lifting a single trough day to the Saturday level moves the weekly average by only +0.80pt for city hotels, +1.19pt for business hotels, and +0.89pt for ryokan. Only in the extreme case of levelling every day below Saturday up to the Saturday level — that is, of the day-of-week spread disappearing entirely — do you reach +3.81pt for city, +4.57pt for business, and +4.49pt for ryokan.
| Days lifted \ Uplift per day | +2.8pt City, May | +3.2pt Business, May | +5.6pt City, 3-month | +8.3pt Business, 3-month | +13.6pt Business, July |
|---|---|---|---|---|---|
| 1 day | +0.40pt | +0.46pt | +0.80pt | +1.19pt | +1.94pt |
| 2 days | +0.80pt | +0.91pt | +1.60pt | +2.37pt | +3.89pt |
| 3 days | +1.20pt | +1.37pt | +2.40pt | +3.56pt | +5.83pt |
| 4 days | +1.60pt | +1.83pt | +3.20pt | +4.74pt | +7.77pt |
| 5 days | +2.00pt | +2.29pt | +4.00pt | +5.93pt | +9.71pt |
At the bottom right of the grid, lifting five days by the largest day-of-week spread observed in this article (13.6pt for business hotels in July) still moves the weekly average by only +9.71pt. Put the other way round, the weekly average is an extremely insensitive metric with respect to changes in day-of-week structure, and looking only at the weekly average leaves almost no trace of the difference between a month like May, where the spread narrowed to 3.2pt, and a month like July, where it opened to 13.6pt. Action plan items (2), on switching day-of-week coefficients by month, and (5), on building the Monday and Sunday trough in as a separate slot, are moves whose effect becomes visible only when managed at the day-of-week level rather than by weekly average.
Summary — Three Yardsticks for Reading Kyoto’s Week
Yardstick 1: The later week is three days long. Business hotels in Kyoto run Thursday 90.4%, Friday 89.8%, and Saturday 91.9% — Thursday is on par with Friday. City hotels show almost no gap either, at 89.3% Thursday and 89.9% Friday. A two-day design built on “weekend = Fri and Sat” may be leaving a day on the table in this market.
Yardstick 2: The day-of-week spread is a function of the month. For business hotels the spread runs 3.2pt in May, 11.5pt in June, and 13.6pt in July. The stronger demand is in a month, the flatter the week becomes; the softer the month, the more it is cut from the front of the week. Day-of-week coefficients fit better held monthly than fixed year-round.
Yardstick 3: Look at the absolute level of the trough. Across the three months, even the lowest day is 86.8% for city hotels, 83.6% for business hotels, and 84.0% for ryokan. Being a trough is not the same as having inventory to spare. Check the actual level of the trough before discounting.
About the Data
- Definition of estimated OCC (based on OTA-listed inventory): occupancy based on OTA-listed inventory = 100 − 100 × rooms remaining on OTA listings ÷ total rooms. It is an estimate based on how listed inventory sells through on OTAs, and its definition differs from actual room occupancy (it reads higher). The months covered in this article are May, June, and July 2026 (all elapsed months), and day-of-week values were aggregated from each month’s daily values, weighted by room count.
- Estimated OCC by day of week and by day is based on listed inventory at the last observation point before the stay date (lead time 0–2 days for the months covered in this article).
- Definition of estimated settled ADR: the transaction price level (tax-exclusive equivalent) estimated from OTA and other sales data (lowest-plan level × property-type coefficient, ensembled across multiple channels). Past months are confirmed values; the current and future months are estimates based on the current state of sales. Median error against published operating results is 6.6%.
- Breakdown of properties covered (N): for estimated OCC, Kyoto Prefecture city hotels N=51–56, business hotels N=272–293, ryokan N=110–182 (the range of properties observed on a daily basis). For estimated settled ADR, Kyoto Prefecture city hotels N=57–58 and business hotels N=324–329 (May–July 2026).
- Data as of August 11, 2026. Sales conditions and inventory move daily, so the figures in this article are a snapshot as of the time of retrieval.
References and Sources
■ Data sources
Estimated OCC (based on OTA-listed inventory) and estimated settled ADR are drawn from aggregated data compiled by MetroEngines Research & Consulting. The scope is Kyoto Prefecture, covering 92 days of elapsed-month actuals from May 1 to July 31, 2026. Day-of-week values use listed inventory at the last observation point before each stay date (lead time 0–2 days for the months covered in this article), with each month’s daily values aggregated and weighted by room count. Estimated settled ADR is compared year over year between confirmed months, with a median error of 6.6% against published operating results (tax-exclusive equivalent). Properties covered: for estimated OCC, city N=51–56, business N=272–293, ryokan N=110–182; for estimated settled ADR, city N=57–58, business N=324–329.
■ Calculation assumptions
Tables 5 and 6 in “How Much Does the Weekly Average Move If You Move a Day?” are built solely on the identity that treats the weekly average as the simple mean of the seven day-of-week values: moving one day by Δpt moves the weekly average by Δ ÷ 7. The lift target in Table 5 is each property type’s Saturday (city 92.4%, business 91.9%, ryokan 90.2%), and the five levels across the top of Table 6 (+2.8 / +3.2 / +5.6 / +8.3 / +13.6pt) are all day-of-week spreads observed in this article, with no extrapolation outside the observed range. These are unit conversions of the published day-of-week values, not forecasts of future occupancy or price. Price levels by day of week have not been calculated, because the estimated settled ADR is a metric whose canonical granularity is monthly.
■ Limitations and caveats
Estimated OCC is an estimate based on how OTA-listed inventory sells through; its definition differs from actual room occupancy and it reads higher. Listed inventory moves daily, so the figures in this article are a snapshot as of the time of retrieval (August 11, 2026), and re-aggregating on the same basis at a later date may shift both the number of properties observed and the levels. Day-of-week values are aggregations of daily observations whereas estimated settled ADR is a monthly metric, so the two do not share the same granularity. The weekly averages in Tables 5 and 6 are simple means of the seven day-of-week values published in this article, and may not agree to the first decimal place with a market-wide average computed on a room-count-weighted basis. The populations for the three property types are independent, and level differences between types include differences in the mix of properties.
Related Reading
- Kyoto Hotel ADR Falls YoY in June 2026: City −14.6%, Business −9.8%
- Kyoto Obon 2026 Booking Curves: Ryokan Add the Most Close In, +11.4pt
- Saitama Business Hotels: Sat 77.2% vs Sun 70.1%, Gap Widens to 11pt
- Autumn School Trips: Weekday Rate Floors in 5 Areas, Nagasaki +1.6pt
- Japan Autumn 2026 Hotel Price Range: 3.3x CV Gap Across 47 Prefectures
- Chiba Settled ADR: H1 2026 Beats Last Year, July Turns −8.2%
- Kyoto Lodging Tax Month 1: Kyoto ADR +18.6% YoY, Mix Shifts Upmarket