

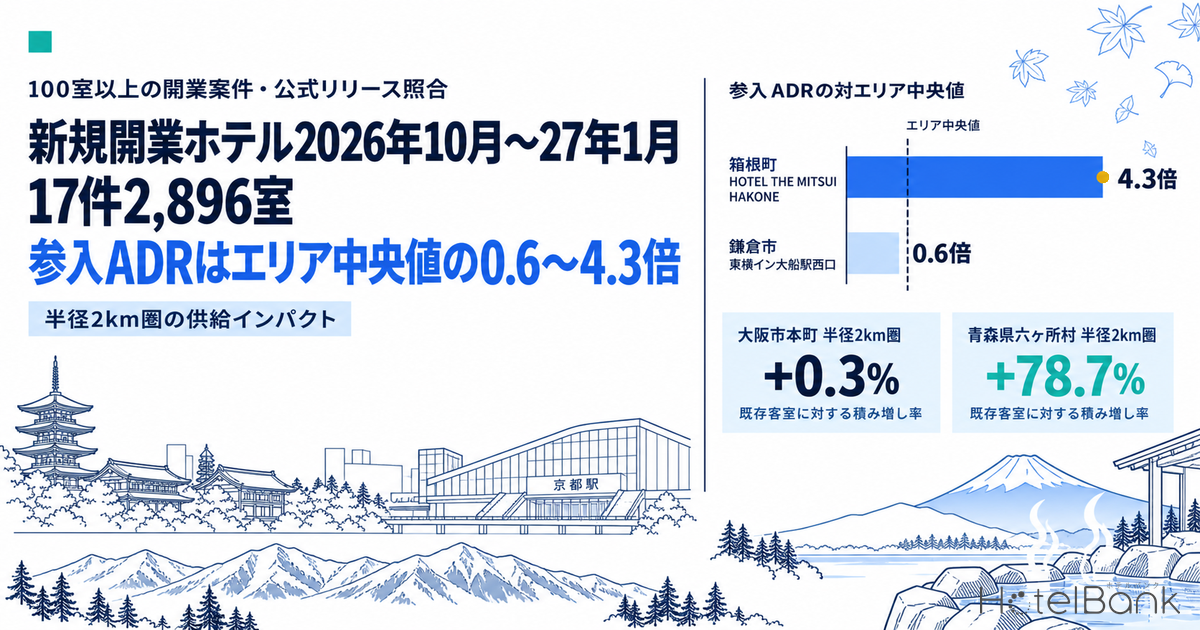
Within the scope tracked by MetroEngines Research, 18 lodging facilities of 100 rooms or more are scheduled to open between October 2026 and January 2027, totalling 3,054 rooms. Reading that figure straight through as “new rooms being added” misses what is actually happening. Checking each project against its official press release, at least two of them — 492 rooms — are rebrands or renovations of existing hotels, leaving a genuine net addition to the market of 2,562 rooms. This article lists all 18 by name, then quantifies how much room stock already exists within a 2 km radius of each project, and which price tier each newcomer is entering.
Metric Definitions Used in This Article
- ADR (average daily rate): an estimated settled rate (tax-excluded equivalent), calculated by applying a segment-specific adjustment factor to the lowest published plan rate each property lists on OTAs and similar channels (two guests per room, per-room rate, tax included). Cross-checked against the per-property results disclosed by listed hotel REITs (91 properties, most recent three months), the median error is approximately 7%. These are estimates and differ from each property’s actual transacted rates and accounting figures. Area-level ADR is the median of the properties covered (the level of a typical property in that area).
- Listed price: the average of all plans published on OTAs and similar channels (two guests per room, per-room rate, tax included). Includes everything from room-only to meal-inclusive plans.
- Supply impact: the new project’s room count divided by the total rooms of existing properties (20 rooms or more) located within a 2 km radius. Shows what percentage is being added on top of the existing stock.
- Data sources: MetroEngines Research (properties, room counts, pricing); official press releases from each company (cross-checking opening dates and room counts); Ministry of Land, Infrastructure, Transport and Tourism, “Statistical Survey on Building Construction Starts” (planning pipeline)
- — 18 projects, 3,054 rooms: properties of 100+ rooms opening between October 2026 and January 2027 (as tracked by MetroEngines Research). Cross-checked against official releases, 492 rooms are rebrands or renovations, leaving a net addition of 2,562 rooms.
- — +0.3% to +78.7%: the rate of addition relative to existing rooms within a 2 km radius. The 202 rooms in Hommachi, Osaka come to +0.3%; the 210 rooms in Rokkasho, Aomori come to +78.7% — roughly a 260-fold difference in weight for openings of the same 200-room class.
- — 0.6x to 4.3x: entry ADR relative to the area median (estimated settled ADR, November–December 2026). Hakone’s 126 rooms come in at 4.3x, establishing a new ceiling; Ofuna’s 122 rooms come in at 0.6x, broadening the base.
18 Projects, 3,054 Rooms — the Full 100+ Room List and Official Cross-Check
We begin by listing every project in the period. The extraction criteria were “100 rooms or more” and “opening between October 1, 2026 and January 31, 2027”; after removing duplicates from our property database, we checked the official release from each operator or developer one by one. Where opening dates or room counts conflicted with our data, the official figure was adopted.
The cross-check produced corrections on two projects. For Solaria Nishitetsu Hotel Osaka Hommachi (ソラリア西鉄ホテル大阪本町), Nishi-Nippon Railroad’s official release states an opening date of December 18, 2026 (our data had December 17). The Grand Castle Naha Shurijo by Hewitt Resort (ザ グランドキャッスル 那覇 首里城 by ヒューイットリゾート) is a rebrand opening on January 1, 2027, structured as a renovation following the end of the current DoubleTree by Hilton Naha Shuri Castle management contract. The latter is a conversion of existing stock, not new construction.
| Opening date | Property | Rooms | Location | Cross-check vs official release |
|---|---|---|---|---|
| 2026/10/01 | Hotel Amanek Kumamoto (ホテルアマネク熊本) | 176 | Kumamoto, Kumamoto | Our data |
| 2026/10/02 | Tabino Hotel Aomori Rokkasho (たびのホテル青森六ヶ所村) | 210 | Rokkasho, Aomori | Matches official (rooms & date) |
| 2026/10/15 | Richmond Hotel Hachinohe Square (リッチモンドホテル八戸スクエア) | 126 | Hachinohe, Aomori | Matches official (rooms & date) |
| 2026/10/15 | HOTEL AZ Okayama Bizen (HOTEL AZ 岡山備前店) | 157 | Bizen, Okayama | Our data |
| 2026/10/16 | Smile Hotel Hachioji Minamiguchi Ekimae (スマイルホテル八王子南口駅前) | 114 | Hachioji, Tokyo | Our data |
| 2026/10/30 | Toyoko Inn Ofuna-eki Nishiguchi (東横イン大船駅西口) | 122 | Kamakura, Kanagawa | Our data |
| 2026/10/31 | Smile Hotel Premium Tottori (スマイルホテルプレミアム鳥取) | 119 | Tottori, Tottori | Our data |
| 2026/11/01 | Kamenoyu by HATAGO INN (亀の湯by HATAGO INN) | 134 | Kumamoto, Kumamoto | Our data |
| 2026/11/15 | Tabino Hotel lit Toyokawa (たびのホテルlit豊川) | 112 | Toyokawa, Aichi | Our data |
| 2026/11/16 | Courtyard by Marriott Kyoto Station (コートヤード・バイ・マリオット京都駅) | 270 | Minami-ku, Kyoto | Matches official (rooms & date) |
| 2026/12/01 | THE ALPS HOTEL HAKUBA | 159 | Otari, Nagano | Official: renovation opening of an existing hotel |
| 2026/12/01 | GRAND HOSTEL LDK Hiroshima (GRAND HOSTEL LDK広島) | 157 | Hiroshima, Hiroshima | Our data |
| 2026/12/10 | Super Hotel Higashi-Hiroshima Hachihonmatsu Natural Hot Spring (スーパーホテル東広島八本松天然温泉) | 148 | Higashi-Hiroshima, Hiroshima | Matches official (rooms); date from our data |
| 2026/12/15 | HOTEL THE MITSUI HAKONE | 126 | Hakone, Kanagawa | Matches official (rooms & date) |
| 2026/12/18 | Solaria Nishitetsu Hotel Osaka Hommachi (ソラリア西鉄ホテル大阪本町) | 202 | Chuo-ku, Osaka | Date corrected per official release (12/17 → 12/18) |
| 2026/12/24 | APA Hotel Shibuya-Ekimae (アパホテル〈渋谷駅前〉) | 231 | Shibuya, Tokyo | Matches official (rooms & date) |
| 2027/01/01 | The Grand Castle Naha Shurijo by Hewitt Resort (ザ グランドキャッスル 那覇 首里城 by ヒューイットリゾート) | 333 | Naha, Okinawa | Official: rebrand of an existing hotel |
| 2027/01/15 | HOTEL AZ Shimane Yasugi (HOTEL AZ 島根安来店) | 158 | Yasugi, Shimane | Date confirmed official (2027/1/15); rooms from our data |
| Total | 18 projects | 3,054 | Of which rebrand / renovation 492 rooms; net new equivalent 2,562 rooms | |
Source: MetroEngines Research (based on confirmed OTA listings) and official company press releases; compiled by the HotelBank Editorial Team
By project count, October leads with seven. By room count, however, October (1,024 rooms) and December (1,023 rooms) are almost level. December has only six projects, but two of them exceed 200 rooms (Solaria Nishitetsu Hotel Osaka Hommachi and APA Hotel Shibuya-Ekimae). The average is 170 rooms per project — for a sample restricted to 100+ rooms, a mix centred on mid-sized business hotels.
Source: MetroEngines Research (based on confirmed OTA listings, N=18 properties); compiled by the HotelBank Editorial Team
This list covers what we track and is not a complete census. Because our property database is built from confirmed OTA listings and publicly announced construction plans, projects that do not open for sale until shortly before opening — and properties launching primarily on corporate contracts or group sales — are picked up late. In practice, OTA listings often do not appear until a few months before opening, so counts for the nearest months tend to accumulate after the fact. It should be read not as a complete list, but as one to be supplemented with official releases for the major projects.
Supply Impact Within a 2 km Radius Runs +0.3% to +78.7% — the Same 200 Rooms Mean Different Things
The absolute room count alone does not tell you how much change a project brings to its area. Solaria Nishitetsu Hotel Osaka Hommachi at 202 rooms and Tabino Hotel Aomori Rokkasho at 210 rooms are almost the same size, yet the existing stock around them is entirely different. So, taking each project’s latitude and longitude as the centre, we cut a 2 km radius and calculated what percentage the new rooms add, using the combined room count of existing properties of 20+ rooms within that radius as the denominator.
Across 12 projects the results ranged from +0.3% to +78.7% — a spread of roughly 260-fold. Hommachi in Osaka already has on the order of 60,000 rooms clustered within a 2 km radius, so adding 202 rooms amounts to just +0.3%. Rokkasho in Aomori, by contrast, has only five properties of 20+ rooms and 267 rooms within its 2 km radius, so introducing 210 rooms is equivalent to +78.7% of existing stock. For the same “200-room-class opening,” the former is a scale that disappears into the market; the latter lifts the area’s lodging capacity a full step. A ranking of all 2026 openings by their ratio to existing stock at the municipality level is explored in Hotel Supply Pressure Ranking 2026-2027: Ozu Kumamoto Tops at 30.8%.
Source: MetroEngines Research (aggregating properties of 20+ rooms within a 2 km radius, N=12 projects); compiled by the HotelBank Editorial Team
The three projects with the largest impact share a trait: all of them sit in locations where the room supply available to meet lodging demand has been thin.
The Rokkasho project is a 210-room, eight-storey steel-frame property operated by Sun Frontier Hotel Management, with a washing machine, microwave and two-door refrigerator in every room, plus a large communal bath, a coin laundry and parking for 160 vehicles. As the official release positions it as “medium-to-long-stay,” the design aims squarely at demand from energy-related construction and maintenance work, where stays run from several weeks to several months. Until now, stay demand of this scale has been absorbed piecemeal across neighbouring municipalities; with 210 rooms concentrated inside the village, clients can build their work schedules on the assumption that accommodation can be arranged. It is a textbook case of demand you can only go after once the capacity to receive it exists.
Tabino Hotel lit Toyokawa (112 rooms) in Toyokawa, Aichi follows the same pattern: existing stock within its 2 km radius is thin at three properties and 254 rooms. Higashi-Mikawa is a manufacturing cluster with steady business-travel demand, but overnight stays tend to flow out to Toyohashi or Nagoya. Adding 112 rooms is equivalent to +44.1% and widens the set of lodging options that can be completed within the area itself.
Toyoko Inn Ofuna-eki Nishiguchi (122 rooms) in Kanagawa comes to +24.7%. Ofuna Station is an interchange hub where the JR Tokaido, Yokosuka and Negishi lines meet the Shonan Monorail, yet properties of 20+ rooms within a 2 km radius were limited to six, totalling 494 rooms. As a base for touring Kamakura, Enoshima and the wider Shonan area, having 122 rooms concentrated right by the station is no small thing. Against a median estimated settled ADR for Kamakura of roughly ¥18,100 as of December 2026 (N=17 properties), this property sits at roughly ¥10,200 for the same month — placing a newly accessible price tier at a touring base. For travellers who want to hold lodging costs down and extend their stay, and for families touring Kamakura and Shonan over several days, the range of options widens.
Location Map of the 18 Projects — a Two-Pole Split Between Major Cities and the Regions
Plotting the 18 projects on a map shows a split into two poles: the major metropolitan areas (Tokyo, Osaka, Kyoto, Hiroshima, Kumamoto) and regional hubs that have had few large hotels until now (Rokkasho, Hachinohe, Bizen, Tottori, Yasugi, Toyokawa and Otari). Circle size corresponds to room count.
Source: MetroEngines Research (based on confirmed OTA listings, N=18 properties) and official company press releases; compiled by the HotelBank Editorial Team
Entry Price Tiers Run 0.6x to 4.3x the Area Median — Projects That Stretch the Top, and Projects That Broaden the Base
As important as the volume of supply is which price tier a new project enters. For projects that have already opened for reservations, an estimated settled ADR can be calculated for the months after opening. Setting that alongside the median estimated settled ADR for the area (municipality) makes the entry position clear.
Source: MetroEngines Research (estimated settled ADR, target months November–December 2026, N=6 projects; area N=9–187 properties); compiled by the HotelBank Editorial Team
| New project | Area | Project ADR | Area median | Ratio | Area N |
|---|---|---|---|---|---|
| Richmond Hotel Hachinohe Square | Hachinohe | ¥8,900 | ¥7,400 | 1.2x | 28 properties |
| Toyoko Inn Ofuna-eki Nishiguchi | Kamakura | ¥10,200 | ¥18,100 | 0.6x | 17 properties |
| Courtyard by Marriott Kyoto Station | Minami-ku, Kyoto | ¥60,600 | ¥25,000 | 2.4x | 53 properties |
| THE ALPS HOTEL HAKUBA | Otari | ¥46,800 | ¥14,400 | 3.2x | 9 properties |
| HOTEL THE MITSUI HAKONE | Hakone | ¥129,700 | ¥30,000 | 4.3x | 159 properties |
| Solaria Nishitetsu Hotel Osaka Hommachi | Chuo-ku, Osaka | ¥19,800 | ¥12,200 | 1.6x | 187 properties |
Source: MetroEngines Research (estimated settled ADR, target months November–December 2026, N=6 projects); compiled by the HotelBank Editorial Team (by opening date)
Hakone is the clearest case. HOTEL THE MITSUI HAKONE, opening December 15, 2026 as a luxury brand of the Mitsui Fudosan group, has 126 rooms across roughly 14 hectares inside Fuji-Hakone-Izu National Park, with a private natural hot-spring bath and a balcony or terrace in every room. Its estimated settled ADR for the opening month is roughly ¥129,700 — 4.3x the Hakone median of roughly ¥30,000 (N=159 properties). This is not an entry aimed at capturing an existing price tier; it is a move that places a new ceiling in Hakone. When the top of the domestic luxury range is lifted, properties in the ¥50,000–¥80,000 band beneath it gain a relative sense of value, and the field of comparison widens. The autumn–winter price tiers in Hakone, and the depth of the upper band this 126-room property enters, are analysed in detail in Hakone’s 126-Room Luxury Supply: Listed +30.9%, Settled ADR +5.7%.
Courtyard by Marriott Kyoto Station, opening November 16 at the Hachijo East exit of Kyoto Station, was built by the JR Central group on the former site of Hotel Saint Nom Kyoto: nine storeys above ground, roughly 15,900 m² of total floor area, and 270 rooms including suites. Its estimated settled ADR for the opening month is roughly ¥60,600 — 2.4x the median for Minami-ku, Kyoto of roughly ¥25,000 (N=53 properties). The area around Kyoto Station is one of Japan’s densest, with 325 properties and 33,499 rooms clustered within a 2 km radius, so adding 270 rooms is +0.8% and the volume impact is small. What matters more is that an international brand’s upper-midscale tier is arriving in force on the Hachijo side. The south side of Kyoto Station is thinner in branded hotels than the north (Karasuma) side, which widens the room to capture global-chain loyalty members and business travellers whose corporate travel policies specify particular brands.
In contrast, in Kamakura, Toyoko Inn Ofuna-eki Nishiguchi enters at 0.6x the median. Rather than stretching the area’s price range upward, it broadens the base beneath. Kamakura and Shonan are destinations with a high day-trip share, and the higher nightly rates go, the more easily visitors default to day trips. Adding an affordable price tier right by the station leads to longer stays and a wider touring radius. Even within the same “new supply,” a project that stretches the top and one that broadens the base mean entirely different things to incumbent properties.
Solaria Nishitetsu Hotel Osaka Hommachi in Hommachi, Osaka comes in at 1.6x the median. It is the tenth property under Nishi-Nippon Railroad’s “SOLARIA” brand and its first in Osaka, with 202 rooms directly connected to Exit 2 of Osaka Metro Hommachi Station; according to the official release, it offers triple and quad rooms as well as rooms fitted with a mini-kitchen and washing machine for medium-to-long stays. Chuo-ku, Osaka has tracked an estimated settled ADR in the ¥9,300–¥13,500 range since June 2026, and this property stands at around ¥19,800 within that. The design goes after multi-night and larger-party demand that the existing, single-room-dominated inventory mix has not been able to absorb.
492 Rooms Are Not a “Net Increase” — How to Tell Rebrands and Renovation Openings Apart
The treatment of rebrands and renovation openings is where supply analysis most often goes wrong. Of these 18 projects, the largest by room count — The Grand Castle Naha Shurijo by Hewitt Resort (333 rooms) — is, according to Core Global Management’s official release, a rebrand opening on January 1, 2027 following renovation after the end of the current DoubleTree by Hilton Naha Shuri Castle management contract. Both the building and the rooms already exist, and Naha’s room stock does not grow by a single unit. The Shuri area has 44 properties and 5,169 rooms within a 2 km radius, so a mechanical calculation gives a +6.4% impact — but the actual net addition is zero rooms.
THE ALPS HOTEL HAKUBA (159 rooms) in Otari, Nagano is the same: it is structured as a renovation of the existing Hakuba Alps Hotel, which Plan Do See began operating on April 1, 2026, reopening in December under a new brand. Directly connected to the Hakuba Norikura ski area, it has a hot-spring communal bath, sauna, outdoor pool, childcare facility and ski school, with rooms of 27–100 m². Existing stock within a 2 km radius is thin at 28 properties and 1,156 rooms, so a mechanical calculation gives +13.8% — but this too is not a net addition.
Subtracting these two, the net addition to the market out of 18 projects and 3,054 rooms comes to 2,562 rooms. When estimating supply pressure, using the list’s total room count as-is overstates the net addition (2,562 rooms) by roughly 20%.
That said, the market impact of a rebrand or renovation is not zero. In terms of shifting price tiers it can in fact matter more than a net addition. THE ALPS HOTEL HAKUBA’s estimated settled ADR after opening is set at roughly ¥46,800 for December 2026 and roughly ¥56,400 for January 2027 — well above the Otari median of roughly ¥14,400 (N=9 properties). The same 159 rooms will now be sold into a different price tier and to a different guest segment. The Hakuba area has deep inbound ski demand and the conditions to attract travellers whose willingness to pay per night exceeds that of domestic guests. For incumbent properties, one way to read this is that a lift in the area’s overall rate level creates an environment in which revisiting their own pricing becomes easier to justify.
Whether a project is a rebrand or new construction cannot be determined without reading the body of the official release. When the property name changes and only the room count is recorded, it accumulates in the data as a “new opening.” In any discussion of supply, it is worth verifying the structure of each project individually — at minimum for those above 200 rooms.
The Pipeline Beyond — 13 Projects and 3,195 Rooms in 2027, but Read It as a Floor
To look beyond these four months, we aggregated lodging projects of 100+ rooms by year from construction-plan data based on the Ministry of Land, Infrastructure, Transport and Tourism’s “Statistical Survey on Building Construction Starts.” The distribution comes out as 18 projects and 4,554 rooms in 2025, 14 projects and 3,851 rooms in 2026, 13 projects and 3,195 rooms in 2027, and 6 projects and 1,175 rooms in 2028.
Source: compiled by MetroEngines Research & Consulting from the Ministry of Land, Infrastructure, Transport and Tourism “Statistical Survey on Building Construction Starts” (100+ rooms, duplicates excluded, N=52 projects, 2025–2029)
The caution here is that the decline from 2028 onward must not be read as “the pipeline drying up.” Building confirmation applications are normally filed one to two years before opening. The counts for 2028 and 2029 are therefore a floor, counting only projects for which applications have already been filed, and they will certainly rise as further applications come in. Note: these figures are based on confirmation applications as of the survey date; project and room counts are expected to increase as further applications are filed, and they should be referenced as a floor for the currently confirmed pipeline.
The same structure applies to this article’s own list. Because OTA listings appear only a few months before opening, projects opening from February 2027 onward are barely captured at this point. That only two projects are recorded for January 2027 does not mean there are only two openings that month — it means the listings and announcements have not yet come through in full.
Demand You Can Go After Once Capacity Exists
Viewed from an incumbent property’s perspective, a debate about volume alone does not translate into action. Organising these 18 projects brings into view three layers of demand that incumbents can newly go after.
First, group and block demand. Where an area’s total room count is thin, a booking that holds 20 or 30 rooms at once physically cannot be accepted. When additions on the scale of Rokkasho’s +78.7% or Toyokawa’s +44.1% — more than half the existing stock — arrive, the area crosses the capacity line at which it can host groups. That is not a benefit to the new property alone: for surrounding incumbents it becomes an opportunity to receive referred guests as overflow capacity. The moment a large project comes online in an area is a good time to revisit your own group plans and group-oriented room inventory.
Second, multi-night and medium-to-long stays. This list includes several projects that build extended stays explicitly into their design. Tabino Hotel Aomori Rokkasho fits every room with a washing machine, microwave and two-door refrigerator; Solaria Nishitetsu Hotel Osaka Hommachi provides rooms with a mini-kitchen and washing machine. Multi-night demand carries a lower rate per night, but it supports the floor of occupancy and smooths housekeeping costs. When projects like these enter an area, multi-night options become visible and latent multi-night demand surfaces more readily as a market. For incumbents, designing three-night-plus plans and improving laundry facilities widens the segment they can reach.
Third, the upper inbound price band. HOTEL THE MITSUI HAKONE in Hakone, THE ALPS HOTEL HAKUBA in Hakuba and Courtyard by Marriott Kyoto Station all enter at 2.4x to 4.3x the area median. This band is hard to fill on domestic leisure guests alone, and its main target is inbound travellers whose willingness to pay is high in foreign-currency terms. When the ceiling is lifted, the whole area’s price reference point moves. For mid-tier properties, a large price anchor placed above them makes their own level easier to read as “mid-range” rather than “expensive” — a tailwind when considering a rate revision.
An increase in supply, in itself, thins each property’s share if total demand does not change. Judging by this list, however, most of the rooms being added are not designed to take existing price tiers and existing guest segments head-on. Each either establishes a new upper band, picks up a stay format that had no capacity before, or places capacity in a regional hub where capacity was thin. For incumbents within an area, overlaying which band you occupy with which band the new projects are entering is the starting point for deciding what to do next.
⚠ Note on ADR for future dates: ADR figures in this article for September 2026 onward are estimates based on rates published on OTAs and similar channels as of the survey date, and they shift as the check-in date approaches. Pre-opening properties are still at a stage where plans continue to be added and revised, so current levels will not necessarily become post-opening results. Please also note that Otari (N=9 properties), Kamakura (N=17 properties) and Hachinohe (N=28 properties) cover a limited number of properties, so their area medians are subject to greater variation.
Conclusion
Within the scope tracked by MetroEngines Research, 18 lodging facilities of 100+ rooms and 3,054 rooms are opening between October 2026 and January 2027. Cross-checking each against its official release, 492 rooms (two projects) are rebrands and renovation openings of existing properties, leaving a net addition to the market of 2,562 rooms. A discrepancy against the official release was also found on one opening date. Any discussion of total supply needs a step that verifies how each project is structured, rather than using the list total as-is.
Supply impact within a 2 km radius spreads widely from +0.3% to +78.7%: metropolitan projects settle inside thick existing stock, while regional projects are large enough to lift the area’s lodging capacity a step. Entry price tiers likewise spread from 0.6x to 4.3x the area median, mixing projects that establish a new ceiling with projects that broaden the base. Only by overlaying both volume and price tier does it become readable what will actually happen to your own property.
Related Reading
References and Sources
■ Market data
- MetroEngines Research — properties and room counts (based on confirmed OTA listings), estimated settled ADR, aggregation of existing supply within a 2 km radius
- From the Ministry of Land, Infrastructure, Transport and Tourism, “Statistical Survey on Building Construction Starts” — compiled by MetroEngines Research & Consulting — construction plans for lodging facilities of 100+ rooms
■ Official company press releases (cross-checking opening dates and room counts)
- Mitsui Fudosan, “HOTEL THE MITSUI HAKONE to open December 15, 2026” (July 13, 2026)
- Nishi-Nippon Railroad, “Solaria Nishitetsu Hotel Osaka Hommachi to open December 18, 2026” (April 17, 2026)
- Central Japan Railway Company, “Courtyard by Marriott Kyoto Station to open November 16, 2026”
- APA Hotel, “APA Hotel Shibuya-Ekimae scheduled to open Thursday, December 24, 2026”
- Core Global Management, “The Grand Castle Naha Shurijo by Hewitt Resort to rebrand-open January 1, 2027”
- Plan Do See, “Reservations open for THE ALPS HOTEL HAKUBA, opening December 2026”
- Sun Frontier Fudousan, “Tabino Hotel Aomori Rokkasho begins accepting reservations” (2026)
- Royal Holdings, “Richmond Hotel Hachinohe Square to open autumn 2026”
- Super Hotel, “Super Hotel Higashi-Hiroshima Hachihonmatsu Natural Hot Spring” official page
- Amaze, “HOTEL AZ Shimane Yasugi” official page (opening January 15, 2027)
■ Press coverage
- Travel Watch, “Courtyard by Marriott Kyoto Station to open November 16”
- Okinawa Times, “The Grand Castle name returns: renovation planned for Shuri, Naha in January 2027”
- Chugoku Shimbun Digital, “Super Hotel to enter Hachihonmatsu-higashi, Higashi-Hiroshima”
■ Official statistics
- Ministry of Land, Infrastructure, Transport and Tourism, “Statistical Survey on Building Construction Starts” (lodging facility plans on a construction-start / confirmation-application basis)