


We count 14 major luxury hotels scheduled to open in Japan between late 2026 and 2030, and the 12 with disclosed room counts total 1,480 rooms (projects we could confirm from public materials, as of November 2026). By year, 8 projects cluster in 2028; by area, Tokyo leads with 3 projects and 437 rooms, followed by Yokohama, Hakone, Setouchi, Kyoto, Sapporo, Kobe and Okinawa. This article lists the luxury hotel pipeline by year and by prefecture, then overlays each site’s city/ward-level estimated settled ADR for September 2026 and the depth of existing room stock within a 1km radius.
- — 14 projects, 1,480 rooms: major luxury hotels scheduled to open from late 2026 to 2030. The room total covers the 12 projects with disclosed counts, as far as we could confirm from public materials as of November 2026.
- — 8 projects and 592 rooms cluster in 2028. The two Setouchi projects have reportedly slipped from summer 2027 to 2028, so the peak year could still move (Table 12).
- — Tokyo, Yokohama and Hakone account for 929 rooms, or 62.8%. Including Yokohama Royal Park Hotel’s post-reopening rooms and IHG’s two projects lifts the Greater Tokyo share to as much as 76.8% (Table 11).
- — Planned rooms equal only 1–2% of operating rooms within 1km in the big cities, but carry far more weight where stock is thin: Naoshima 88.0%, Miyajimaguchi 16.1%, Kowakudani 14.4% (as of November 12, 2026).
- — September 2026 estimated settled ADR in the host municipality ranges from ¥25,900 in Hakone to ¥8,600 in Takamatsu, and the number of properties with ADR of ¥30,000+ within 1km ranges from 12 around Gora Station to zero around Takamatsu Station.
Luxury Hotel Openings by Year — 8 of 14 Projects Fall in 2028
| Opening | Projects | Disclosed rooms (total) | Projects (location, rooms) |
|---|---|---|---|
| December 2026 | 1 | 126 rooms | HOTEL THE MITSUI HAKONE (Hakone, 126 rooms) |
| 2027 | 3 | 469 rooms+ | Waldorf Astoria Tokyo Nihonbashi (ウォルドーフ・アストリア東京日本橋) (Chuo-ku, 197 rooms) / Conrad Yokohama (コンラッド横浜) (Naka-ku, Yokohama, 272 rooms) / Four Seasons Okinawa (tentative name) (Onna Village, not counted) |
| 2028 (incl. fiscal-year dates) | 8 | 592 rooms+ | Mandarin Oriental Setouchi – Takamatsu (Takamatsu, 92 rooms) / Mandarin Oriental Setouchi – Naoshima (Naoshima, 22 rooms) / Raffles Tokyo (Minato-ku, 130 rooms) / Dorchester Collection hotel (name TBA) (Chiyoda-ku, 110 rooms) / LXR Hotels & Resorts Hakone Gora hotel project (tentative) (Hakone, 94 rooms) / Umiuta Hiroshima, LXR Hotels & Resorts (Hatsukaichi, 61 rooms) / Regent Kyoto (Sakyo-ku, Kyoto, 83 rooms) / Yokohama Royal Park Hotel (reopening as a Luxury Collection hotel) (Nishi-ku, Yokohama; not counted — 603 rooms before closure) |
| 2029 | 1 | 157 rooms | Park Hyatt Sapporo (パーク ハイアット 札幌) (Chuo-ku, Sapporo, 157 rooms) |
| 2030 | 1 | 136 rooms | Conrad Kobe (コンラッド神戸) (Chuo-ku, Kobe, 136 rooms) |
| Total | 14 | 1,480 rooms+ | Room total sums the 12 projects with disclosed counts. “+” indicates projects whose rooms are not included in the total. |
Source: Compiled by HotelBank Editorial Team from company disclosures (Hilton “Company Overview,” updated August 25, 2026; Hyatt Japan “Press Materials, April 2026”; and others)
*Opening dates follow each company’s wording (including “scheduled” and fiscal-year dates) and are not confirmed opening dates. The two Mandarin Oriental Setouchi properties are placed in 2028 based on July 2026 reports. Four Seasons Okinawa (tentative name) is excluded from the room total because we could not confirm the current plan’s room count in primary sources, and Yokohama Royal Park Hotel because its post-reopening room count has not been disclosed.
Browse by prefecture
Tokyo (3) Kanagawa (Yokohama 2, Hakone 2) Kyoto (1) Hyogo (1) Hokkaido (1) Kagawa & Hiroshima (Setouchi 3) Okinawa (1) Undated projects Totals by region
• ADR (average daily rate) = estimated settled rate (tax-excluded equivalent), calculated by applying segment-specific adjustment factors to the lowest plan level each property publishes on OTAs (per room, 2 guests, tax-included). Checked against property-level results disclosed by listed hotel REITs (91 properties, last three months), the median error is about 7%. These are estimates and differ from each property’s actual settled prices and accounting figures.
• ADR at the area level (prefecture, city/ward/town) is the median of the estimated settled rates of covered properties (the typical property level in the area).
• References to listed prices mean the per-room rate for 2 guests (tax-included).
• OCC (occupancy) = share of rooms sold out of total rooms in the area (estimate based on OTA sales inventory).
• Source: MetroEngines Research (continuously tracks OTA public prices for about 168,000 properties in Japan, of which about 27,000 are confirmed as operating)
Room stock in this article covers lodging properties with 10+ rooms (excluding leisure/love hotels) within a 1,000m radius of each site’s nearest station or block (shown in each table). “Operating” means properties with selling prices observed on major booking sites in the last three months (September–November 2026), as of November 12, 2026 (MetroEngines Research). “Upper price tier” means operating properties in the radius with an estimated settled ADR of ¥30,000 or more in September 2026. MetroEngines Research tracks about 168,000 properties in Japan, of which roughly 27,000 properties and 1.26 million rooms confirmed as operating on OTAs form the analysis universe.
Inclusion Criteria — Only Projects With Timing and Location Confirmed in Public Materials
First, the scope of the list. We included projects whose brand, location and opening timing could be confirmed in materials published by the operator or developer. For Hilton, we transcribed the luxury-tier brands among the scheduled openings in its “Company Overview” (updated August 25, 2026); for Hyatt, the new openings listed in Hyatt Japan’s “Press Materials, April 2026” — each in the wording of the source. Other projects are included only where room counts and timing could be confirmed by cross-checking developer announcements against major media reports.
Conversely, plans that have been named but whose timing or scale we could not verify in primary sources are not listed. The figure of 14 is therefore not a census of every project in Japan, but the range we were able to confirm. Opening dates also shift with construction schedules and materials procurement, so check developers’ announcements for the latest status of each project.
Source: Compiled by HotelBank Editorial Team from company disclosures (Hilton “Company Overview,” updated August 25, 2026; Hyatt Japan “Press Materials, April 2026”; and others)
Tokyo — 3 Projects, 437 Rooms in Nihonbashi, Tokyo Station and Hamamatsucho, All on Upper Floors of Large Redevelopments
All three Tokyo projects are embedded in major central-city redevelopments: Waldorf Astoria Tokyo Nihonbashi (197 rooms, scheduled for 2027); a Dorchester Collection hotel on the upper floors of Torch Tower in front of Tokyo Station (110 rooms, scheduled for FY2028, name TBA); and Raffles Tokyo on floors 36–46 of the World Trade Center Building Main Tower in Hamamatsucho (130 rooms, scheduled for 2028) — 437 rooms in total.
| Project / location, opening | Rooms | Municipality ADR, Sep 2026 | Existing rooms within 1km (listed on major booking sites) |
|---|---|---|---|
| Waldorf Astoria Tokyo Nihonbashi Chuo-ku / scheduled 2027 Basis: Hilton “Company Overview” | 197 rooms | Chuo-ku: ¥17,270 (−2.4% YoY, N=152) | Within 1km of Nihonbashi Station: 89 operating properties, 12,203 rooms (planned rooms = 1.6% of operating rooms) Upper price tier: 12 (of 68 with ADR) |
| Dorchester Collection hotel (name TBA) Chiyoda-ku / scheduled FY2028 Basis: Mitsubishi Estate announcement (Nov 2022) | 110 rooms | Chiyoda-ku: ¥14,900 (−3.5% YoY, N=80) | Within 1km of Tokyo Station Nihonbashi Exit: 68 operating properties, 10,047 rooms (planned rooms = 1.1% of operating rooms) Upper price tier: 12 (of 54 with ADR) |
| Raffles Tokyo Minato-ku / scheduled 2028 Basis: Tokyo Tatemono and 3 others announcement (Jul 2024) | 130 rooms | Minato-ku: ¥16,078 (−6.6% YoY, N=133) | Within 1km of Hamamatsucho Station: 51 operating properties, 8,324 rooms (planned rooms = 1.6% of operating rooms) Upper price tier: 4 (of 43 with ADR) |
Source: Compiled from company disclosures, MetroEngines Research and HotelBank Editorial Team (ADR = estimated settled ADR, tax-excluded equivalent; room stock as of November 12, 2026)
September 2026 estimated settled ADR in the host wards was ¥17,300 in Chuo-ku (N=152 properties), ¥14,900 in Chiyoda-ku (N=80) and ¥16,100 in Minato-ku (N=133) — all in the mid-to-high ¥10,000s. Ward medians include many business hotels and sit in a different tier from the price band the three new projects target. Counting the upper price tier within 1km instead, we found 12 properties each around Nihonbashi Station and Tokyo Station’s Nihonbashi Exit, and 4 around Hamamatsucho Station. Because Nihonbashi and the Tokyo Station front are close and their radii overlap, those two projects will face the same set of existing properties.
In terms of room depth, the 1km radius of Nihonbashi Station holds 89 operating properties with 12,203 rooms, and Hamamatsucho Station 51 properties with 8,324 rooms. The three new projects equal only 1–2% of operating rooms in each radius — not enough to move the market on volume. Their significance lies rather in adding reference points that mark the upper bound of area pricing.
Kanagawa — In Yokohama, One New Build and One Reopening; in Hakone, Two Projects With Onsen Rooms Totaling 220 Rooms
Kanagawa has two projects each in Yokohama and Hakone. In Yokohama, alongside Conrad Yokohama (272 rooms, scheduled for 2027) in a mixed-use complex in the Kitanaka-dori district, Yokohama Royal Park Hotel — closed since the end of March 2025 — is scheduled to reopen in FY2028 as a Marriott International “Luxury Collection” hotel. The latter had 603 rooms before closing, but its post-reopening room count has not been disclosed, so it is excluded from our room total. The scale of the renovation and its economics are covered in detail in our analysis of the Yokohama Royal Park Hotel reopening.
| Project / location, opening | Rooms | Municipality ADR, Sep 2026 | Existing rooms within 1km (listed on major booking sites) |
|---|---|---|---|
| Conrad Yokohama Naka-ku, Yokohama / scheduled 2027 Basis: Hilton “Company Overview” | 272 rooms | Naka-ku, Yokohama: ¥12,428 (+11.2% YoY, N=51) | Within 1km of Bashamichi Station: 48 operating properties, 12,018 rooms (planned rooms = 2.3% of operating rooms) Upper price tier: 3 (of 44 with ADR) |
| Yokohama Royal Park Hotel (reopening as a Luxury Collection hotel) Nishi-ku, Yokohama / reopening scheduled FY2028 Basis: Mitsubishi Estate et al. announcement (Mar 2025) | Not counted (603 rooms before closure) | Nishi-ku, Yokohama: ¥23,349 (+33.4% YoY, N=17) | Within 1km of Yokohama Landmark Tower: 32 operating properties, 8,886 rooms Upper price tier: 4 (of 29 with ADR) |
| HOTEL THE MITSUI HAKONE Hakone / opening December 15, 2026 Basis: Mitsui Fudosan (announced Jul 2026) | 126 rooms | Hakone: ¥25,858 (+4.7% YoY, N=186) | Within 1km of Kowakudani Station: 21 operating properties, 872 rooms (planned rooms = 14.4% of operating rooms) Upper price tier: 7 (of 17 with ADR) |
| LXR Hotels & Resorts Hakone Gora hotel project (tentative) Hakone / opening 2028 Basis: Hilton “Company Overview” | 94 rooms | Hakone: ¥25,858 (+4.7% YoY, N=186) | Within 1km of Gora Station: 41 operating properties, 1,377 rooms (planned rooms = 6.8% of operating rooms) Upper price tier: 12 (of 30 with ADR) |
Source: Compiled from company disclosures, MetroEngines Research and HotelBank Editorial Team (ADR = estimated settled ADR, tax-excluded equivalent; room stock as of November 12, 2026)
The two Yokohama projects sit in different wards. September ADR was ¥12,400 in Naka-ku, home to Conrad Yokohama (+11.2% YoY, N=51 properties), and ¥23,300 in Nishi-ku, home to Landmark Tower (+33.4% YoY, N=17). With only 17 properties, the Nishi-ku figure should be read as volatile. The 1km radius of Bashamichi Station is deep, with 48 operating properties and 12,018 rooms, of which 3 are in the upper price tier.
Hakone looks different. HOTEL THE MITSUI HAKONE (126 rooms), opening in Kowakudani on December 15, 2026, and the LXR Hotels & Resorts Hakone Gora hotel project (tentative; 94 rooms), slated for 2028 in Gora, add up to 220 rooms. Hakone’s September ADR was ¥25,900 (+4.7% YoY, N=186 properties) — the highest of all host municipalities in this article — and 12 of the 30 properties with ADR within 1km of Gora Station are in the upper price tier. This is a case of roughly 100-room blocks arriving in an area dominated by small, high-priced ryokan: 94 rooms equals 6.8% of the 1,377 operating rooms within 1km of Gora Station, a far larger presence than in the cities.
Kyoto — Regent Kyoto (83 Rooms) in Okazaki, an Area of Cultural Institutions and Residences With Few Hotel Rooms
In Kyoto, we include Regent Kyoto (83 rooms, scheduled for 2028), for which IHG announced the groundbreaking ceremony in May 2025. The site is in Okazaki, Sakyo-ku, and the hotel is being newly built on the grounds of a long-established ryotei restaurant.
| Project / location, opening | Rooms | Municipality ADR, Sep 2026 | Existing rooms within 1km (listed on major booking sites) |
|---|---|---|---|
| Regent Kyoto Sakyo-ku, Kyoto / scheduled 2028 Basis: IHG announcement (May 2025) | 83 rooms | Sakyo-ku, Kyoto: ¥13,670 (+0.6% YoY, N=15) | Within 1km of Okazaki (Higashi-Tennocho): 10 operating properties, 780 rooms (planned rooms = 10.6% of operating rooms) Upper price tier: 1 (of 4 with ADR) |
Source: Compiled from company disclosures, MetroEngines Research and HotelBank Editorial Team (ADR = estimated settled ADR, tax-excluded equivalent; room stock as of November 12, 2026)
Sakyo-ku’s September ADR was ¥13,700 (N=15 properties), essentially flat at +0.6% YoY. The 1km radius of Okazaki holds just 10 operating properties with 780 rooms — a thin concentration compared with station areas in Tokyo or Yokohama. At 10.6% of operating rooms in the radius, 83 rooms will change the area’s room mix itself once the hotel opens.
Hyogo — Conrad Kobe (136 Rooms) in 2030, on Upper Floors of Sannomiya’s City Hall Redevelopment
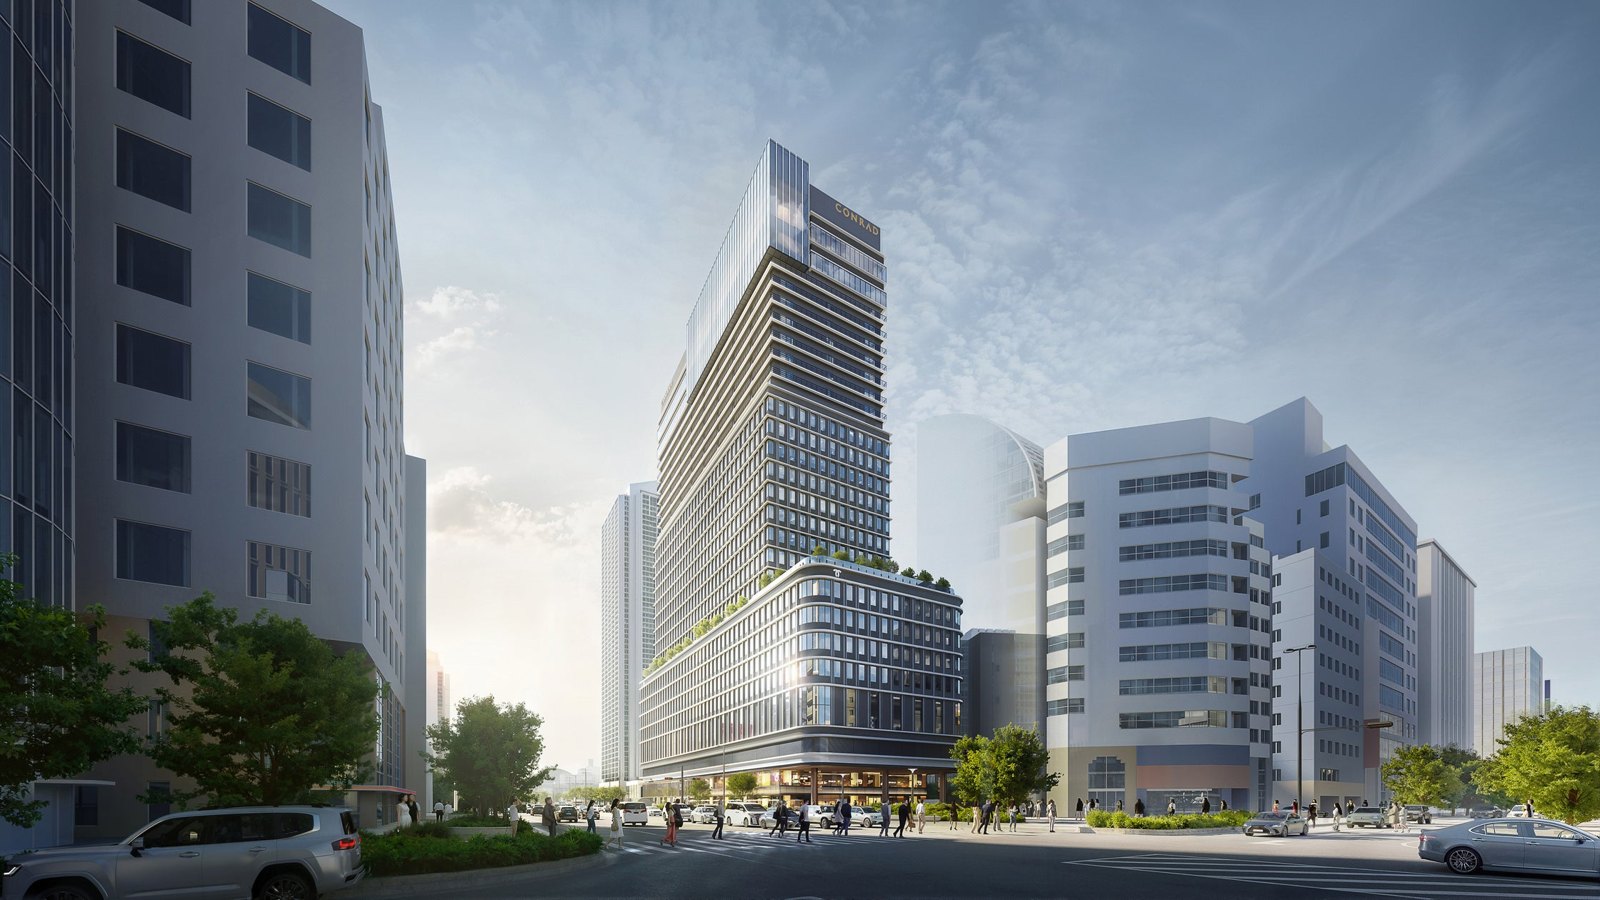
The furthest-out project on the list is Conrad Kobe (136 rooms), slated for 2030. It will occupy a mixed-use tower being built in the redevelopment of Kobe City Hall Main Building No. 2, in the heart of Sannomiya.
| Project / location, opening | Rooms | Municipality ADR, Sep 2026 | Existing rooms within 1km (listed on major booking sites) |
|---|---|---|---|
| Conrad Kobe Chuo-ku, Kobe / opening 2030 Basis: Hilton “Company Overview” | 136 rooms | Chuo-ku, Kobe: ¥12,120 (+0.2% YoY, N=64) | Within 1km of Kobe City Hall: 43 operating properties, 7,205 rooms (planned rooms = 1.9% of operating rooms) Upper price tier: 3 (of 41 with ADR) |
Source: Compiled from company disclosures, MetroEngines Research and HotelBank Editorial Team (ADR = estimated settled ADR, tax-excluded equivalent; room stock as of November 12, 2026)
Chuo-ku, Kobe posted a September ADR of ¥12,100 (N=64 properties), +0.2% YoY. The 1km radius of Kobe City Hall has 43 operating properties with 7,205 rooms, and 3 of the 41 with ADR are in the upper price tier. An international upper-tier brand joining a radius dominated by business hotels can be read as an opportunity to widen Sannomiya’s price range upward. The framework for this public-land project is examined in our analysis of Conrad Kobe’s 136 rooms and the City Hall Building No. 2 redevelopment.
Hokkaido — Park Hyatt Sapporo (157 Rooms) in 2029, in an Odori Redevelopment Tower
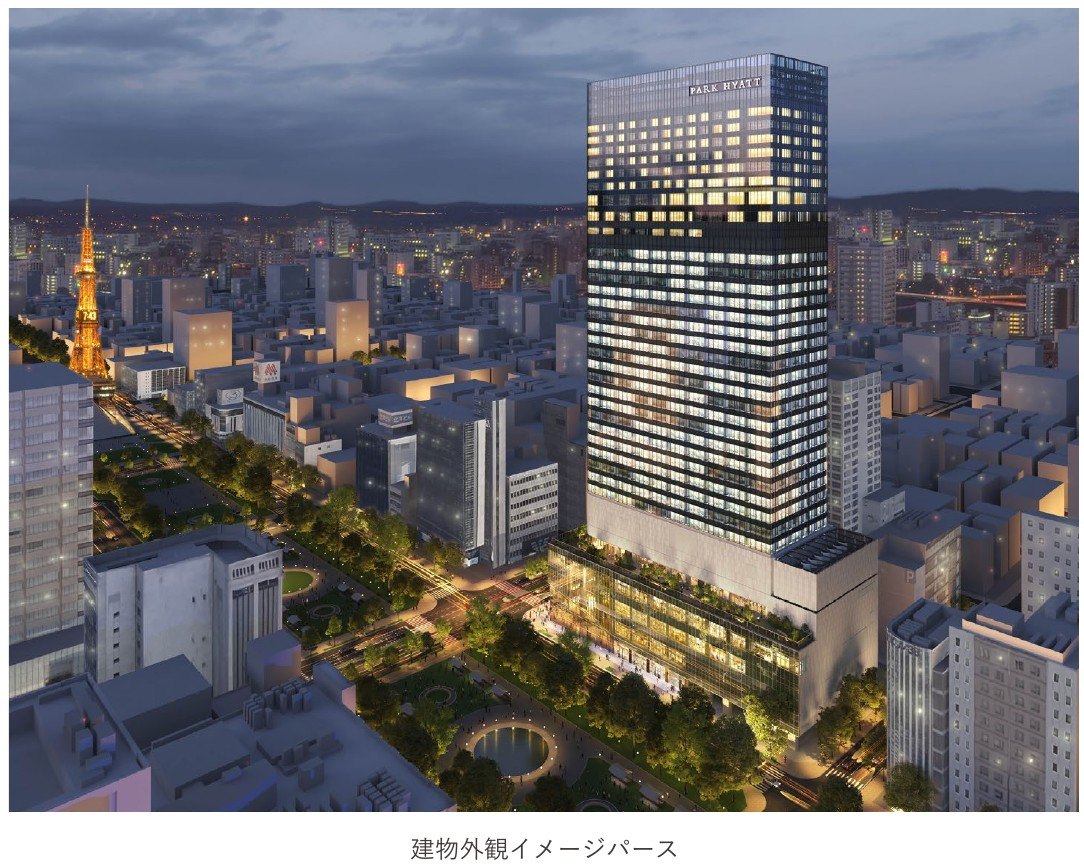
In Hokkaido, we include Park Hyatt Sapporo (157 rooms, 2029), listed in Hyatt Japan’s “Press Materials, April 2026.” The site is Odori Nishi 4-chome in Chuo-ku, Sapporo, inside a redevelopment tower.
| Project / location, opening | Rooms | Municipality ADR, Sep 2026 | Existing rooms within 1km (listed on major booking sites) |
|---|---|---|---|
| Park Hyatt Sapporo Chuo-ku, Sapporo / 2029 Basis: Hyatt Japan press materials | 157 rooms | Chuo-ku, Sapporo: ¥16,122 (+7.2% YoY, N=140) | Within 1km of Odori Station: 115 operating properties, 20,829 rooms (planned rooms = 0.8% of operating rooms) Upper price tier: 1 (of 97 with ADR) |
Source: Compiled from company disclosures, MetroEngines Research and HotelBank Editorial Team (ADR = estimated settled ADR, tax-excluded equivalent; room stock as of November 12, 2026)
Chuo-ku, Sapporo’s September ADR was ¥16,100 (+7.2% YoY, N=140 properties). The 1km radius of Odori Station is the deepest of all sites in this article at 115 operating properties and 20,829 rooms, so 157 rooms amounts to just 0.8% of operating rooms. Yet only 1 of the 97 properties with ADR is in the upper price tier, leaving the top of the price range open. This is a project that adds a new tier in price rather than in volume.
Kagawa & Hiroshima — 3 Setouchi Projects, 175 Rooms in Takamatsu, Naoshima and Miyajimaguchi
Setouchi has three projects. In Kagawa, Mandarin Oriental Setouchi’s Takamatsu (92 rooms) and Naoshima (22 rooms) properties were announced in December 2023, initially for a summer 2027 opening. A July 2026 report then said the opening would be pushed to 2028 due to design changes in light of materials prices and procurement conditions. New dates for each property have not been given, so check the latest official announcements. In Hiroshima, Umiuta Hiroshima, LXR Hotels & Resorts (61 rooms) is slated to open in Miyajimaguchi in 2028.
| Project / location, opening | Rooms | Municipality ADR, Sep 2026 | Existing rooms within 1km (listed on major booking sites) |
|---|---|---|---|
| Mandarin Oriental Setouchi – Takamatsu Takamatsu / 2028 (reportedly revised from summer 2027) Basis: developer announcement (Dec 2023), media report (Jul 2026) | 92 rooms | Takamatsu: ¥8,620 (+5.9% YoY, N=74) | Within 1km of Takamatsu Station: 25 operating properties, 2,408 rooms (planned rooms = 3.8% of operating rooms) Upper price tier: 0 (of 24 with ADR) |
| Mandarin Oriental Setouchi – Naoshima Naoshima / originally summer 2027; timing reportedly under review Basis: developer announcement (Dec 2023), media report (Jul 2026) | 22 rooms | Naoshima: not shown (reference value only, N=3) | Within 1km of Honmura, Naoshima: 2 operating properties, 25 rooms (planned rooms = 88.0% of operating rooms) Upper price tier: 1 (of 1 with ADR) |
| Umiuta Hiroshima, LXR Hotels & Resorts Hatsukaichi / opening 2028 Basis: Hilton “Company Overview” | 61 rooms | Hatsukaichi: ¥23,161 (+14.1% YoY, N=35) | Within 1km of Miyajimaguchi Station: 5 operating properties, 379 rooms (planned rooms = 16.1% of operating rooms) Upper price tier: 1 (of 4 with ADR) |
Source: Compiled from company disclosures, MetroEngines Research and HotelBank Editorial Team (ADR = estimated settled ADR, tax-excluded equivalent; room stock as of November 12, 2026)
Takamatsu’s September ADR was ¥8,600 (+5.9% YoY, N=74 properties), and none of the 24 properties with ADR within 1km of Takamatsu Station reached ¥30,000. In other words, the Takamatsu project will not join an existing upper tier but open a new price band in front of the station. Hatsukaichi’s September ADR was high at ¥23,200 (+14.1% YoY, N=35), and with only 5 operating properties and 379 rooms within 1km of Miyajimaguchi Station, 61 rooms equals 16.1% of operating rooms. Naoshima has too few properties with ADR (3) to publish a municipal figure, but the 1km radius of Honmura has just 2 operating properties with 25 rooms, so the 22-room project carries great weight relative to the island’s room base.
Okinawa — Four Seasons in Onna Village, Groundbreaking in 2024 on a Former Communications Site
In Okinawa, we include a Four Seasons resort (tentative name) planned on the former Onna Communications Site in Onna Village. At the March 2024 groundbreaking, it was reported to be targeting a 2027 opening; the developer is Malaysia’s Berjaya Group. We could not confirm the current plan’s room count in primary sources, so it is counted only in the project tally.
| Project / location, opening | Rooms | Municipality ADR, Sep 2026 | Existing rooms within 1km (listed on major booking sites) |
|---|---|---|---|
| Four Seasons Okinawa (tentative name) Onna Village / groundbreaking Mar 2024 targeting 2027 Basis: media reports at groundbreaking (Mar 2024) | Not counted | Onna Village: ¥21,895 (+9.2% YoY, N=44) | Within 1km of Onna Village Office: 3 operating properties, 65 rooms Upper price tier: 1 (of 2 with ADR) |
Source: Compiled from company disclosures, MetroEngines Research and HotelBank Editorial Team (ADR = estimated settled ADR, tax-excluded equivalent; room stock as of November 12, 2026)
Onna Village’s September ADR was ¥21,900 (+9.2% YoY, N=44 properties). Large resorts are scattered along Onna’s coastline, so the 1km radius of the village office holds only 3 operating properties with 65 rooms. The near-absence of existing rooms around the site indicates the new resort is being designed as a self-contained destination.
Site Map — Projects Cluster in Greater Tokyo and Setouchi
Source: Compiled by HotelBank Editorial Team from company disclosures (circle size = disclosed rooms; position = each site’s nearest station or block)
Undated or “2028 and Later” Projects — Niseko, Yoichi, Hakone, Kyushu
Separate from the 14 projects above, some plans have an opening date of “TBA” or “2028 or later” and no fixed room count. They are excluded from the annual totals and listed here for reference.
| Project | Location | Scale | Opening (as stated) | Basis |
|---|---|---|---|---|
| Casara Niseko Village, LXR Hotels & Resorts | Hokkaido (Niseko Village) | 8 buildings | TBA | Hilton “Company Overview” (updated Aug 25, 2026) |
| Atona Yoichi (吾汝 Atona 余市, tentative) | Hokkaido | TBA | 2028 or later | Hyatt Japan “Press Materials, April 2026” |
| Atona Hakone (tentative) | Kanagawa | TBA | 2028 or later | Same as above |
| Atona Yufu, Yakushima and Kuju (all tentative) | Kyushu | TBA | 2028 or later | Same as above |
| Third Mandarin Oriental Setouchi property | Another island in Setouchi | 50 rooms | Targeting 2030 (as of Dec 2023 announcement) | Developer announcement (Dec 2023) |
Source: Compiled by HotelBank Editorial Team from company disclosures (Hilton “Company Overview,” updated August 25, 2026; Hyatt Japan “Press Materials, April 2026”; and others)
Atona (吾汝 Atona) is a new brand that Hyatt Japan’s materials list for 2028 or later, with five tentative sites: Yoichi, Hakone, Yufu, Yakushima and Kuju (for rate levels at each site, see our rate map of Atona’s five sites). Niseko’s September ADR was ¥13,800 (N=10 properties), a subdued summer–autumn level, but rates rise sharply in winter there, so September alone does not capture the year-round picture.
Separately from the luxury tier, two IHG “Noted Collection” projects announced in September 2026 also aim at the upper price band: a 207-room conversion of an existing property in Kabukicho, Shinjuku-ku (scheduled for 2027), and an 81-room new build in Ginza 8-chome (targeting 2029). Media reports describe it as IHG’s premium brand. Shinjuku-ku’s September ADR was ¥15,100 (N=101 properties). These are not included in our 14 projects and 1,480 rooms.
Totals by Region — Tokyo, Yokohama and Hakone Hold Over 60% of High-End Rooms
By region, of the 1,480 disclosed rooms, Tokyo accounts for 437, Yokohama 272 and Hakone 220 — 929 rooms, or 62.8% of the total, across the three Greater Tokyo areas. The rest are Setouchi with 175 rooms, Sapporo 157, Kobe 136 and Kyoto 83.
| Region | Projects | Disclosed rooms (total) | Share | Projects |
|---|---|---|---|---|
| Tokyo | 3 | 437 rooms | 29.5% | Waldorf Astoria Tokyo Nihonbashi, Raffles Tokyo, Dorchester Collection hotel (name TBA) |
| Yokohama | 2 | 272 rooms (plus 1 reopening; 603 rooms before closure) | 18.4% | Conrad Yokohama, Yokohama Royal Park Hotel (reopening as a Luxury Collection hotel) |
| Hakone | 2 | 220 rooms | 14.9% | HOTEL THE MITSUI HAKONE, LXR Hotels & Resorts Hakone Gora hotel project (tentative) |
| Setouchi (Takamatsu, Naoshima, Miyajimaguchi) | 3 | 175 rooms | 11.8% | Mandarin Oriental Setouchi – Takamatsu, Mandarin Oriental Setouchi – Naoshima, Umiuta Hiroshima, LXR Hotels & Resorts |
| Kyoto | 1 | 83 rooms | 5.6% | Regent Kyoto |
| Sapporo | 1 | 157 rooms | 10.6% | Park Hyatt Sapporo |
| Kobe | 1 | 136 rooms | 9.2% | Conrad Kobe |
| Okinawa | 1 | — (rooms not counted) | — | Four Seasons Okinawa (tentative name) |
| Total | 14 | 1,480 rooms+ | 100.0% |
Source: Compiled by HotelBank Editorial Team from company disclosures (Hilton “Company Overview,” updated August 25, 2026; Hyatt Japan “Press Materials, April 2026”; and others)
Source: Compiled by HotelBank Editorial Team from company disclosures (Hilton “Company Overview,” updated August 25, 2026; Hyatt Japan “Press Materials, April 2026”; and others)
The market backdrop in each region shows in the YoY change of the host municipality’s September ADR. Growth stands out in regional areas and Yokohama — Hatsukaichi +14.1%, Naka-ku, Yokohama +11.2%, Onna Village +9.2%, Chuo-ku, Sapporo +7.2% — while Tokyo’s three wards came in slightly below last year: Chuo-ku −2.4%, Chiyoda-ku −3.5%, Minato-ku −6.6%. Heading into 2027–2028, when new upper-tier supply arrives, ward medians and the upper tier are worth tracking separately.
Source: Compiled from MetroEngines Research and HotelBank Editorial Team (estimated settled ADR for September 2026, tax-excluded equivalent; median of properties in each municipality. Naoshima not shown: 3 properties)
Changing the Counting Rules and Opening Dates — Greater Tokyo’s Share Ranges 62.8–76.8%; the Peak Year Shifts Between 2027 and 2029
The totals so far add up only the 12 projects with disclosed room counts. Below we test how far the conclusions move when the excluded projects are added and when opening dates slip.
| Yokohama Royal Park Hotel rooms after reopening | Neither included | Incl. Shinjuku 207 rooms | Incl. Ginza 81 rooms | Incl. both (288 rooms) |
|---|---|---|---|---|
| Not counted (this article’s basis) | 62.8% | 67.3% | 64.7% | 68.8% |
| 300 rooms (assumed) | 69.0% | 72.3% | 70.4% | 73.4% |
| 400 rooms (assumed) | 70.7% | 73.6% | 71.9% | 74.6% |
| 500 rooms (assumed) | 72.2% | 74.8% | 73.3% | 75.7% |
| 603 rooms (same as before closure) | 73.5% | 75.9% | 74.5% | 76.8% |
Source: Compiled by HotelBank Editorial Team from disclosed rooms in Table 10 (12 projects, 1,480 rooms, of which 929 in Greater Tokyo), Mitsubishi Estate / Mitsubishi Estate Hotels & Resorts announcement (March 31, 2025) and Travel Voice (September 28, 2026). 300–500 rooms are assumptions, not disclosed figures.
As Table 11 shows, Greater Tokyo’s share is 62.8% on this article’s basis. Assuming Yokohama Royal Park Hotel reopens with the same 603 rooms as before closure lifts it to 73.5%, and adding IHG’s two projects (288 rooms), which we treat as outside the luxury tier, brings it to 76.8%. The post-reopening room count may change with the renovation, but even at 300 rooms the share is 69.0%; under every combination, the conclusion that “Greater Tokyo holds over 60%” holds.
| Scenario | Dec 2026 | 2027 | 2028 | 2029 | 2030 | Peak year by rooms |
|---|---|---|---|---|---|---|
| As stated in materials (Table 1) | 1 / 126 rooms | 3 / 469 rooms | 8 / 592 rooms | 1 / 157 rooms | 1 / 136 rooms | 2028 (592 rooms) |
| Both Setouchi projects open in summer 2027 as originally planned | 1 / 126 rooms | 5 / 583 rooms | 6 / 478 rooms | 1 / 157 rooms | 1 / 136 rooms | 2027 (583 rooms) |
| All eight 2028 projects slip by one year | 1 / 126 rooms | 3 / 469 rooms | 0 / 0 rooms | 9 / 749 rooms | 1 / 136 rooms | 2029 (749 rooms) |
Source: Compiled by HotelBank Editorial Team from company disclosures and Nikkei (July 31, 2026). As in Table 1, project counts include the two projects whose rooms are not counted (Four Seasons Okinawa (tentative name), Yokohama Royal Park Hotel); rooms are the total of the 12 projects with disclosed counts. The slip scenario is a mechanical assumption, not a forecast.
The annual peak, meanwhile, depends on timing assumptions. Had the two Setouchi projects opened in summer 2027 as first planned, 2027 would be the peak with 5 projects and 583 rooms, and 2028 would fall to 6 projects and 478 rooms. Conversely, if all eight 2028 projects slip by a year, the peak moves to 2029 with 9 projects and 749 rooms. The Dorchester Collection hotel and Yokohama Royal Park Hotel are stated as “FY2028,” which on a calendar basis could extend into January–March 2029. The 2028 concentration should therefore be read as a picture based on current wording, with a margin of one year either side of each opening.
What It Means for Existing Operators — More Upper-Tier Reference Points Create Opportunity
So how can properties operating near these sites use this list? First, since new projects amount to only a few percent of existing operating rooms in most radii, the effect to watch is less the change in supply than the lifting of the area’s price ceiling. More upper-tier reference points create room to revisit pricing for existing properties’ top categories, such as suites and high-floor rooms.
Second, in places with thin room stock — Hakone, Okazaki, Miyajimaguchi, Naoshima — new projects may raise the drawing power of the entire area through referrals and awareness. Preparing plans that showcase a property’s strengths, such as onsen, cuisine or location, around the opening period can be effective. Third, opening dates can move, so rather than treating them as fixed, it is worth checking developers’ announcements every six months and updating pricing and sales plans accordingly. For long-term occupancy trends, the Japan Tourism Agency’s “Overnight Travel Statistics Survey” and the Japan National Tourism Organization (JNTO) visitor arrival statistics are the baseline references.
Frequently Asked Questions
Q. Which luxury hotels are scheduled to open in 2027?
A. Within what we could confirm, Waldorf Astoria Tokyo Nihonbashi (197 rooms) and Conrad Yokohama (272 rooms) are scheduled for 2027, and the Four Seasons in Onna Village (tentative name) broke ground targeting a 2027 opening.
Q. Why are there so many projects in 2028?
A. Raffles Tokyo, the Dorchester Collection hotel, the LXR properties in Hakone Gora and Miyajimaguchi, and Regent Kyoto coincide with the Yokohama Royal Park Hotel reopening and the two Setouchi projects whose timing was reportedly revised, bringing the total to eight.
Q. Is there a clear definition of an “ultra-luxury hotel”?
A. There is no unified standard; the term is used for hotels positioned at the top of each company’s brand hierarchy. This article covers projects under brands that the companies themselves position as luxury.
Q. Where are planned rooms large relative to existing rooms nearby?
A. Measured as planned rooms over operating rooms within 1km, the highest ratios are Honmura, Naoshima at 88.0% (22/25 rooms), Miyajimaguchi Station at 16.1%, Kowakudani Station at 14.4% and Okazaki at 10.6%. City station areas stay at 1–2%, such as Odori Station at 0.8% and Tokyo Station Nihonbashi Exit at 1.1% (as of November 12, 2026).
Q. Why is the host municipality’s ADR lower than luxury hotel rates?
A. Municipality ADR is the median estimated settled rate of covered properties and reflects the area’s typical level, which includes many business hotels. The relationship with luxury pricing is shown separately as the number of properties within 1km with an estimated settled ADR of ¥30,000+ in September 2026 (upper price tier).
Summary
Japan has 14 major luxury hotels scheduled to open from late 2026 to 2030, with 1,480 disclosed rooms. By year, 2028 gathers 8 projects and 592 rooms; by region, Tokyo, Yokohama and Hakone hold 62.8%. September ADR in host municipalities ranges from ¥25,900 in Hakone to ¥8,600 in Takamatsu, and upper-price-tier properties within 1km range from 12 around Gora Station to zero around Takamatsu Station. Under the same “luxury hotel pipeline” label, projects that join an existing high-price tier and projects that open a new price band carry different implications for the surrounding market. Timing may continue to shift, so this list should be reread as public materials are updated.
Related Articles
Further Reading
- Yokohama Royal Park Reopens 2028 as Luxury Collection: 603-Room Math
- Conrad Yokohama 272 Rooms: Luxury Tier Above a ¥33,300 ADR Ceiling
- Conrad Kobe on Public Land: Leasehold Cuts Required ADR Only ¥3,100
- Hyatt Atona’s 5 Sites by ADR: Hakone ¥26k to Yakushima ¥12k, 2028+
- Hakone Gora Ryokan Appraised at ¥390mn a Room: REIT Equity, 184 Keys
- 15 Foreign-Brand Hotels, 2,709 Rooms: Japan’s 2026-2031 Pipeline
- 34 Hotels, 5,028 Rooms Opening in Japan 2027: Full Pipeline List
References and Sources
■ Data sources
The project list is limited to those whose brand, location, opening timing and room count could be confirmed in company disclosures (Hilton “Company Overview,” updated August 25, 2026; Hyatt Japan “Press Materials, April 2026”; developer announcements) and major media reports (as of November 2026). Municipality ADR is MetroEngines Research’s estimated settled ADR (September 2026, tax-excluded equivalent; median of covered properties in each municipality, N=10–186). Room stock within 1km is as of November 12, 2026 (properties with 10+ rooms, excluding leisure/love hotels; “operating” = selling prices observed on major booking sites in the last three months).
■ Calculation assumptions
Room totals are a simple sum of the 12 projects with disclosed counts; shares are regional rooms ÷ 1,480. “Planned rooms = X% of operating rooms” is planned rooms ÷ operating rooms within 1km. Upper price tier = operating properties in the radius with estimated settled ADR of ¥30,000+ in September 2026. Table 11 tests Yokohama Royal Park Hotel’s post-reopening rooms (300–500 rooms are assumptions) and inclusion of IHG’s two “Noted Collection” projects; Table 12 mechanically shifts opening dates. Both are sensitivity/scenario analyses, not forecasts.
■ Limitations
The 14 projects are those we could confirm from public materials, not a census of every project in Japan. Opening dates follow each company’s wording and are not confirmed dates. Room counts for Four Seasons Okinawa (tentative name) and Yokohama Royal Park Hotel are not included in totals. Naoshima’s municipal ADR is not shown (3 properties), and Niseko (N=10), Sakyo-ku, Kyoto (N=15) and Nishi-ku, Yokohama (N=17) have small samples and are volatile. Municipality ADR is a median and does not indicate luxury-tier rate levels; the 1km radius is an approximation centered on the nearest station or block.
■ References
Source: Hilton “Company Overview” (updated August 25, 2026)
Source: Hyatt Japan Co., Ltd. “Press Materials, April 2026”