


According to MetroEngines Research, which counts openings from the date a property first appears on the major booking sites, 67 hotels and other lodging properties with 1,284 rooms opened in Hyogo Prefecture in 2026 (including openings scheduled through December). Checking the largest of them one by one against each company’s announcements, however, shows that the biggest, the 381-room Courtyard by Marriott Kobe on Port Island, is a rebrand of Hotel Pearl City Kobe, and that THE ORIENT (116 rooms) in the former foreign settlement is the former Oriental Hotel, opened in 2010, under a new name. Excluding these two properties and their 497 rooms, net new supply is 65 properties and 787 rooms, and just over half of that comes from two Route Inn hotels with 419 rooms, opened in front of Shin-Sanda Station and at the Hikami IC. This article separates rebrands from net new supply, then layers the supply added at suburban station-front and interchange sites, the vacation rentals concentrated on Awaji Island, and estimated settled ADR by municipality, and estimates the room rate a newly built 200-room roadside hotel would need.
• ADR (average daily rate) = estimated settled rate (tax-excluded equivalent), calculated by applying segment-specific adjustment factors to the lowest-priced plan each property publishes on OTAs (per-room rate for two adults sharing one room, tax included). Checked against property-level results disclosed by listed hotel REITs (91 properties, most recent three months), the median error is about 7%. These are estimates and differ from each property’s actual transaction prices and accounting figures.
• ADR for an area (prefecture or municipality) is the median of the estimated settled rates of the properties covered (the level of a typical property in the area).
• Wherever listed prices are mentioned, they are per-room rates for two adults sharing one room (tax included).
• OCC (occupancy) = rooms sold as a share of total rooms in the area (an estimate based on OTA sales inventory).
• Source: MetroEngines Research (continuous tracking of OTA public prices for approx. 168,000 properties, of which approx. 27,000 are confirmed to be operating)
Room stock for Port Island covers lodging properties with 10 or more rooms (excluding leisure/love hotels) within a 2,000m radius of Port Island (Naka-Futo Station); “operating” means a selling price was observed on the major booking sites in the most recent three months (September–November 2026) (as of November 10, 2026, compiled by MetroEngines Research).
Room stock for Shin-Sanda covers lodging properties with 10 or more rooms (excluding leisure/love hotels) within a 3,000m radius of JR Shin-Sanda Station; “operating” is defined the same way (September–November 2026; as of November 10, 2026, compiled by MetroEngines Research).
Room stock for Hikami covers lodging properties with 10 or more rooms (excluding leisure/love hotels) within a 5,000m radius of the Hikami IC; “operating” is defined the same way (September–November 2026; as of November 10, 2026, compiled by MetroEngines Research).
Key Takeaways
— 497 of the 1,284 rooms are rebrands: Courtyard by Marriott Kobe (381 rooms, formerly Hotel Pearl City Kobe) and THE ORIENT (116 rooms, formerly the Oriental Hotel) are existing buildings and add nothing to the prefecture’s room stock. Net new supply is 65 properties and 787 rooms.
— 60% of net new supply is in suburban Sanda and Tamba: Route Inn Shin-Sanda Ekimae (231 rooms), Route Inn Hikami Inter (188 rooms) and HOTEL R9 The Yard Tamba (56 rooms) add 475 rooms, 60.4% of the net increase. Rooms within 3km of Shin-Sanda Station rose from 188 to 419, and 244 of the 423 operating rooms within 5km of the Hikami IC opened in 2026.
— Awaji Island vacation rentals dominate the property count: 45 of the 67 openings are vacation rentals, but they total only 58 rooms. Awaji Island’s three cities saw 47 openings with 156 rooms, and the number of properties with observed prices rose from 327 to 421 in one year.
— New suburban rooms are selling above their city’s level: In October 2026, the two Route Inn hotels posted estimated settled ADRs of ¥8,231 and ¥9,393, above the medians for Sanda (¥7,516) and Tamba (¥5,945).
— Construction cost decides the next building: For 200 rooms at 75% occupancy, a 50% GOP margin and a 7% yield, the required ADR is ¥7,200–7,500 at the 2024 steel-frame unit cost of ¥1.648 million per tsubo, and ¥10,300–10,700 at the 2025 cost of ¥2.410 million per tsubo.
The 67 Openings and 1,284 Rooms — 381 and 116 Rooms Are Rebrands of Existing Buildings
Start with the overall picture of what opened in Hyogo in 2026. Counting from first listing on the major booking sites, MetroEngines Research recorded 67 openings with 1,284 rooms as of November 9, 2026. Of these, 12 properties with 1,181 rooms have 10 or more rooms each, and it is fair to say that these 12 are what actually moves the prefecture’s room supply.
Checking the largest of them against each company’s announcements, though, shows they are quite different in nature. Courtyard by Marriott Kobe (コートヤード・バイ・マリオット神戸, 381 rooms) on Port Island is Hotel Pearl City Kobe, fully renovated and reopened on Thursday, October 1 by HMI Hotel Group under its strategic partnership with Marriott International. It follows the group’s reopening of the former Hotel Crown Palais Kobe as Kobe Marriott Hotel in December 2025. THE ORIENT (116 rooms) in the former foreign settlement is the Oriental Hotel, operated by Plan・Do・See since 2010, which changed its name on Sunday, February 1 when its trademark license agreement ended, and resumed operations on February 12 after interior work. In both cases the rooms are in the existing buildings, so the prefecture’s room stock did not grow.
Meanwhile, the properties confirmed as new builds are centered in the suburbs. Route Inn Japan’s Hotel Route-Inn Tamba -Hikami Inter- (ホテルルートイン丹波-氷上インター-, 188 rooms) opened on Thursday, July 9 as the company’s sixth hotel in Hyogo, about a one-minute drive from the Hikami IC on the Kita-Kinki Toyooka Expressway. Hotel Route-Inn Kobe Sanda -Shin-Sanda Ekimae- (ホテルルートイン神戸三田-新三田駅前-, 231 rooms) opened on Monday, September 14 as its seventh in the prefecture, a station-front site about a one-minute walk from JR Shin-Sanda Station. In December 2024 the Kobe Shimbun reported that the company would begin construction of a roughly 234-room hotel in front of Shin-Sanda Station in February 2025. In addition, Develop’s container-type HOTEL R9 The Yard Tamba (56 rooms) opened on Thursday, February 5 on National Route 175, about a three-minute drive from the Hikami IC. In Sannomiya, BASE LAYER HOTEL KOBE SANNOMIYA (82 rooms) opened on Nakayamate-dori on Tuesday, November 10.
| Property | Location | Rooms | Opened | Nature of supply |
|---|---|---|---|---|
| Courtyard by Marriott Kobe | Kobe, Chuo-ku (Port Island) | 381 | Oct 1 | Rebrand (fully renovated former Hotel Pearl City Kobe) |
| Hotel Route-Inn Kobe Sanda -Shin-Sanda Ekimae- | Sanda | 231 | Sep 14 | New build (approx. 1 min walk from JR Shin-Sanda Station) |
| Hotel Route-Inn Tamba -Hikami Inter- | Tamba (Hikami-cho) | 188 | Jul 9 | New build (approx. 1 min drive from Hikami IC) |
| THE ORIENT | Kobe, Chuo-ku (former foreign settlement) | 116 | Feb 1 | Name change (former Oriental Hotel, opened 2010) |
| BASE LAYER HOTEL KOBE SANNOMIYA | Kobe, Chuo-ku (Nakayamate-dori) | 82 | Nov 10 | New opening |
| THE PASONA natureverse retreat | Awaji (Iwaya) | 57 | June | New opening (long-stay retreat) |
| HOTEL R9 The Yard Tamba | Tamba (Hikami-cho) | 56 | Feb 5 | New build (container type, approx. 3 min drive from Hikami IC) |
| Rakuten STAY TERRACE Kinosaki Riverside | Toyooka (Kinosaki-cho) | 24 | Jul 23 | New opening (all rooms face the Maruyama River, 4 stories) |
| BE WANDERLUST HOTEL Awajishima | Minamiawaji | 14 | December (planned) | New opening planned |
| 3 other properties with 10+ rooms | Toyooka, Himeji, Takarazuka | 32 | — | Minshuku, small hotel, campground |
| 55 properties with fewer than 10 rooms | Mainly Awaji Island’s three cities | 103 | — | Includes 45 vacation rentals |
Set against openings by year, 2026’s 1,284 rooms are the most since 2022. Excluding the 497 rebranded rooms, however, net new supply is 787 rooms, not very different from 2025 (845 rooms, of which Kobe Marriott Hotel’s 186 rooms were a rebrand) or 2022 (1,134 rooms). The prefecture’s supply has not grown as much as the headline figure suggests; the more reasonable reading is that where supply is being added has shifted from central Kobe to the suburbs.
By Segment — Vacation Rentals Are 67% of Openings; City and Business Hotels Are 83% of Rooms
By segment, the picture for property count and room count is almost reversed. Of the 67 openings, 45 (67.2%) are vacation rentals, but they total just 58 rooms, only 4.5% of the total. Conversely, 3 city hotels with 579 rooms (45.1%) and 4 business hotels with 485 rooms (37.8%) together account for 82.9% of rooms from just seven properties. An “opening rush” measured by property count and the supply impact measured by rooms need to be treated as separate things.
The vacation rentals are clustered on Awaji Island: 27 properties with 104 rooms in Awaji City, 13 with 27 rooms in Sumoto and 7 with 25 rooms in Minamiawaji, bringing openings in Awaji Island’s three cities to 47 properties and 156 rooms, or 70.1% of all openings in the prefecture by count. Awaji City’s 104 rooms include the Pasona Group’s long-stay retreat (57 rooms). The number of properties on Awaji Island with observed listed prices grew by 94 in one year, from 327 in October 2025 to 421 in October 2026. Single-unit properties are small on their own, but they are steadily pushing up the island’s lodging capacity. Note that estimated settled ADR covers only validated segments (business, city, resort, ryokan and capsule), so vacation rental price levels are not included in the municipal ADRs in this article.
By Municipality — 60% of Net New Supply Is in Sanda and Tamba; Central Kobe Is Mostly Rebrands
Splitting each municipality’s openings into net new and rebranded rooms makes the center of gravity of supply clear. Kobe’s Chuo-ku, the largest by rooms (3 properties, 579 rooms), had 497 rebranded rooms, leaving net new supply at just BASE LAYER’s 82 rooms. By contrast, everything in Tamba (2 properties, 244 rooms) and Sanda (1 property, 231 rooms) is new build, and the two cities’ 475 rooms make up 60.4% of the prefecture’s 787 net new rooms. Awaji Island’s three cities follow with 156 rooms (19.8%), then Toyooka (37 rooms), Himeji (13 rooms) and Takarazuka (10 rooms).
| Rooms within 3km (operating) | 3 properties, 419 rooms |
| Of which opened in 2026 | 231 rooms |
| Zoning (representative point) | Neighborhood commercial |
| Benchmark land price, Sanda 5-1 (commercial) | ¥79,500/㎡ (+1.9%) |
| Rooms within 5km (operating) | 8 properties, 423 rooms |
| Of which opened in 2026 | 244 rooms |
| Zoning (representative point) | Not designated |
| Benchmark land price, Tamba 5-4 (commercial) | ¥44,600/㎡ (+0.5%) |
| Rooms within 2km (operating) | 4 properties, 1,315 rooms |
| Zoning (representative point) | Commercial |
| Floor area ratio / building coverage | 400% / 80% |
Suburban Station-Front and Interchange Sites — Rooms Within 3km of Shin-Sanda Up 2.2x; 60% of Rooms Near the Hikami IC Are New
Sanda and Tamba, the pillars of net new supply, both had large blocks of new rooms land where existing room stock was thin. Within a 3km radius of Shin-Sanda Station, the properties with selling prices observed in the most recent three months total 3 properties and 419 rooms; excluding the Route Inn that opened in 2026, the existing stock was 2 properties with 188 rooms. One building added 231 rooms, 1.2 times the existing stock, meaning rooms within the radius rose 2.2-fold. The company’s opening release cited not only business demand but also nearby leisure demand such as Kobe-Sanda Premium Outlets.
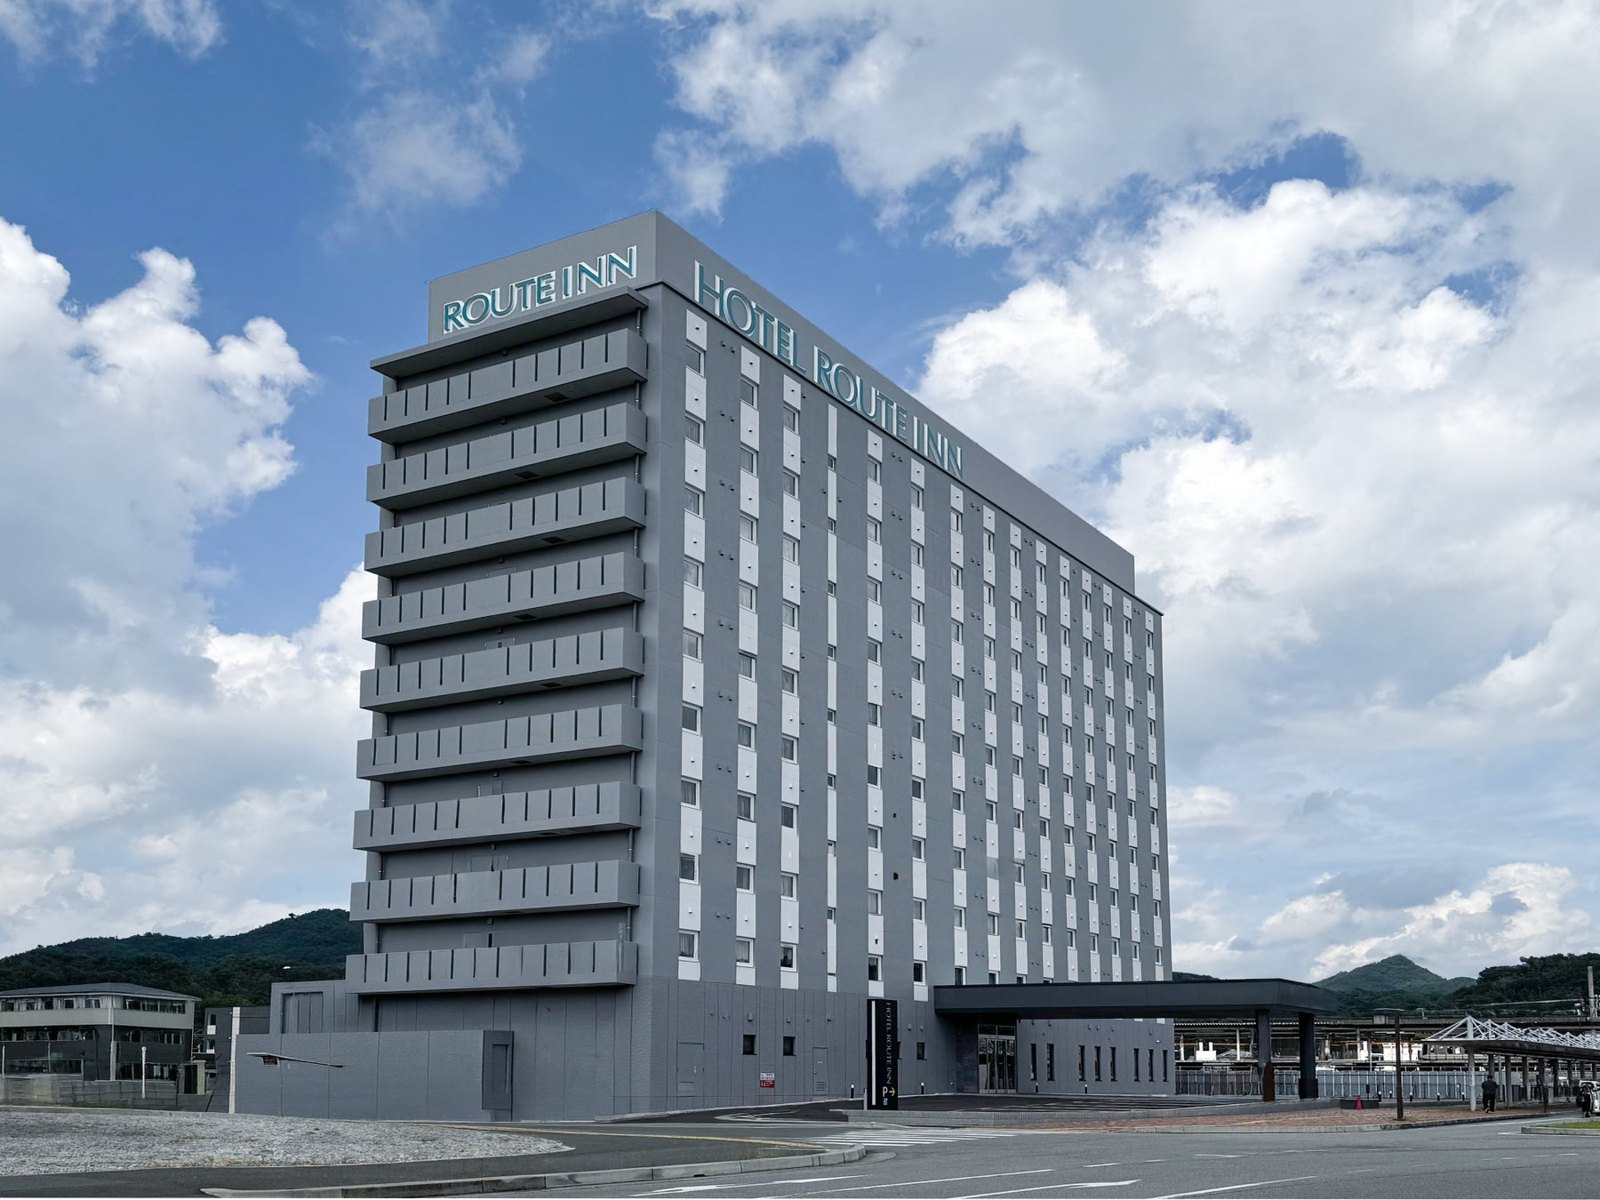
The area around the Hikami IC is even more concentrated. Within a 5km radius, operating properties total 8 with 423 rooms, of which the Route Inn’s 188 rooms and R9’s 56 rooms, 244 rooms in all (57.7%), opened in 2026. R9’s opening release noted that many factories, including the Hikami Industrial Park, are located within about a 10-minute drive, and it targets business trips and long stays. A site close to an interchange on the Kita-Kinki Toyooka Expressway can capture both weekday demand from factories and construction and weekend leisure demand heading to Kinosaki and the Tajima area, which suits the roadside development model well. We lay out the site requirements for this type of hotel in Route Inn’s site criteria (approx. 3,800㎡ site, 200 rooms).
In terms of site assessment, land prices in both areas are low, which keeps land acquisition costs light. In the 2026 prefectural land price survey (as of July 1), a commercial site 710m from Shin-Sanda Station (Sanda 5-1) was ¥79,500 per ㎡, up 1.9% YoY, and a commercial site in Hongo, Hikami-cho (Tamba 5-4) was ¥44,600, up 0.5%. On the other hand, the representative points for both the Shin-Sanda Station front and the Hikami IC area fall within flood inundation zones (maximum assumed scale) for rivers managed by Hyogo Prefecture, with an inundation depth rank of 0.5m to under 3.0m. In lending and insurance reviews, BCP specifications such as placing substations and emergency generators on upper floors and flood barriers on the ground floor are likely to be checkpoints. The assessment is a simplified one based on each property’s representative coordinates and does not reflect building layout or site ground elevation.
Estimated Settled ADR by Municipality — Sanda and Himeji Up About 7% YoY; Southern Awaji Below Last Year
We compare rates in the municipalities where new rooms were added, for October 2026 (a finalized month) against the same month a year earlier. Hyogo’s overall estimated settled ADR was ¥13,772 (N=554), up 3.3% from ¥13,326 a year earlier (the rate structure across the prefecture’s areas is set out in Hyogo’s Hotel Market in 5 Layers 2026). Cities driven by business demand rose: Sanda to ¥7,516 (+6.7%) and Himeji to ¥7,647 (+6.9%). On the other hand, southern Awaji Island’s Sumoto (¥17,135, −16.8%) and Minamiawaji (¥19,574, −7.5%) came in below the prior year, while Awaji City was ¥15,569 (+3.4%). Kobe’s Chuo-ku was ¥14,008 (−2.6%), a level reached as the number of properties with observed prices rose from 72 to 85.
Next, we set the estimated settled ADR of the main 2026 openings against the median of their municipality. The two suburban hotels are selling above their city’s level. In October 2026, Route Inn Shin-Sanda Ekimae posted ¥8,231, 9.5% above Sanda’s median (¥7,516), and Route Inn Tamba -Hikami Inter- posted ¥9,393, 1.58 times Tamba’s median (¥5,945). This suggests that a standardized product with a large public bath and breakfast is creating a new price band distinct from existing small hotels and ryokan. Courtyard Kobe on Port Island posted ¥10,134 in October, its opening month, positioned in the ¥10,000 band below Kobe Chuo-ku’s median (¥14,008) and serving a different price band from central Sannomiya. THE ORIENT in the former foreign settlement posted ¥48,332, at the top tier of urban hotels in the prefecture.
Comparison With Neighboring Prefectures — Second Only to Osaka in Rooms Opened, but Below Kyoto and Okayama Excluding Rebrands
Placing Hyogo’s figures alongside neighboring prefectures makes its position easier to see. Measured the same way, rooms opened in 2026 are led by Osaka at 3,568, followed by Hyogo at 1,284, Kyoto (1,166) and Okayama (1,029). Excluding its 497 rebranded rooms, however, Hyogo’s net new supply is 787 rooms, below the listing-based figures for Kyoto and Okayama, where rebrands have not been separated out. Hyogo averages 19.2 rooms per opening, unlike Osaka (64.9) and Okayama (46.8), which are driven by large projects, or Kyoto (11.8) and Nara (11.8), which are driven by small properties; it combines large suburban business hotels with Awaji Island vacation rentals.
In rate growth, Hyogo’s +3.3% YoY sits in the middle of the region. Okayama (+15.1%), Tokushima (+9.7%), Tottori (+9.2%) and Kyoto (+6.9%) outpaced Hyogo, and Nara (+3.2%) was about the same. Osaka’s −21.0% appears to be a reaction to the comparison month, October 2025, which included the end of Expo 2025 Osaka, Kansai (closed October 13). Hyogo has kept its prefecture-wide rate above the prior year even while stacking large blocks of net new rooms in the suburbs, and has not yet entered a phase where added supply pushes rates down.
| Prefecture | Openings | Rooms | Rooms per opening | Of which 10+ rooms | Est. settled ADR | YoY | N |
|---|---|---|---|---|---|---|---|
| Hyogo | 67 | 1,284 | 19.2 | 12 / 1,181 rooms | ¥13,772 | +3.3% | 554 |
| Osaka | 55 | 3,568 | 64.9 | 38 / 3,523 rooms | ¥10,580 | −21.0% | 661 |
| Kyoto | 99 | 1,166 | 11.8 | 19 / 1,034 rooms | ¥20,564 | +6.9% | 602 |
| Okayama | 22 | 1,029 | 46.8 | 7 / 1,009 rooms | ¥9,489 | +15.1% | 192 |
| Tokushima | 16 | 346 | 21.6 | 5 / 323 rooms | ¥6,417 | +9.7% | 139 |
| Tottori | 7 | 297 | 42.4 | 3 / 288 rooms | ¥9,042 | +9.2% | 154 |
| Nara | 18 | 212 | 11.8 | 5 / 169 rooms | ¥14,469 | +3.2% | 135 |
| Shiga | 16 | 137 | 8.6 | 3 / 105 rooms | ¥8,290 | −8.0% | 158 |
| Wakayama | 20 | 60 | 3.0 | 1 / 20 rooms | ¥8,929 | +0.7% | 218 |
Central Kobe — 2026 Was a Reshuffle of Existing Buildings; the New-Build Wave Comes From 2027
In central Kobe, 2026 was a year of reshuffling existing buildings rather than building new ones. Within a 2km radius of Naka-Futo Station on Port Island, properties with selling prices observed in the most recent three months total 4 with 1,315 rooms, and Courtyard Kobe’s 381 rooms are in the same building as the former Hotel Pearl City Kobe. Room stock within the radius is unchanged; what changed is the brand and price band. How far rates move after a rebrand is something we have measured separately across 33 properties. The new build in Sannomiya is BASE LAYER’s 82 rooms; for details, see our article on the opening of BASE LAYER HOTEL Kobe Sannomiya.
The new-build wave arrives from 2027. MLIT’s Building Activity Statistics Survey lists a 223-room hotel on Onoedori in Kobe’s Chuo-ku (completion scheduled for July 2027) and a hotel on the upper floors of the Kumoidori 5-chome Redevelopment Phase I building (32 stories, completion scheduled for December 2027), which includes the Sannomiya Bus Terminal. The latter was originally reported as “EVOL HOTEL KOBE,” to open within FY2027, but a July 2026 report said TRUNK, part of the Take and Give Needs Group, plans to open it as “TRUNK(HOTEL) KOBE” in 2028. Also announced are a 755-room APA Hotel north of Sannomiya Station (opening planned for spring 2029; see APA 755 Rooms in Kobe Sannomiya, 2029) and the 93-room Noir by RIHGA Kobe Arima in Arima Onsen (opening planned for around the end of February 2028; see Noir by RIHGA Kobe Arima). Central Kobe, where the 2026 rebrands widened the choice of brands, is expected to add large new-build projects one after another in 2027–2029.
Development Scenario — For a 200-Room Roadside Hotel, Construction Cost Moves the Required ADR From the ¥7,000s to the ¥10,000s
For developers and lenders considering the next building at a suburban station-front or interchange site, we ran a simplified estimate of the required ADR for a 200-room roadside business hotel built near Shin-Sanda Station or in Hikami-cho. Assumptions: a 3,800㎡ site, 5,300㎡ gross floor area (approx. 1,603 tsubo, 26.5㎡ per room), steel frame, 75% annual occupancy, a 50% GOP margin (our assumption; Relo Hotel Solutions puts the general industry benchmark for GOP margin at around 30–40%, and Table 7 also shows a 45% GOP margin case), and a 7% target yield. Land is priced at the commercial land prices from the land price survey above, and construction cost is set at three levels.
| Construction cost assumption | Shin-Sanda area: total investment | Shin-Sanda: required ADR | Hikami-cho: total investment | Hikami-cho: required ADR |
|---|---|---|---|---|
| 2024 steel-frame actual, ¥1.648M/tsubo | ¥2.94bn | ¥7,529 | ¥2.81bn | ¥7,190 |
| 2025 steel-frame actual, ¥2.410M/tsubo Base | ¥4.17bn | ¥10,653 | ¥4.03bn | ¥10,313 |
| 2025 actual + inflation during construction (¥2.601M/tsubo) | ¥4.47bn | ¥11,436 | ¥4.34bn | ¥11,097 |
The estimate shows that construction cost determines feasibility. At the 2024 steel-frame unit cost, the required ADR is ¥7,200–7,500, so a 7% yield is reachable at Sanda’s median (¥7,516) or at the ¥8,000–9,000 range that the suburban hotels opened in 2026 are achieving. At the 2025 steel-frame cost of ¥2.410 million per tsubo, by contrast, the required ADR exceeds ¥10,000, and allowing for increases during construction pushes it into the ¥11,000s. The difference in land prices amounts to only about ¥130 million in total investment; the gap in construction cost matters far more than the gap between locations.
| Sensitivity (Shin-Sanda area) | ¥1.648M/tsubo | ¥2.410M/tsubo | ¥2.601M/tsubo |
|---|---|---|---|
| Base (75% occupancy, 50% GOP margin) | ¥7,529 | ¥10,653 | ¥11,436 |
| Occupancy −5pt (70%) | ¥8,066 | ¥11,414 | ¥12,253 |
| GOP margin −5pt (45%) | ¥8,365 | ¥11,836 | ¥12,707 |
| Both | ¥8,963 | ¥12,682 | ¥13,615 |
Conversely, Table 8 shows yield based on achievable rates and occupancy. Assuming the 2025 construction cost (total investment ¥4.17bn), the ¥8,231 and ¥9,393 that the two suburban Route Inn hotels achieved in October 2026 yield only 5.8% and 6.6% even at 80% occupancy. Reaching 7% requires 80% occupancy or higher at a ¥10,000 ADR, or 75% or higher at ¥11,000.
| ADR \ Occupancy | 65% | 70% | 75% | 80% | 85% |
|---|---|---|---|---|---|
| ¥8,000 | 4.6% | 4.9% | 5.3% | 5.6% | 6.0% |
| ¥9,000 | 5.1% | 5.5% | 5.9% | 6.3% | 6.7% |
| ¥10,000 | 5.7% | 6.1% | 6.6% | 7.0% | 7.4% |
| ¥11,000 | 6.3% | 6.7% | 7.2% | 7.7% | 8.2% |
| ¥12,000 | 6.8% | 7.4% | 7.9% | 8.4% | 8.9% |
Rising construction costs raise the break-even line for new entrants, but for existing properties and those that opened earlier they act as a brake on additional competitors. Operators that can hold down construction costs through standard designs and bulk ordering, and formats like R9 that compress construction time and cost with container modules, still have investment opportunities at suburban station-front and interchange sites.
Saturated Central Kobe reshuffle
497 of Chuo-ku’s 579 rooms are rebrands
2026 was a swap of brands and price bands. Large new-build projects arrive in sequence in 2027–2029.
Opportunity 1 Suburban station-front & IC sites
475 rooms in Sanda and Tamba, priced above city levels
Thin existing stock and low land prices. Feasibility depends on keeping construction cost within a required ADR in the ¥7,000s.
Opportunity 2 Small-unit supply on Awaji Island
47 properties, 156 rooms; tracked properties +94 in a year
Single-unit vacation rentals are pushing up the count. Mid-sized stay-type properties are limited, leaving room to grow for long stays.
Summary
Hyogo’s 67 openings and 1,284 rooms in 2026 split into two rebrands with 497 rooms and 65 net new properties with 787 rooms. Central Kobe was mainly a reshuffle of existing buildings through Courtyard by Marriott Kobe and THE ORIENT, while 60% of net new supply was the 475 rooms of the two Route Inn hotels at the Shin-Sanda Station front and the Hikami IC, plus R9. Rooms within 3km of Shin-Sanda Station rose 2.2-fold, and 57.7% of operating rooms within 5km of the Hikami IC opened in 2026; yet the October 2026 estimated settled ADRs of these hotels were all above their city medians, so new suburban rooms are creating a price band separate from existing stock. When considering the next building, judge it on construction cost and the reliability of weekday demand rather than on land price. At 2024-level construction costs, the required ADR is in the ¥7,000s, within today’s rate band; at 2025 levels, the ¥10,000s are needed. On Awaji Island, vacation rentals are pushing up the property count, and there is still room for mid-sized stay-type properties.
Frequently Asked Questions
Q. How many hotels and rooms opened in Hyogo Prefecture in 2026?
A. Counting from first listing on the major booking sites, MetroEngines Research recorded 67 properties with 1,284 rooms (including openings scheduled through December, as of November 9, 2026). Of these, 45 are vacation rentals, and properties with 10 or more rooms total 12 with 1,181 rooms.
Q. Is Courtyard by Marriott Kobe a new build?
A. No. HMI Hotel Group fully renovated Hotel Pearl City Kobe (381 rooms) and reopened it under the Courtyard by Marriott Kobe brand on October 1, 2026. THE ORIENT (116 rooms) in the former foreign settlement is likewise the former Oriental Hotel, renamed on February 1.
Q. Where did Hyogo’s net new rooms in 2026 come from?
A. Of the 787 net new rooms excluding 497 rebranded rooms, Sanda (231 rooms) and Tamba (244 rooms) together account for 475 rooms, or 60.4%. Awaji Island’s three cities added 47 properties with 156 rooms, and net new supply in Kobe’s Chuo-ku is BASE LAYER HOTEL KOBE SANNOMIYA’s 82 rooms.
Notes on the data: Opening data is based on OTA listing confirmation, using the date a property first appeared on the major booking sites as its opening date. Because listings appear several months before opening, openings in November–December 2026 may increase as further listings appear. Estimated settled ADR by municipality uses only finalized months (October 2026 and earlier) and does not use estimates for future months based on current listings. Flood inundation zone assessments are simplified, based on each property’s representative coordinates (assessed November 10, 2026).
Related Articles
- Hyogo’s Hotel Market in 5 Layers 2026: ADR from ¥10,700 to ¥29,600
- Route Inn Site Criteria: 3,800㎡, 200 Rooms, No Rival Within 1km
- Kagawa Hotel Openings 2026: Only 316 of 686 Rooms Are Net New
- Ehime Hotel Investment Map 2026: Matsuyama ADR ¥10,100, 439 Net New Rooms
- APA 755 Rooms in Kobe Sannomiya, 2029: +13.9% Supply, ADR ¥12,100
- Noir by RIHGA Kobe Arima: 93 Rooms Enter a 49-Inn, 1,740-Room Onsen
- BASE LAYER HOTEL Kobe 82 Rooms Opens Nov 10: 4-City Supply and Rates
References and Sources
■ Data sources
Opening data was compiled by MetroEngines Research & Consulting from first listing on the major booking sites (Hyogo 2026 N=67 properties, 1,284 rooms, as of November 9, 2026; 2022–2025 and the eight neighboring prefectures by the same method). The two rebrands were checked individually against each company’s announcements. Estimated settled ADR uses only finalized months (October 2025 and October 2026); municipal and prefectural values are the median of the properties covered. Room stock covers properties with 10 or more rooms (excluding leisure/love hotels) within each radius; properties with a selling price observed in the most recent three months were treated as operating (as of November 10, 2026). Land prices, zoning and flood inundation zones are from the MLIT Real Estate Information Library; construction costs are from MLIT’s Statistics on Building Construction Starts.
■ Estimate assumptions
200 rooms, 3,800㎡ site, 5,300㎡ gross floor area (approx. 1,603 tsubo), steel frame, 75% annual occupancy, 50% GOP margin, 7% target yield. Total investment = construction unit cost × gross floor area in tsubo + site area × commercial land price from the 2026 prefectural land price survey (Sanda 5-1: ¥79,500/㎡; Tamba 5-4: ¥44,600/㎡). Construction cost at three levels: ¥1.648M/tsubo (2024, steel-frame buildings for the accommodation industry), ¥2.410M/tsubo (2025, hotels or ryokan, steel frame) and ¥2.601M/tsubo (¥2.410M plus 1.5 years of escalation to the midpoint of construction). Required ADR = total investment × 7% ÷ (GOP margin × 200 rooms × 365 days × occupancy); expected yield (Table 8) is the inverse calculation.
■ Limitations
Opening timing is proxied by first listing date, so openings in November–December 2026 may increase as further listings appear. Opening counts for neighboring prefectures do not separate out rebrands. Estimated settled ADRs for Sanda and Tamba are for reference only, as fewer than 10 properties are covered. The estimates cover room revenue only and do not consider ancillary revenue, FF&E reserves, property taxes, design fees, pre-opening costs or financing terms; actual investment decisions require an individual feasibility study. Flood assessments are simplified, based on each property’s representative coordinates.
■ Market data
- MetroEngines Research & Consulting — new opening data (based on OTA listing confirmation, Hyogo 2022–2026), room stock within radii (Shin-Sanda Station 3km, Hikami IC 5km, Port Island 2km, as of November 10, 2026), estimated settled ADR by municipality (October 2025 and October 2026), estimated settled ADR by property (October 2026)
■ Government statistics and public data
- MLIT Real Estate Information Library (不動産情報ライブラリ) — prefectural land price survey (2026), zoning, flood inundation zones (maximum assumed scale)
- MLIT Statistics on Building Construction Starts (建築着工統計調査) (2024 accommodation industry; 2025 hotels or ryokan; planned construction cost and floor area by structure)
- MLIT Building Activity Statistics Survey (建築物動態統計調査) — hotel construction plans in Hyogo (based on building confirmation applications as of the survey date)
■ Industry reports
- Turner & Townsend, “Japan market insight” — construction cost escalation forecasts
- Relo Hotel Solutions, “What is GOPPAR?” (GOPPAR(ゴッパー)とは?) — general industry benchmark for GOP margin (around 30–40%)
■ News and press releases
- HMI Hotel Group: Courtyard by Marriott Kobe rebrand opening on October 1 (September 29, 2026, in Japanese)
- Kobe Shimbun: Hotel Pearl City Kobe becomes Courtyard by Marriott Kobe (October 2, 2026, in Japanese)
- Plan・Do・See: Oriental Hotel Kobe to be renamed THE ORIENT from February 1, 2026 (PR TIMES, in Japanese)
- Route Inn Japan: Hotel Route-Inn Tamba -Hikami Inter- opens July 9 (PR TIMES, in Japanese)
- Route Inn Japan: Hotel Route-Inn Kobe Sanda -Shin-Sanda Ekimae- opens September 14 (PR TIMES, September 14, 2026, in Japanese)
- Kobe Shimbun: Business hotel to be built in front of Shin-Sanda Station (December 2024, in Japanese)
- Develop: HOTEL R9 The Yard Tamba opens February 5 (@Press, in Japanese)
- BASE LAYER HOTEL opens in Kobe Sannomiya on November 10, 2026 (PR TIMES, in Japanese)
- Best Calendar: BASE LAYER HOTEL opens in Kobe Sannomiya on November 10 (11 room types, 82 rooms; in Japanese)
- THE PASONA natureverse retreat opens on Awaji Island (57 rooms)
- Rakuten STAY: Rakuten STAY TERRACE Kinosaki Riverside grand opening on July 23 (4 stories, 24 rooms; PR TIMES, July 9, 2026, in Japanese)
- City of Kobe: New bus terminal (Kumoidori 5-chome redevelopment, in Japanese)
- Kobe Shimbun: Luxury hotel to open in Sannomiya within FY2027 (May 2022, in Japanese)