

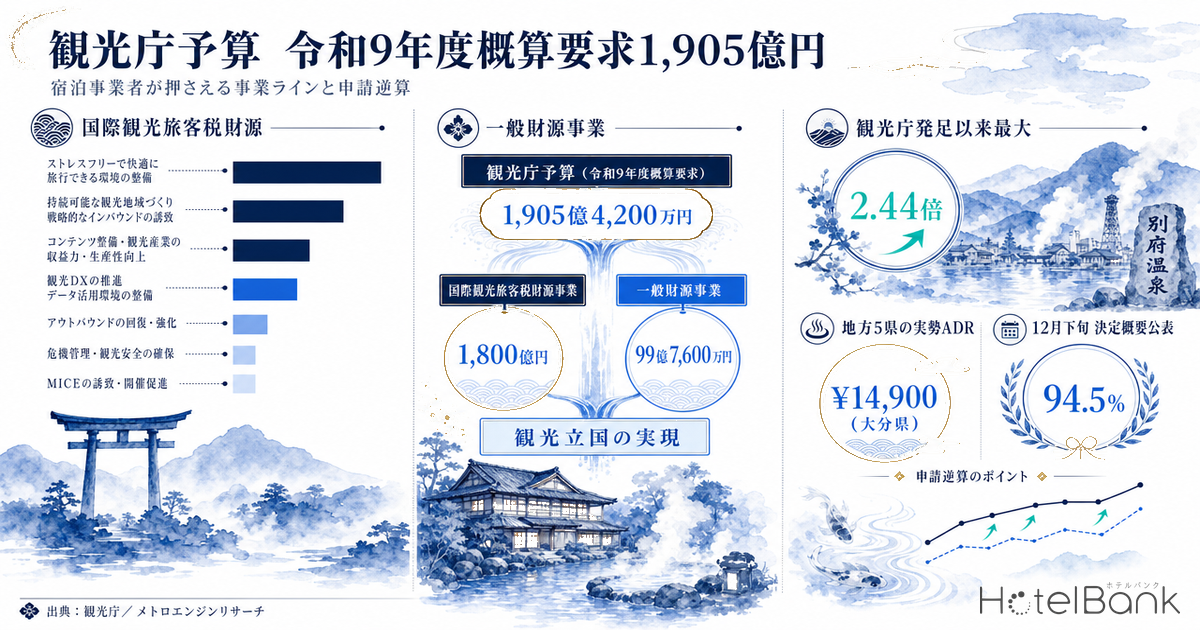
On August 28, 2026, the Japan Tourism Agency (JTA, 観光庁) published its budget request for FY2027 (令和9年度, April 2027–March 2028). The total request comes to ¥190.54 billion, the largest since the agency was established in October 2008. The increase is driven mainly by programs funded by the International Tourist Tax (国際観光旅客税), whose request has climbed to ¥180 billion (1.38x the FY2026 budget of ¥130 billion). Using the actual figures in the published documents, this article walks through how a request becomes an enacted budget, where the program lines that hotel operators actually use sit, and how to work backwards from the timeline when building the budget into your own capex and hiring plans. We also use internal data to show current market room rates in regional areas before any subsidies take effect.
Metric Definitions Used in This Article
- ADR (Average Daily Rate): An estimated settled rate (tax-exclusive equivalent), calculated by applying property-type correction factors to the lowest-plan price each property publishes on OTAs and other channels (per room, 2 guests, tax-inclusive). Checked against property-level results disclosed by listed hotel REITs (91 properties, most recent 3 months), the median error is about 7%. These are estimates and differ from each property’s actual settled rates and accounting figures. Area-level ADR is the median of the properties covered (the level of a typical property in the area). This article only shows months through July 2026, for which observations are finalized.
- Budget units: Government releases state figures in millions of yen; this article converts them to billions of yen (¥bn). Chart axes use 億円 (1 oku = ¥100 million). Because of rounding, breakdowns may not sum exactly to totals.
- Data sources: Budget figures from the Japan Tourism Agency, “Overview of the FY2027 Budget Request for the Japan Tourism Agency” (August 2026); room rates from MetroEngines Research
- — ¥190.54 billion Total FY2027 budget request, the largest since the JTA was created. But ¥180 billion (94.5%) is funded by the International Tourist Tax, and what those programs will be is not fixed until late December 2026.
- — ¥9.976 billion The request for general-revenue programs, where most of the open calls hotel operators apply to sit. In FY2026, the final budget came in at 0.78x the request, so a working range of ¥8–10 billion is a reasonable assumption.
- — 2.44x / 1.63x Within general revenue, the fastest-growing categories are domestic exchange and outbound expansion, and resilience of tourist destinations and the tourism industry. Workforce recruitment and training, tourism DX and labor-saving investment, and support for upgrading lodging facilities all sit in the latter category.
- — Grant decisions in June–August 2027 Many programs exclude orders placed or work started before the grant decision. Once completion within the fiscal year and results reporting are factored in, only about six months are usable, so large renovations need to be split across multiple fiscal years.
- — Oita ¥14,900 > Tokyo ¥14,600 Rates in regional areas likely to be targeted by subsidies are already high (trailing 12-month average estimated settled ADR). Subsidies are easier to justify on a payback basis when designed not to “lift rates” but to “extend the periods and number of days when high rates can be captured.”
Breaking Down the ¥190.5 Billion FY2027 Request — 94% Funded by the Tourist Tax
The JTA budget is made up of three funding sources with very different characteristics: programs funded by the International Tourist Tax, ordinary general-revenue programs, and the Special Account for Reconstruction from the Great East Japan Earthquake. The FY2027 request across these three sources is as follows.
| Category | FY2027 request | FY2026 budget | YoY multiple |
|---|---|---|---|
| International Tourist Tax-funded programs | ¥180.0bn | ¥130.0bn | 1.38x |
| General-revenue programs | ¥9.976bn | ¥8.345bn | 1.20x |
| (1) Strategic inbound promotion balanced with residents’ quality of life | ¥6.671bn | ¥6.317bn | 1.06x |
| (2) Expanding domestic exchange and outbound travel | ¥1.220bn | ¥0.500bn | 2.44x |
| (3) Resilience of tourist destinations and the tourism industry | ¥1.187bn | ¥0.727bn | 1.63x |
| (4) Other (routine administrative costs, etc.) | ¥0.898bn | ¥0.800bn | 1.12x |
| Special Account for Reconstruction from the Great East Japan Earthquake | ¥0.566bn | ¥0.665bn | 0.85x |
| Total | ¥190.542bn | ¥139.010bn | 1.37x |
Source: Compiled by HotelBank Editorial Team from the summary table in the Japan Tourism Agency, “Overview of the FY2027 Budget Request for the Japan Tourism Agency” (August 2026)
The first thing to note is the composition: ¥180 billion, or 94.5% of the total, is funded by the International Tourist Tax. The tax was raised from ¥1,000 to ¥3,000 per person for departures on or after July 1, 2026, and FY2027 is the first fiscal year in which a full year of revenue at the higher rate comes in. In other words, the growth in the total is most plainly read not as a new policy decision, but as the expanded tax base flowing straight through into the requested amount.
Meanwhile, most of the programs that hotel operators apply to directly through open calls sit on the far smaller general-revenue side, at ¥9.976 billion. The size of the headline total and the size of the programs your property can actually use need to be looked at separately.
What Is a Budget Request? — Three Stages: August Request, December Draft, March Enactment
A budget request (概算要求) is the procedure by which each ministry and agency submits to the Ministry of Finance the budget it believes it needs for the following fiscal year; the deadline is the end of August. The figures at this stage are only requests, not a finalized budget. From here, amounts and program content are settled in the following steps.
| Timing | What happens | What it means for hotel operators |
|---|---|---|
| End of August August 28, 2026 | Budget request published, showing requested amounts by category and key items | Policy direction becomes readable. Program names and requirements are not yet fixed |
| November–December | Ministry of Finance review. In some years a supplementary budget is compiled in parallel | Supplementary budgets must be spent within the fiscal year, so open calls may be announced on short notice |
| Late December | Cabinet approves the government budget draft. The JTA publishes its “Decision Overview.” Specific uses of Tourist Tax revenue are also decided by the Ministerial Council on the Promotion of Japan as a Tourism-Oriented Country | The most important moment, when program names and budget amounts are revealed. Identify the programs your property will target here |
| January–March | Deliberation in the ordinary Diet session. Budget overview documents published in late January | Period to assemble application materials: quotes, drawings, internal team setup |
| End of March | Budget enacted | Preconditions for execution are in place |
| April onward | Open calls launch program by program | Many programs exclude orders or construction started before the grant decision, so order timing must be planned |
Source: Compiled by HotelBank Editorial Team from the publication history of JTA documents (FY2024–FY2027)
Splitting the JTA budget history into three parts — general revenue in the initial budget, Tourist Tax revenue in the initial budget, and supplementary budgets — makes the structural shift over the past decade and more very clear.
Source: Compiled by HotelBank Editorial Team from the budget history in the Japan Tourism Agency, “Overview of the FY2027 Budget Request for the Japan Tourism Agency.” Chart legend (top to bottom): initial budget (general revenue), initial budget (International Tourist Tax), supplementary budgets, etc.; unit: 億円 = ¥100 million. FY2027 is the requested amount (before any supplementary budget)
From FY2020 to FY2022, supplementary budgets of roughly ¥90–150 billion were added each year, and for several years the supplementary budget exceeded the initial budget. Supplementary budgets have since settled down, and Tourist Tax revenue has instead become the backbone of the initial budget. In FY2026, the initial budget alone reached ¥138.345 billion (general account basis, excluding the Special Account for Reconstruction), and the FY2027 request goes further still, to about ¥190 billion. A larger share in the initial budget also means a larger share of programs whose open-call schedules can be anticipated from the start of the fiscal year. Where the FY2026 ¥138.3 billion actually went geographically is examined in our analysis of how the JTA’s FY2026 ¥138.3 billion budget is being spent, which tests how far regional dispersion has really gone.
FY2026: ¥81.4 Billion Requested, ¥138.3 Billion Approved — Only Tourist Tax Funding Grew
The preceding year, FY2026, is a good case study of how approved amounts move relative to requests. The FY2026 budget request totaled ¥81.359 billion, but the enacted initial budget was ¥138.345 billion (excluding the Special Account for Reconstruction), 1.70x the request. On that figure alone, one might conclude that “approvals come in 70% above requests,” but the breakdown tells a different story.
Source: Compiled by HotelBank Editorial Team from the JTA FY2026 and FY2027 budget request overviews and the FY2026 budget overview. Chart shows the FY2026 approved-to-requested multiple for (top to bottom) Tourist Tax funding, general-revenue programs, the Special Account for Reconstruction, and the total (general account basis)
Tourist Tax funding went from ¥70 billion requested to ¥130 billion approved, a 1.86x increase. This is because, after the request was submitted, the FY2026 tax reform decided to raise the tax from ¥1,000 to ¥3,000, expanding the funding source itself. It was an unusual year, with a system change landing between request and approval.
General-revenue programs, by contrast, went from ¥10.694 billion requested to ¥8.345 billion approved, a multiple of 0.78x. The Special Account for Reconstruction was ¥0.665 billion both requested and approved, 1.00x. On the general-revenue side, where most of the programs hotel operators apply to sit, taking the requested amount at face value leads to overestimating the actual budget size.
What the ¥180 Billion in Tourist Tax Funding Covers Is Decided in December — Reading the FY2026 Allocation
The budget request document states the following about Tourist Tax funding: “At the time of the budget request, only the requested amount is shown; specific programs will be (omitted) considered in the budget compilation process and, taking into account the opinions of private-sector experts, decided by the Ministerial Council on the Promotion of Japan as a Tourism-Oriented Country (chaired by the Prime Minister).” In other words, the ¥180 billion that makes up 94.5% of the total has no confirmed program names yet.
So where will it go? A useful reference is the FY2026 allocation included in the same document. The ¥130 billion in Tourist Tax funding is booked in a lump sum under the JTA and then transferred to the relevant ministries and agencies for execution.
| Three use areas | Executing agency | FY2026 amount |
|---|---|---|
| 1. Creating a stress-free, comfortable travel environment Subtotal ¥59.7bn | Immigration Services Agency | ¥12.8bn |
| Ministry of Finance | ¥7.1bn | |
| Japan Tourism Agency | ¥22.3bn | |
| Ministry of Foreign Affairs | ¥17.5bn | |
| 2. Making information on Japan’s diverse attractions easier to obtain | Japan Tourism Agency | ¥9.2bn |
| 3. Raising satisfaction with local experiences and stays by developing tourism resources that draw on regional culture, nature, etc. Subtotal ¥61.3bn | Agency for Cultural Affairs | ¥22.4bn |
| Ministry of the Environment | ¥17.8bn | |
| Japan Tourism Agency | ¥15.3bn | |
| Imperial Household Agency | ¥5.8bn | |
| Total (of which JTA-booked: ¥46.8bn, 36.0%) | ¥130.2bn | |
Source: Compiled by HotelBank Editorial Team from the Ministerial Council on the Promotion of Japan as a Tourism-Oriented Country, “Basic Policy on the Use of the International Tourist Tax” (partially revised December 26, 2025). Because of rounding, the total does not match the headline amount
Of the ¥130 billion, the JTA itself executes ¥46.8 billion, just 36.0% of the total. The rest is allocated to areas such as more advanced immigration screening (Immigration Services Agency), customs and tax-exemption related work (Ministry of Finance), promotion through overseas diplomatic missions (Ministry of Foreign Affairs), wider public access to cultural properties (Agency for Cultural Affairs), and environmental improvements in national parks (Ministry of the Environment). The practical assumption is that the programs lodging facilities can apply to directly sit within this JTA-booked portion and the general-revenue programs.
The FY2027 document gives, as examples of initiatives that could be carried out with Tourist Tax funding, promoting sustainable destination development by whole communities, fostering internationally competitive snow resorts, supporting town development in regional hot spring areas through the removal and regeneration of abandoned buildings, and tourism revitalization support for recovery from natural disasters. All of these are positioned as examples from FY2026 programs; it is not confirmed that programs with the same names will be set up in FY2027.
Five Program Lines Hotel Operators Should Watch
Cross-referencing the key items in the request document with the policy list in the 5th Basic Plan for the Promotion of Japan as a Tourism-Oriented Country, approved by the Cabinet in March 2026, shows which category each initiative closely relevant to hotel operators falls under.
| Initiative | Placement in the FY2027 request | Requested amount for category | YoY |
|---|---|---|---|
| Workforce recruitment and training | General revenue, “Resilience of tourist destinations and the tourism industry” — Human resource development promotion program for destinations and the tourism industry (promoting the industry’s appeal to recruit and train talent in Japan and overseas, building training environments, developing destination management and lodging professionals) | ¥1.187bn (category total) | 1.63x |
| Tourism DX and labor-saving investment | Same category, item (3) Promoting tourism DX and regional transport DX; the Basic Plan explicitly lists “productivity gains through tourism DX, labor-saving investment, etc.” | ¥1.187bn (category total) | 1.63x |
| Support for upgrading lodging facilities | Same category, item (4) Strengthening the management resilience of the tourism industry. Town development support for regional hot spring areas through removal and regeneration of abandoned buildings is also cited as an example on the Tourist Tax side | ¥1.187bn + part of Tourist Tax funding | 1.63x / 1.38x |
| Universal tourism | Placed in both “Expanding domestic exchange and outbound travel,” item (2) Developing new exchange markets, and “Resilience of tourist destinations and the tourism industry,” item (7) Improving the visitor environment to meet diverse needs | ¥1.220bn (domestic exchange category total) | 2.44x |
| Attracting visitors to regions and improving the visitor environment | Tourist Tax funding, “Developing tourism resources that draw on regional culture, nature, etc.” — DMO support, fostering snow resorts, environmental improvements in national parks, environmental improvements to enrich local tourism resources | Part of ¥180bn (programs fixed in December) | 1.38x |
| Tourism recovery in disaster-affected areas | Special Account for Reconstruction (tourism-related reconstruction support in Fukushima); for the Noto region, the Tourist Tax side cites examples such as drawing up plans for lodging facilities to reopen and creating visitor-attracting content | ¥0.566bn + part of Tourist Tax funding | 0.85x |
Source: Compiled by HotelBank Editorial Team from the key items and main policy list in the Japan Tourism Agency, “Overview of the FY2027 Budget Request for the Japan Tourism Agency,” and the “Basic Plan for the Promotion of Japan as a Tourism-Oriented Country (5th)” (Cabinet decision, March 27, 2026)
By growth rate, general-revenue increases are concentrated in the top two categories: domestic exchange and outbound expansion at 2.44x, and resilience of tourist destinations and the tourism industry at 1.63x. The former includes promoting universal tourism, creating “related populations” and encouraging dual-region living, generating demand that matches diverse travel needs, and developing domestic school-trip programs. The latter covers workforce, tourism DX and labor-saving, support for upgrading lodging facilities, and a sound competitive environment. In short, the areas of greatest interest to hotel operators are concentrated in categories that are small in yen terms but growing quickly. For tourism DX and labor-saving investment specifically, our complete guide to tourism DX subsidies for hotels and ryokan sorts the subsidies usable under current programs into seven schemes — worth checking as options before FY2027 programs arrive.
Where Will FY2027 Land? Setting a Working Range
What follows is not confirmed information, so we state our assumptions and express the outlook as a range. The approved amount will only be known when the Cabinet approves the government budget draft in late December 2026; until then, only the requested amount is available.
HotelBank estimates (projections, not confirmed figures)
- General-revenue programs: ¥9.976 billion requested. Applying FY2026’s approved-to-requested multiple of 0.78x gives about ¥7.8 billion; at 1.00x, about ¥10 billion. In practice, a range of ¥8–10 billion is a reasonable assumption.
- Tourist Tax-funded programs: ¥180 billion requested. In FY2026, the decision to raise the tax rate came after the request, lifting the approval to 1.86x. The FY2027 request, however, already assumes the current ¥3,000 rate, so the same kind of upside is not built into the structure.
- Supplementary budgets: Recent supplementary budgets were ¥54.3 billion in FY2024 and ¥22.5 billion in FY2025. Whether one is compiled, and its size, varies by year, so do not build it into business plans — treat it as potential upside if it materializes.
Plugging the requested amounts straight into your property’s plan will lead to assuming a larger scale than reality, especially on the general-revenue side. Conversely, on the Tourist Tax side, rather than holding off simply because program names will not appear until December, it pays to check in advance whether your investment themes overlap with FY2026’s example programs (fostering snow resorts, removing and regenerating abandoned buildings, environmental improvements to enrich local tourism resources, etc.). That way you can act immediately after the December announcement.
Market Rates Before Subsidies — Estimated Settled ADR in Five Regional Prefectures
Many subsidy programs aim to attract visitors to regions and improve the visitor environment there. So, using internal data, we check current rate levels — before any subsidies — in five prefectures that resemble the regional types named as program areas in the request document: Ishikawa, where tourism recovery in Noto is specified; Fukushima, where tourism recovery from the Great East Japan Earthquake is funded through the Special Account for Reconstruction; Nagano and Niigata, key locations for snow resort development; and Oita, where town development support for regional hot spring areas is expected to apply.
Source: Compiled by HotelBank Editorial Team from MetroEngines Research. Chart labels: 大分県 = Oita, 長野県 = Nagano, 石川県 = Ishikawa, 新潟県 = Niigata, 福島県 = Fukushima, 東京都 = Tokyo
| Area | Trailing 12-month avg. ADR | vs. Tokyo | July 2026 ADR | YoY | N (July 2026) |
|---|---|---|---|---|---|
| Oita | ¥14,900 | 101.9% | ¥12,600 | -9.4% | 466 properties |
| Nagano | ¥12,100 | 82.6% | ¥11,100 | +0.3% | 820 properties |
| Ishikawa | ¥11,200 | 76.8% | ¥9,700 | -3.3% | 242 properties |
| Niigata | ¥9,700 | 66.5% | ¥9,000 | -3.4% | 421 properties |
| Fukushima | ¥7,500 | 51.4% | ¥7,300 | -1.2% | 439 properties |
| Tokyo (reference) | ¥14,600 | 100.0% | ¥12,600 | -4.8% | 1,136 properties |
Source: Compiled by HotelBank Editorial Team from MetroEngines Research. Trailing 12 months is the average of monthly median estimated settled ADR from August 2025 to July 2026
On a trailing 12-month average basis, Oita at ¥14,900 edges out Tokyo at ¥14,600. Lumping all regions together as “low-rate” does not hold, at least for prefectures with hot spring areas. Ishikawa is at ¥11,200 and Nagano at ¥12,100. Even in areas likely to be targeted by subsidy programs, the starting point for rates is already fairly high. For how discount funding translates into actual rates at Oita’s hot spring resorts, see our analysis of the net rate gap between Kurokawa Onsen and Yufuin, which reads it through the differences in program design across the prefectural border.
Tracking the data month by month, the seasonal pattern turns out to be the inverse of central Tokyo’s.
Source: Compiled by HotelBank Editorial Team from MetroEngines Research (2026 data through July, finalized observations only). Chart compares monthly estimated settled ADR for Oita (大分県) and Tokyo (東京都)
Tokyo peaks for the year in April and dips in June–July. Oita, by contrast, is highest in December and January: ¥17,300 in December 2025 and ¥17,300 in January 2026, both above Tokyo in the same months (¥15,800 and ¥13,200). In other words, during winter hot spring season, regional onsen destinations overtake the central city and business-hotel market on rates.
This changes how subsidy programs should be viewed. Investments such as improving the visitor environment or regenerating abandoned buildings are easier to justify on a payback basis when designed not as “lifting up low-rate areas,” but as “increasing the number of sellable days in periods when high rates are already achieved, or raising rate levels in shoulder seasons.” Establishing pre-subsidy rate levels first is also an effective way to demonstrate that the impact figures in a business plan are reasonable.
Building It Into Capex and Hiring Plans — Working Backwards from the Application Timeline
Many subsidy programs exclude expenses for contracts, orders or construction started before the grant decision. Capex decisions therefore need to be worked backwards not from “when do we want to do the work” but from “when will the grant decision come.” A standard sequence, assuming you aim to use FY2027 programs, looks like this.
| Timing | Capex actions | Hiring and workforce actions |
|---|---|---|
| September–November 2026 | Check where key items in the request overlap with your investment themes. Get one rough quote | Provisionally set the job types and headcount to train. Take stock of existing training plans |
| Late December 2026 | Confirm the published Decision Overview. Program names and budget amounts are revealed | Confirm the framework of the human resource development promotion program |
| January–March 2027 | Finalize formal quotes, drawings and construction schedule. Decide the mix of own funds and borrowing | Finalize next year’s hiring plan, aligned with the expected training program |
| April–June 2027 | Open calls begin. Submit applications | Open calls begin — often in the first half of the fiscal year |
| June–August 2027 | Grant decision. Only now proceed to orders and contracts | Fix the training start date |
| Autumn 2027–February 2028 | Construction. Build completion within the fiscal year and results reporting into the schedule | Implementation and results reporting |
Source: Compiled by HotelBank Editorial Team based on the JTA’s budget publication schedule. Open-call timing and requirements for individual programs are governed by each program’s application guidelines
Three practical implications follow. First, if you want to avoid construction during peak season, you need to secure construction slots from autumn onward on the assumption that the grant decision will come in summer. Second, for programs that require completion and results reporting within the fiscal year, only about six months are effectively available from start to finish, so large renovations with long lead times are easier to handle if split across multiple fiscal years, or run in parallel with a financing plan that does not rely on subsidies. Third, hiring and training programs tend to open calls in the first half of the fiscal year, so starting the review at the same time as next spring’s hiring plan connects the two well.
Separately, the item the JTA lists in its FY2027 tax reform requests is a review of verification procedures for the consumption tax exemption system for foreign visitors, in connection with the introduction of the Japan Electronic System for Travel Authorization (JESTA) during FY2028. For lodging facilities with an on-site tax-free shop, this is an issue to anticipate as operating changes from FY2028 onward.
Summary
The FY2027 budget request of ¥190.542 billion is the largest since the JTA was established, but 94.5% of it is funded by the International Tourist Tax, and the actual programs will be fixed in the budget compilation in late December 2026. General-revenue programs, where most of the programs hotel operators actually apply to sit, total ¥9.976 billion; given how FY2026 moved from request to approval (0.78x), a working assumption of ¥8–10 billion is reasonable.
The standout growth rates are 2.44x for domestic exchange and outbound expansion, and 1.63x for resilience of tourist destinations and the tourism industry. The former covers universal tourism, related populations and dual-region living; the latter covers workforce recruitment and training, tourism DX and labor-saving investment, and support for upgrading lodging facilities. Neither is large in yen terms, but in direction both overlap closely with hotel operators’ investment themes.
On rates, levels in regional areas likely to be targeted by subsidies are already fairly high. Oita’s trailing 12-month average of ¥14,900 exceeds Tokyo’s ¥14,600, and in winter it beats central Tokyo on a monthly basis as well. Whether subsidy programs can be designed not as “a means of lifting rates” but as “a means of extending the periods and days when high rates can be captured” will determine how convincingly the investment payback can be explained. The next milestone is the publication of the Decision Overview in late December 2026.
Related Articles
- How the JTA’s FY2026 ¥138.3 Billion Budget Is Spent — The Ideal of Regional Dispersion vs. the Reality of a 2.5x ADR Gap
- [FY2026 Edition] Complete Guide to Tourism DX Subsidies for Hotels and Ryokan — Seven Schemes for PMS and Smart Check-in Adoption
- Tourism DX Promotion Program (Up to ¥15 Million) — A Step-by-Step Subsidy Application Guide for Hotel Operators
- Kyushu Support Discount: Net Rate Gap Between Kurokawa Onsen and Yufuin Narrows to ¥665 — A 10pt Program Difference Across a 31km Prefectural Border
References and Sources
■ Primary sources (Japan Tourism Agency / Ministry of Land, Infrastructure, Transport and Tourism)
- Japan Tourism Agency, “Overview of the FY2027 Budget Request for the Japan Tourism Agency” (published August 28, 2026, PDF, Japanese) — summary table, key items, main policy list, FY2027 tax reform requests, basic policy on the use of the International Tourist Tax
- Japan Tourism Agency, “Budget and Taxation” page (list of budget requests, decision overviews and budget overviews by fiscal year, Japanese)
- Japan Tourism Agency, “Use of the International Tourist Tax” (last updated May 21, 2026, Japanese) — three use areas for tax revenue, and the rate increase to ¥3,000 from July 1, 2026
- Ministerial Council on the Promotion of Japan as a Tourism-Oriented Country, “Basic Policy on the Use of the International Tourist Tax” (decided December 24, 2021; partially revised December 26, 2025)
- “Basic Plan for the Promotion of Japan as a Tourism-Oriented Country (5th)” (Cabinet decision, March 27, 2026; plan period FY2026–FY2030, Japanese)
■ News coverage (FY2026 and FY2027 budget requests, Japanese)
- Travel Voice, “JTA Budget Request 2027: Record ~¥190 Billion, Domestic and Outbound Up 2.44x” (August 28, 2026)
- Kanko Keizai Shimbun, “[Breaking] JTA’s Next-Year Budget Request at ¥190 Billion, Up on Tourist Tax Increase” (August 2026)
- Honichi Lab, “FY2027 JTA Budget Request Hits Record ¥190.5 Billion on Tourist Tax Increase” (September 4, 2026)
- Travel Voice, “JTA Budget Request 2026: Total Up 40% to ¥81.4 Billion” (August 26, 2025) — breakdown of the FY2026 request of ¥81.359 billion
- Travel Vision, “JTA FY2026 Budget Request ¥81.3 Billion, Record ¥70 Billion from Tourist Tax” (August 2025)
■ Market data
- MetroEngines Research — Estimated settled ADR by prefecture (January 2025–July 2026; Ishikawa N=242, Fukushima N=439, Nagano N=820, Oita N=466, Niigata N=421, Tokyo N=1,136; all as of July 2026)