

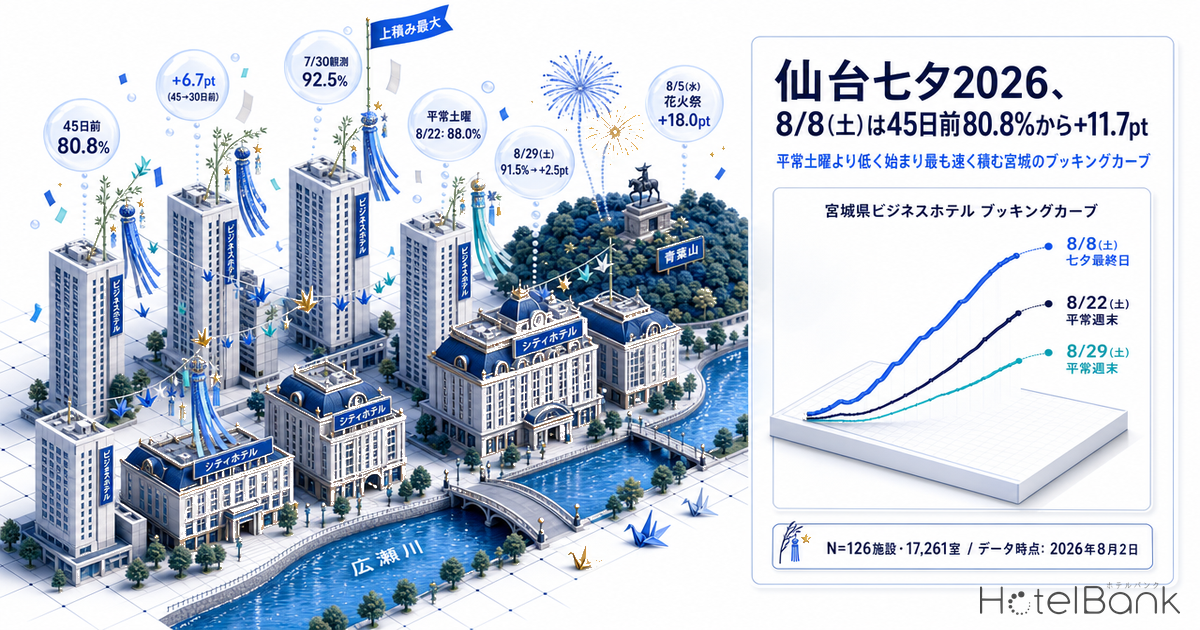
On Saturday, August 8 — the closing day of the Sendai Tanabata Festival 2026 — estimated OCC (based on OTA-listed inventory) at business hotels in Miyagi stood at 80.8% as of 45 days before the stay date. That is 7.2pt below the 88.0% recorded for Saturday, August 22, an ordinary Saturday in the same month. Yet when we look at how much was added between 45 and 30 days out, August 8 gained +6.7pt — the largest of the nine stay dates compared here, ahead of August 22’s +4.2pt and August 29’s +2.5pt. As of the July 30 observation, August 8 had tightened to 92.5% and August 22 to 94.7%. Event dates take the shape of “starting low and filling fast” — and this asymmetry shows the danger of judging by the 45-day-out level alone and rushing to sell early.
Scope: business hotels in Miyagi, N=126 properties (17,261 rooms) / city hotels, N=21 properties (2,963 rooms). This article does not address price metrics; occupancy is expressed only as an estimate based on OTA-listed inventory. Definitions appear at the end of the article. Data as of: August 2, 2026.
- — Starts low, fills fastest — the asymmetry of event dates — Estimated OCC (OTA-listed inventory basis) at business hotels for the Tanabata closing day, Saturday August 8, was 80.8% at 45 days out, 7.2pt below the 88.0% of ordinary Saturday August 22. But the gain from 45 to 30 days out was +6.7pt, the largest among the nine stay dates examined (Miyagi, as of August 2, 2026).
- — The 45-day-out level and the subsequent gain do not move together — Saturday August 29 had the highest level at 45 days out (91.5%) but the smallest gain (+2.5pt), while August 8, mid-range at 45 days out, had the largest (+6.7pt). What determines the gain is not the absolute level but the timing at which demand arrives.
- — The biggest late-stage move was the fireworks night — Wednesday August 5 went from 73.6% at 45 days out to 91.6% at the July 30 observation (6 days remaining), a gain of +18.0pt. The comparable ordinary Wednesday, August 19, moved only from 70.1% to 79.5% at the July 30 observation (20 days remaining).
- — Headroom is asymmetric by hotel type — At 45 days out on the Tanabata closing day, city hotels stood at 95.1% versus 80.8% for business hotels — a 14.3pt gap. City hotels added +1.9pt, business hotels +6.7pt. Holding inventory until close-in is a strategy that works on the business-hotel side (N = 126 business properties / 17,261 rooms; 21 city properties / 2,963 rooms).
- — Do not extrapolate a strong Tanabata week to the whole month — July actuals showed a day-of-week spread of 97.3% on Saturdays versus 85.2% on Mondays at business hotels (12.1pt). Meanwhile, Wednesday August 19 — the week after Obon — sat at 79.5% at the July 30 observation, still well short of July’s Wednesday average of 91.8%.
Sendai Tanabata 2026 runs Thu Aug 6 – Sat Aug 8, with the fireworks festival the night before on Wed Aug 5
According to the official site of the Sendai Tanabata Festival Association (secretariat: Sendai Chamber of Commerce and Industry), the festival is held on August 6–8 every year regardless of the day of the week. Mapped onto the 2026 calendar, August 6 is a Thursday, the 7th a Friday, and the 8th a Saturday. In addition, the 57th Sendai Tanabata Fireworks Festival takes place the previous evening, Wednesday August 5, from 19:30 to 20:30 (scheduled) around Aobayama Park and the Hirose River banks (organizer: Sendai Junior Chamber Inc.). The 2026 demand event is therefore made up of four days, from Wednesday August 5 through Saturday August 8, with only the final day falling on a Saturday. For how the scale of the Sendai Tanabata Festival feeds through to lodging supply and demand, we compared it with another city’s Tanabata in Hiratsuka vs Sendai Tanabata 2026: Day-Trip vs Overnight Hotel Demand.
We check how these four days show up in the shape of lodging demand by matching them against the same weekdays in an ordinary week. As control dates we use August 19 (Wed), 20 (Thu), 21 (Fri) and 22 (Sat), avoiding the Obon week, plus August 29 (Sat) at month-end. All comparisons are made at fixed points with the number of days remaining until the stay date (lead time) aligned. In addition to the 45-day-out and 30-day-out fixed points, we use the cross-section of July 30, 2026 — the most recent observation date common to every stay date — as a third fixed point. July 30 is a date on which the number of observed properties was close to full relative to the denominator for all nine stay dates covered here, but the days remaining differ by stay date (9 days for August 8, 23 days for August 22, 30 days for August 29). Because this column alone does not have aligned lead times, read it not as a level comparison but as “what is on screen right now.”
Three Saturdays in August — the Tanabata closing day starts lowest and fills fastest
We begin with business hotels (N=126 properties, 17,261 rooms), overlaying the booking curves of the three Saturdays in August. The horizontal axis is days remaining until the stay date: 45 days out on the left, moving closer to the stay date toward the right.
Source: Compiled by the HotelBank Editorial Team from MetroEngines Research
The three lines differ clearly in both starting height and slope. At 45 days out, August 29 is highest at 91.5%, August 22 next at 88.0%, and the Tanabata closing day of August 8 lowest at 80.8%. Yet the slopes run in the opposite order, with August 8 the steepest. Over the five weeks from 45 to 30 days out, August 8 added +6.7pt, August 22 +4.2pt, and August 29 only +2.5pt. August 29 had already reached 94.0% with 30 days remaining, barely above its 91.5% at 45 days out — inventory had essentially been absorbed by the 45-day mark.
At the July 30 observation (9 days remaining for August 8), August 8 stood at 92.5%, August 22 at 94.7%, and August 29 at 94.0%. The 7.2pt gap between August 8 and August 22 at 45 days out had narrowed to 2.2pt. The Tanabata closing day is the stay date among August’s Saturdays on which inventory keeps moving the longest.
| Stay date | Category | T-45 | T-30 | Jul 30 obs. | Gain T-45 → T-30 | Share of properties with no confirmable listed inventory (Jul 30 obs.) |
|---|---|---|---|---|---|---|
| Aug 5 (Wed) | Fireworks festival | 73.6% | 78.6% | 91.6% (6 days left) | +5.0pt | 22.2% |
| Aug 6 (Thu) | Tanabata day 1 | 73.6% | 78.0% | 87.9% (7 days left) | +4.4pt | 16.7% |
| Aug 7 (Fri) | Tanabata day 2 | 77.8% | 83.5% | 88.8% (8 days left) | +5.7pt | 14.3% |
| Aug 8 (Sat) | Tanabata closing day | 80.8% | 87.5% | 92.5% (9 days left) | +6.7pt | 43.7% |
| Aug 19 (Wed) | Ordinary | 70.1% | 74.8% | 79.5% (20 days left) | +4.7pt | 6.3% |
| Aug 20 (Thu) | Ordinary | 72.6% | 77.7% | 81.5% (21 days left) | +5.1pt | 7.9% |
| Aug 21 (Fri) | Ordinary | 75.4% | 79.7% | 82.8% (22 days left) | +4.3pt | 7.1% |
| Aug 22 (Sat) | Ordinary weekend | 88.0% | 92.2% | 94.7% (23 days left) | +4.2pt | 49.2% |
| Aug 29 (Sat) | Ordinary weekend | 91.5% | 94.0% | 94.0% (30 days left) | +2.5pt | 44.8% |
Miyagi business hotels. All figures are estimated OCC (OTA-listed inventory basis). The denominator is 126 properties / 17,261 rooms for Aug 5–22, and 125 properties / 16,975 rooms for Aug 29 only. Observed properties numbered 112–120 at 45 days out, 116–124 at 30 days out, and 124–126 at the July 30 observation. “Share of properties with no confirmable listed inventory” is the estimated proportion of properties for which inventory for that stay date could not be confirmed on OTAs and similar channels.
Source: Compiled by the HotelBank Editorial Team from MetroEngines Research
Reading the table across, it is striking how small the difference in “position at 45 days out” is between the four Tanabata days and the same weekdays in an ordinary week. Wednesday to Wednesday, August 5 at 73.6% versus August 19 at 70.1% is a 3.5pt gap; Thursday to Thursday, August 6 at 73.6% versus August 20 at 72.6% is only 1.0pt; Friday to Friday, August 7 at 77.8% versus August 21 at 75.4% is just 2.4pt. Looking only at the 45-day-out cross-section, the Tanabata week looks much like an ordinary week. The divergence opens up after that.
The 45-day-out level and the subsequent gain do not move together
For the nine stay dates, we place the estimated OCC at 45 days out (line) alongside the gain from there to 30 days out (bars). If the two moved in the same direction, dates that started higher would also add more — but the actual relationship runs the other way.
Source: Compiled by the HotelBank Editorial Team from MetroEngines Research
August 19 (70.1%) and August 20 (72.6%), the lowest at 45 days out, posted mid-range gains of +4.7pt and +5.1pt. Meanwhile August 8, mid-range at 45 days out at 80.8%, showed the largest gain at +6.7pt, and August 29, the highest at 91.5%, the smallest at +2.5pt. In other words, what governs the size of the gain is not the absolute level at 45 days out but the timing at which demand for that stay date arrives. On an event date, a substantial share of demand has yet to arrive as of 45 days out. A similar shape appears at another large Tohoku event: 94.5% Sold 45 Days Out: Omagari Fireworks vs a Normal Akita Weekend traces how the event date — already at 94.5% at 45 days out — parted ways with an ordinary weekend.
The trajectory of the fireworks night, Wednesday August 5, is emblematic. At 73.6% at 45 days out and 78.6% at 30 days out, it tracked in parallel with the ordinary Wednesday of August 19 (70.1% to 74.8%). But by the July 30 observation (6 days remaining), it had reached 91.6%, a gain of +18.0pt from 45 days out. At the same July 30 observation, August 19 stood at 79.5% (20 days remaining, +9.4pt from 45 days out). Because the days remaining are not aligned, the levels cannot be compared directly, but the shape of the trajectories shows that the Tanabata-week stay dates absorb inventory strongly in the close-in phase. Thursday August 6 also moved +14.3pt, from 73.6% at 45 days out to 87.9% at the July 30 observation (7 days remaining).
The share of properties with no confirmable listed inventory points the same way. For August 8 it rose in steps: 32.5% at 45 days out, 41.3% at 30 days out, and 43.7% at the July 30 observation. On the same day of the week, August 29 was essentially flat, from 47.2% at 45 days out to 44.8% at the July 30 observation — settled at an early stage. August 5 doubled, from 11.1% at 45 days out to 22.2% at the July 30 observation.
City hotels are already near the ceiling at 45 days out — headroom sits with the business-hotel segment
Applying the same analysis to city hotels (N=21 properties, 2,963 rooms) changes the picture.
| Stay date | Category | T-45 | T-30 | Jul 30 obs. | Gain T-45 → T-30 | Share of properties with no confirmable listed inventory (Jul 30 obs.) |
|---|---|---|---|---|---|---|
| Aug 5 (Wed) | Fireworks festival | 88.6% | 92.1% | 94.4% | +3.5pt | 14.3% |
| Aug 6 (Thu) | Tanabata day 1 | 89.5% | 90.8% | 93.5% | +1.3pt | 28.6% |
| Aug 7 (Fri) | Tanabata day 2 | 89.9% | 93.8% | 94.5% | +3.9pt | 19.0% |
| Aug 8 (Sat) | Tanabata closing day | 95.1% | 97.0% | 99.2% | +1.9pt | 61.9% |
| Aug 19 (Wed) | Ordinary | 85.3% | 88.3% | 91.2% | +3.0pt | 19.0% |
| Aug 20 (Thu) | Ordinary | 84.9% | 87.6% | 90.7% | +2.7pt | 9.5% |
| Aug 21 (Fri) | Ordinary | 87.2% | 90.6% | 92.3% | +3.4pt | 19.0% |
| Aug 22 (Sat) | Ordinary weekend | 95.7% | 98.5% | 99.2% | +2.8pt | 71.4% |
| Aug 29 (Sat) | Ordinary weekend | 98.8% | 98.7% | 98.7% | −0.1pt | 71.4% |
Miyagi city hotels, N=21 properties / 2,963 rooms. Days remaining in the July 30 observation column are the same as in the business-hotel table (Aug 5 = 6 days left through Aug 29 = 30 days left). Observed properties numbered 19–21 at 45 and 30 days out, and 21 at the July 30 observation.
Source: Compiled by the HotelBank Editorial Team from MetroEngines Research
At city hotels, the Tanabata closing day of August 8 had already reached 95.1% at 45 days out — a 14.3pt gap versus 80.8% at business hotels. The gain was also limited to +1.9pt on August 8, below August 22’s +2.8pt and August 5’s +3.5pt. August 29 went from 98.8% at 45 days out to 98.7% at 30 days out, with virtually no headroom left. Miyagi’s city-hotel sample is limited to 21 properties, so individual properties weigh heavily on the aggregate and this should be discounted accordingly. Even so, the structure is readable: the strategy of holding event-date inventory until close-in works on the business-hotel side, where there is still distance to the ceiling at 45 days out.
Turning to the share of properties with no confirmable listed inventory, city hotels on August 8 reached 61.9% at the July 30 observation, well above the 43.7% at business hotels. Yet the ordinary weekends of August 22 and August 29 were both higher still at 71.4%. Rather than the Tanabata closing day standing out for city hotels, the reality is closer to it being one day within a broadly tight set of August weekends. How the 45-day-out level corresponds to close-in headroom by hotel type is examined with the same question in Tochigi Booking Curves by Type: Resort 81.1% at T-45, Only +2.6pt Left.
The base set by July actuals — a day-of-week spread of 97.3% on Saturdays and 85.2% on Mondays
To judge August’s booking pace, it helps to establish where the most recent completed month landed. In July 2026, Miyagi’s monthly average estimated OCC was 91.4% at business hotels (120–126 properties, 16,417–17,261 rooms) and 93.1% at city hotels (18–21 properties, 2,811–2,963 rooms). Averaged by day of week, the shape is as follows.
Source: Compiled by the HotelBank Editorial Team from MetroEngines Research
For business hotels, Saturday is highest at 97.3% and Monday lowest at 85.2%, a spread of 12.1pt. Sunday is also low at 87.6%. For city hotels, Saturday is 98.7% and Monday 88.5%, a spread of 10.2pt, with Sunday higher than business hotels at 92.5%. Both segments show the same shape: demand builds from Thursday (business 93.3%, city 92.9%) through Saturday, then falls back on Sunday and Monday.
Against that base, business hotels on Wednesday August 19 sitting at 79.5% at the July 30 observation (20 days remaining) means there is still distance to July’s Wednesday average of 91.8%. August 19 falls in the week after Obon. By contrast, Wednesday August 5 in the Tanabata week had reached 91.6% at the July 30 observation (6 days remaining), roughly level with July’s Wednesday average. August’s day-of-week pattern clearly takes a different shape in the Tanabata week than in the week after Obon.
For revenue managers running business and city hotels in Miyagi — implications and an action plan
1. “A low level at 45 days out” does not mean “a weak date.” At the market level, business hotels on the Tanabata closing day of August 8 started from 80.8% at 45 days out, 7.2pt below ordinary Saturday August 22 (88.0%). Deciding to release inventory early on the basis of that cross-section alone means taking the +6.7pt of demand that arrived afterwards (through 30 days out) at settings made at an early stage. When reading your own booking curve, look at two axes rather than the absolute level at 45 days out: whether your property sits above or below the market curve for the same area and same segment, and whether your slope from there is gentler or steeper than the market’s.
2. The phase in which the gain occurs differs by stay date. Saturday August 29 added only +2.5pt from 91.5% at 45 days out — essentially settled at the 45-day mark. Conversely, Wednesday August 5 moved +18.0pt, from 73.6% at 45 days out to 91.6% at the July 30 observation (6 days remaining). Within a single month, “dates decided at 45 days out” and “dates decided close-in” coexist. There is room to separate these two types on your own monthly calendar and vary the operating rules for inventory and pricing accordingly.
3. The amount of headroom left differs by segment. City hotels were already at 95.1% at 45 days out on August 8, with a gain of only +1.9pt from there. That is a different starting premise from business hotels’ 80.8% and +6.7pt. On dates near the ceiling, the question is no longer how to build volume but how to handle the last few rooms. Whether your property is near the ceiling or still has distance to it leads to an entirely different set of measures to consider.
4. In Sendai, August’s day-of-week shape differs between event and non-event weeks. July actuals showed a day-of-week spread of 97.3% on Saturdays and 85.2% on Mondays. But Wednesday August 19 stood at 79.5% at the July 30 observation (20 days remaining), still short of July’s Wednesday average of 91.8%. Reading strong Tanabata-week pace as the tone of the whole month makes it easy to misjudge the week after Obon. We suggest assessing the tone week by week.
| Time horizon | Measure | Decision trigger (figures from this article) | Objective |
|---|---|---|---|
| Today – this week (Tanabata itself) | Line up your remaining allocation for Aug 5–8 against the market’s most recent level | The market (business hotels) at the July 30 observation: Aug 5 = 91.6%, Aug 6 = 87.9%, Aug 7 = 88.8%, Aug 8 = 92.5%. If your property sits well below this, there is room to revisit how the remaining allocation is being sold | Check whether your property alone is being left behind in the close-in phase |
| Today – this week | Identify the slowest-pacing day among the four and concentrate promotional effort there | In the market, Aug 6 (Thu) is the lowest of the four days at 87.9%. If Thursday is likewise slow at your property, consider acting on Aug 6 before Aug 8 | Allocate resources to the soft day rather than the tight one |
| Within two weeks (week after Obon) | Re-assess the three weekdays of Aug 19–21 as a different tone from the Tanabata week | At the July 30 observation the market was Aug 19 = 79.5% (20 days remaining), Aug 20 = 81.5%, Aug 21 = 82.8%. The distance from July’s averages of 91.8% (Wed), 93.3% (Thu) and 92.6% (Fri) is large | Do not extrapolate a strong event week to the whole month |
| Within two weeks | For Aug 22 (Sat), check whether your remaining allocation is thicker or thinner than the market’s | The market built early: 88.0% at 45 days out → 92.2% at 30 days out → 94.7% at the July 30 observation (23 days remaining). If your property is still at a level equivalent to 45 days out, there is room to revisit how the remaining period is run | Avoid missing early-settling dates |
| Looking to next month | Build a ledger sorting your stay dates into two types: “settled at 45 days out” and “settled close-in” | In the market, Aug 29 is the settling type (91.5% at 45 days out, gain of +2.5pt), while Aug 5 is the close-in type (73.6% at 45 days out → 91.6% at the July 30 observation). This establishes the basis for running the two differently | Lay the groundwork for switching operating rules day by day |
| Looking to next month | Redraw the day-of-week base from your own actuals and overlay it on the market’s shape | In July 2026 the market showed business hotels at 97.3% on Saturdays and 85.2% on Mondays (12.1pt spread), and city hotels at 98.7% and 88.5% (10.2pt spread). If your own day-of-week spread is wider than this, suspect a factor specific to the weak days | Update the day-of-week operating calendar |
Source: Compiled by the HotelBank Editorial Team from MetroEngines Research
Summary — three yardsticks to take away
Yardstick 1: Separate the position at 45 days out from the slope that follows. Business hotels on the Tanabata closing day of August 8 started 7.2pt below ordinary Saturday August 22 (80.8% versus 88.0%) yet posted the largest gain of the nine dates, +6.7pt from 45 to 30 days out. Position and slope do not move together.
Yardstick 2: Even within one month, the timing of settlement differs by date. Saturday August 29 added only +2.5pt from 91.5% at 45 days out — essentially settled at the 45-day mark. Wednesday August 5, by contrast, moved +18.0pt, from 73.6% at 45 days out to 91.6% at the July 30 observation (6 days remaining). Running these two types under one policy loses both.
Yardstick 3: Headroom is asymmetric by segment. At 45 days out on the Tanabata closing day, business hotels stood at 80.8% and city hotels at 95.1%. When the distance to the ceiling differs, so does the effectiveness of holding inventory until close-in. Start by checking which position your property occupies, overlaid on the market curve for your own segment.
Metric Definitions Used in This Article
| Definition of estimated OCC | Occupancy on an OTA-listed inventory basis = 100 − 100 × rooms remaining as listed on OTAs ÷ total rooms. It is an estimate based on how inventory sold on OTAs is being absorbed, and its definition differs from actual room occupancy (it reads higher). This article labels it “estimated OCC (OTA-listed inventory basis).” |
| Booking curve | Based on observations from 45 days before the stay date up to the most recent reading. The scope is Miyagi, and the stay dates are August 5, 6, 7, 8, 19, 20, 21, 22 and 29, 2026. The “July 30 observation” used as a third fixed point is the cross-section of July 30, 2026, on which days remaining differ by stay date (Aug 5 = 6 days, Aug 6 = 7, Aug 7 = 8, Aug 8 = 9, Aug 19 = 20, Aug 20 = 21, Aug 21 = 22, Aug 22 = 23, Aug 29 = 30). |
| Share of properties with no confirmable listed inventory | The estimated proportion of properties for which listed inventory for the given stay date could not be confirmed on OTAs and similar channels. |
| Breakdown of N= | Business hotels: 126 properties, 17,261 rooms (125 properties, 16,975 rooms for stay date Aug 29 only). Observed properties numbered 112–120 at 45 days out, 116–124 at 30 days out, and 124–126 at the July 30 observation. City hotels: 21 properties, 2,963 rooms. Observed properties numbered 19–21 at 45 and 30 days out, and 21 at the July 30 observation. July 2026 completed-month actuals cover 120–126 business properties / 16,417–17,261 rooms and 18–21 city properties / 2,811–2,963 rooms. |
| Data as of | Data as of: August 2, 2026. Sales status and inventory change daily, so the figures in this article are a snapshot at the time of retrieval. |
Source: Compiled by the HotelBank Editorial Team from MetroEngines Research
References and Sources
| Sendai Tanabata Festival — event outline | Official site of the Sendai Tanabata Festival Association (secretariat: Sendai Chamber of Commerce and Industry) (dates: August 6–8 every year) |
| 57th Sendai Tanabata Fireworks Festival — event outline | Official site of the Sendai Tanabata Fireworks Festival (Wednesday, August 5, 2026, 19:30–20:30 scheduled; around Aobayama Park / the Hirose River banks; organizer: Sendai Junior Chamber Inc.) |
Related Reading
- 94.5% Sold 45 Days Out: Omagari Fireworks vs a Normal Akita Weekend
- Tochigi Booking Curves by Type: Resort 81.1% at T-45, Only +2.6pt Left
- Hokkaido City Hotels: Only Aug 15 Trails at 78.7% OCC, 45 Days Out
- Nagano Late-Summer Booking Curve 2026: Ryokan -11.8pt at 45 Days Out
- Hiratsuka vs Sendai Tanabata 2026: Day-Trip vs Overnight Hotel Demand