

When hotel investors add up holding costs, fixed asset tax is usually thought of as two items: land and buildings. Under Japan’s Local Tax Act, however, there are three classes of fixed assets: land, buildings and depreciable assets (Local Tax Act, Article 341, item 1). Guest room furniture, beds, bedding, commercial kitchen equipment, laundry machines, outdoor power receiving/transforming equipment, signage, exterior paving — a hotel is packed with this third taxable object, and it adds a cost every year separately from the fixed asset tax on the building. Depreciable assets are also the only class where the owner must file a return each year by January 31 declaring what they held on January 1 (Article 383 of the same Act).
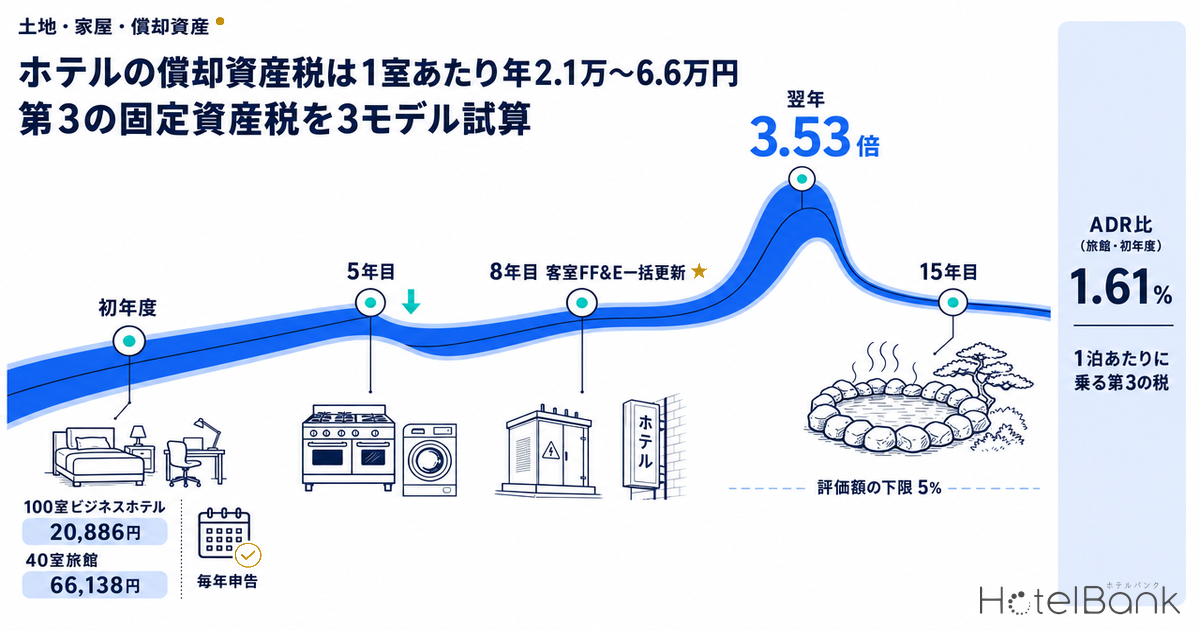
This article breaks down this “third fixed asset tax, levied every year on things that are neither land nor buildings” on a per-room basis. The bottom line: across three models — a 100-room business hotel, a 150-room city hotel and a 40-room ryokan — first-year depreciable asset tax comes to ¥20,886 to ¥66,138 per room per year. And in the year after a full replacement of guest room FF&E, the tax bill jumps 3.53x.
How this differs from our earlier coverage. Our previous articles on holding taxes and running costs covered the fixed asset tax on land and buildings, the holding cost of undeveloped hotel land, the triennial reassessment of land and building values, and other running-cost items such as statutory inspections and electricity. None of them dealt with depreciable assets — the third taxable object — on their own. That is what is new here.
Metric Definitions Used in This Article
- ADR (Average Daily Rate): Estimated settled rate (tax-excluded equivalent), calculated by applying segment-specific adjustment factors to the lowest-plan rate each property publishes on major booking sites (2 guests per room, per-room rate, tax-included). Checked against property-level results disclosed by listed hotel REITs (91 properties, most recent 3 months), the median error is about 7%. These are estimates and differ from each property’s actual settled rates and accounting figures. Area-level ADR is the median of the properties covered (the level of a typical property in the area).
- Depreciable assets: Assets other than land and buildings that can be used for business, whose depreciation is deductible as a loss or necessary expense when calculating income under the Corporation Tax Act or Income Tax Act (Local Tax Act, Article 341, item 4). Intangible fixed assets and vehicles subject to automobile tax or light vehicle tax are excluded.
- Assessed value: Acquisition cost multiplied by the residual-value rate for the asset’s useful life. In the year of acquisition a half-year of depreciation applies (1 − depreciation rate ÷ 2); from the following year (1 − depreciation rate) applies, with a floor of 5% of acquisition cost (Fixed Asset Valuation Standards, Chapter 3).
- Tax amount: Taxable base (rounded down to the nearest ¥1,000) × tax rate of 1.4% (standard rate under Local Tax Act, Article 350; rounded down to the nearest ¥100). No tax is levied if the taxable base is below ¥1.5 million (tax exemption threshold, Article 351).
- Estimates: The three models in this article are built up from assumptions and do not represent any actual property. All assumptions are disclosed in the tables at the end.
- Data sources: MetroEngines Research & Consulting; published materials from the Ministry of Internal Affairs and Communications, the National Tax Agency and the Small and Medium Enterprise Agency (checked September 9, 2026)
- — ¥20,886–¥66,138 per room per year. A “third fixed asset tax” levied every year on top of land and buildings. These are first-year amounts for a 100-room business hotel, a 150-room city hotel and a 40-room ryokan.
- — 15-year cumulative total of ¥85,961–¥308,962 per room. Despite having fewer rooms, the ryokan pays 3.6x the business hotel. The gap reflects the ratio of depreciable assets to building investment (18.3% vs 14.6%).
- — 3.53x in the year after a renovation. A full replacement of guest room FF&E resets the assessed value. Build it into the business plan as a one-year spike in NOI costs.
- — −20% to +29% versus the mid case, depending on assumptions. Asset mix matters more than the tax rate. 1.4% is only the standard rate; some municipalities set a higher rate by ordinance (Izumo City, Shimane: 1.5%).
- — Assessed value never falls below 5% of acquisition cost. Unlike the ¥1 memorandum value for national tax, the tax never disappears as long as you keep the assets (¥122,500 a year in the 100-room model).
Fixed Asset Tax Has Three Parts — Land, Buildings and Depreciable Assets
Article 341, item 1 of the Local Tax Act states that “fixed assets” collectively means land, buildings and depreciable assets. Item 4 of the same article defines depreciable assets as “assets other than land and buildings that can be used for business (excluding mining rights, fishing rights, patents and other intangible depreciable assets), whose depreciation amount or depreciation expense is included in losses or necessary expenses in calculating income under the Corporation Tax Act or Income Tax Act, other than low-cost assets and other assets specified by Cabinet Order.” The taxable object is set out in Article 342, the taxable base in Article 349-2, the tax rate in Article 350, the exemption threshold in Article 351 and the filing obligation in Article 383.
Of these three, land and buildings are assessed and taxed by the municipality on its own authority using registry data and similar records (assessment-based taxation). Depreciable assets are different: the municipality cannot know about them unless the owner files a return showing each asset’s location, type, quantity, acquisition date, acquisition cost and useful life. Filing omissions happen unintentionally, yet tax can be assessed retroactively for up to five years from the day after the statutory payment deadline (Local Tax Act, Article 17-5, paragraph 5). An oversight in the business plan can surface all at once years later.
| Taxable object | Taxation method | Basis of valuation | What it covers in a hotel | Revaluation / changes |
|---|---|---|---|---|
| Land | Assessment-based (no filing required) | Road-frontage values based on official land prices, etc. | Site and parking land | Revalued every 3 years |
| Buildings | Assessment-based (no filing required) | Replacement cost × age-based depreciation adjustment | Structure, interior fit-out, building services integrated with the building | Revalued every 3 years |
| Depreciable assets | Self-reported (every year by Jan 31) | Acquisition cost × residual-value rate (old declining-balance method) | FF&E, commercial kitchen, laundry, power receiving/transforming, signage, exterior paving | Recalculated every year (reflecting acquisitions and disposals) |
Source: Compiled by MetroEngines Research & Consulting from the Local Tax Act and Fixed Asset Valuation Standards (checked September 9, 2026)
A common stumbling block in practice is what does not count as a depreciable asset. Under the parenthetical in Article 341, item 4, vehicles subject to automobile tax or light vehicle tax are excluded. In other words, shuttle buses and limousines are outside depreciable asset tax, while large special vehicles such as snowplows and forklifts are included. Also excluded are low-cost depreciable assets under ¥100,000 expensed immediately, and assets under ¥200,000 for which three-year lump-sum depreciation was chosen. Conversely, when a small or medium-sized business filing a blue return expenses assets under ¥300,000 immediately under the Act on Special Measures Concerning Taxation, the assets must still be declared for depreciable asset tax even though they were expensed for national tax purposes. It is a classic example of local and national tax treating the same asset differently.
How Valuation Works — Half-Year Depreciation in Year One, 5% Floor
Depreciable assets are valued using the old declining-balance method. In the year of acquisition (strictly, “assets acquired during the previous year”), half a year of depreciation applies regardless of the month of acquisition; from the following year the prior year’s assessed value is multiplied by the residual-value rate. And the assessed value never falls below 5% of acquisition cost. This is a decisive difference from national tax, which allows depreciation down to a ¥1 memorandum value: for local tax, 5% of acquisition cost stays in the taxable base for as long as you hold the asset.
| Useful life | Depreciation rate | Residual rate (acquired in prior year) | Residual rate (acquired before prior year) | Typical hotel assets |
|---|---|---|---|---|
| 2 yrs | 0.684 | 0.658 | 0.316 | Tableware and kitchen utensils (ceramic/glass) |
| 3 yrs | 0.536 | 0.732 | 0.464 | Bedding, curtains, carpets for hospitality use; signboards and neon signs |
| 4 yrs | 0.438 | 0.781 | 0.562 | Personal computers (PMS terminals, etc.) |
| 5 yrs | 0.369 | 0.815 | 0.631 | Hospitality-use furniture and lounge sets, TVs and audio equipment |
| 6 yrs | 0.319 | 0.840 | 0.681 | Cooling/heating units, refrigerators and washing machines, storage-battery power equipment |
| 8 yrs | 0.250 | 0.875 | 0.750 | Beds, interior decorations (non-metal) |
| 10 yrs | 0.206 | 0.897 | 0.794 | Lodging-industry equipment (machinery), asphalt paving |
| 13 yrs | 0.162 | 0.919 | 0.838 | Bathhouse-industry equipment, HVAC (refrigerator output of 22kW or less) |
| 15 yrs | 0.142 | 0.929 | 0.858 | Electrical equipment (incl. lighting), water supply/drainage and sanitary equipment, concrete paving |
| 20 yrs | 0.109 | 0.945 | 0.891 | Gardens and landscaping |
Source: Compiled by MetroEngines Research & Consulting from the Fixed Asset Valuation Standards (residual-value rates) and Appended Tables 1 and 2 of the Ministerial Ordinance on Useful Lives of Depreciable Assets
Here is a concrete example. If guest room furniture with an acquisition cost of ¥1 million (other hospitality-use furniture, useful life 5 years) is acquired in January, its assessed value the following fiscal year is acquisition cost × 0.8155 (half-year depreciation at a rate of 0.369; shown rounded to 0.815 in the table above) = ¥815,500. In year 2 it is ¥815,500 × 0.631 = ¥514,580. Repeating the calculation gives ¥51,475 in year 7, and in year 8 the calculated value drops below the ¥50,000 floor, so it is fixed at 5% of acquisition cost, or ¥50,000. That ¥50,000 stays in the taxable base permanently until the furniture is disposed of.
Source: Estimates by MetroEngines Research & Consulting based on the Fixed Asset Valuation Standards
This is where business plans go wrong. For national tax, depreciation expense ends after five years, but for local tax the taxable base remains at 5% forever. Fixed asset tax keeps being levied on assets whose depreciation expense has already reached zero — and this asymmetry weighs on NOI from around the tenth year of operation onward.
Where Buildings End and Depreciable Assets Begin — Hotel Kitchens and Laundries Fall on the Asset Side
Even if building services are depreciated together with the building for tax accounting purposes, the portions not included in the building’s valuation under the Local Tax Act must be declared separately as depreciable assets. The line is drawn according to classification tables published by each municipality, and for hotels the key category is “service equipment provided at customers’ request.” Chigasaki City’s classification table treats kitchen equipment that is “service equipment provided at customers’ request (restaurants, hotels, department stores, etc.)” as depreciable assets, and likewise treats laundry equipment consisting of “washers, spin dryers, dryers and similar machines, and service equipment provided at customers’ request (hotels, etc.)” as depreciable assets. Nishinomiya City similarly classifies “service equipment of hotels, restaurants, hospitals, etc.” as depreciable assets.
In other words, the same kitchen equipment may be included in the building valuation if it serves an employee cafeteria, whereas kitchen equipment in a breakfast venue or restaurant serving hotel guests is a depreciable asset. Because a hotel is essentially a bundle of such “service equipment,” its share of depreciable assets is structurally high.
| Equipment category | Valued as part of the building | Declared as depreciable assets |
|---|---|---|
| Kitchen equipment | Equipment other than that listed on the right | Service equipment provided at customers’ request (hotels, restaurants, etc.); kitchen equipment in dormitories, hospitals, employee cafeterias, etc. |
| Laundry equipment | Equipment other than that listed on the right | Washers, spin dryers, dryers and similar machines; service equipment of hotels, etc. |
| Air conditioning | Equipment other than wall-mounted room air conditioners (central HVAC, etc.) | Wall-mounted room air conditioners, certain business-specific equipment |
| Electrical equipment | Indoor lighting outlets and fixtures, lightning protection, fire alarm systems | Power receiving/transforming equipment, backup power (generators, storage batteries), central monitoring, all outdoor equipment, power service entrance, LAN equipment |
| Water supply, drainage and sanitary | Indoor piping, elevated and receiving water tanks, pumps, etc.; all sanitary fixtures | Outdoor equipment, service connection work, certain business-specific equipment, local hot-water systems (electric water heaters, water boilers) |
| Conveyance equipment | Elevators, escalators, dumbwaiters, etc. | Factory belt conveyors, etc. |
| Other | — | Advertising towers, neon signs, lettered signs, projecting signs, parking equipment, bicycle parking, simple partitions, curtains and blinds, etc. |
| Exterior works | — | All works (gates, fences, landscaping, etc.) |
Source: Compiled by MetroEngines Research & Consulting from Chigasaki City, “Classification of Buildings and Depreciable Assets for Building Services,” and Nishinomiya City, “Classification of Buildings and Depreciable Assets” (where the building and equipment have the same owner)
However, municipalities apply this line differently. For example, the treatment of shared entrance intercom systems carries different notes from city to city, and some cities include exterior works that are “structurally integrated with the building” in the building. Use the table above as a reference for typical classification patterns, and in practice always confirm with the property tax division of the municipality where the property is located.
Another point investors often overlook is fit-out installed by tenants. Building fixtures installed by someone other than the building owner can be deemed depreciable assets — even if they form part of the building — with the installer deemed the owner for tax purposes (Local Tax Act, Article 343, paragraph 10). In lease structures where the operator, as tenant, invests in FF&E and interior fit-out, depreciable asset tax arises on the operator’s side, separately from the building tax borne by the owner. When setting the economic terms of a master lease or operating lease, the contract should state clearly who bears this cost.
Three Model Estimates — ¥20,886 to ¥66,138 per Room per Year
Now to quantify it. We built three models, stacked up each asset by useful life and calculated the tax from year 1 through year 15. For construction costs we used the per-room construction cost ranges by hotel type from our earlier research, and carved out the portion accounted for by depreciable assets (FF&E, business equipment, signage and exterior works).
| Model | Rooms | Construction cost per room | Building investment | Acquisition cost of depreciable assets | Per room | Share of building investment |
|---|---|---|---|---|---|---|
| A. Business hotel (limited service) | 100 | ¥12 mn | ¥1.20 bn | ¥175,000,000 | ¥1,750,000 | 14.6% |
| B. City hotel (full service) | 150 | ¥25 mn | ¥3.75 bn | ¥560,000,000 | ¥3,733,333 | 14.9% |
| C. Ryokan (hot spring, two meals included) | 40 | ¥30 mn | ¥1.20 bn | ¥219,200,000 | ¥5,480,000 | 18.3% |
Source: Estimates by MetroEngines Research & Consulting (assumptions disclosed in the tables at the end)
Depreciable assets account for 14.6% of building investment at the business hotel and 14.9% at the city hotel, but a higher 18.3% at the ryokan. That is because “service equipment” — filtration, circulation and heating systems for large public and open-air baths, commercial kitchens for kaiseki cuisine, hot-spring heating equipment — is heavy relative to the number of rooms. Even at just 40 rooms, the ryokan holds ¥220 million in depreciable assets alone.
Source: Estimates by MetroEngines Research & Consulting (tax rate 1.4%; taxable base rounded down to ¥1,000, tax rounded down to ¥100)
| Model | Year 1 | Year 3 | Year 5 | Year 10 | Year 15 | 15-yr total / room |
|---|---|---|---|---|---|---|
| A. 100-room business hotel Annual tax | ¥2,088,600 | ¥1,086,200 | ¥616,800 | ¥230,100 | ¥143,500 | — |
| Per room | ¥20,886 | ¥10,862 | ¥6,168 | ¥2,301 | ¥1,435 | ¥85,961 |
| B. 150-room city hotel Annual tax | ¥6,586,700 | ¥3,224,800 | ¥1,758,400 | ¥657,600 | ¥441,400 | — |
| Per room | ¥43,911 | ¥21,499 | ¥11,723 | ¥4,384 | ¥2,943 | ¥170,852 |
| C. 40-room ryokan Annual tax | ¥2,645,500 | ¥1,492,000 | ¥942,500 | ¥396,700 | ¥216,300 | — |
| Per room | ¥66,138 | ¥37,300 | ¥23,562 | ¥9,918 | ¥5,408 | ¥308,962 |
Source: Estimates by MetroEngines Research & Consulting (standard tax rate of 1.4% applied)
First-year tax per room is ¥20,886 for the business hotel, ¥43,911 for the city hotel and ¥66,138 for the ryokan. Over 15 years the ryokan’s cumulative total reaches ¥308,962 per room, 3.6x the business hotel’s ¥85,961. Even with fewer rooms, the ryokan format carries the heaviest per-room depreciable asset tax burden. It is a structural difference that business plans easily miss.
Next, we break down first-year tax by asset. At the 100-room business hotel, the largest contributors are, perhaps surprisingly, not guest room FF&E but power receiving/transforming and outdoor electrical equipment (12.5%) and commercial kitchen equipment (12.0%). Assets with long useful lives depreciate slowly, so their assessed values stay high.
Source: Estimates by MetroEngines Research & Consulting (100-room business hotel, year 1)
Moving the Assumptions — Three Scenarios and a Two-Way Sensitivity
The figures so far are a single estimate built on a provisional, typical asset mix for each hotel type. If you put these numbers into a real business plan, you will also want to know how much the tax swings when the assumptions move. Two variables drive most of the range: the ratio of depreciable assets to building investment and the tax rate of the municipality where the property is located.
First, three scenarios. The mid case is this article’s base assumptions (depreciable asset ratio of 14.6% for A, 14.9% for B and 18.3% for C, standard tax rate of 1.4%). The optimistic case lowers the acquisition cost of depreciable assets by 20% from the base at the standard rate; the pessimistic case raises it by 20% and assumes a location in a municipality with an above-standard rate of 1.5%.
| Model | Optimistic Ratio −20% / 1.4% |
Mid Base case / 1.4% |
Pessimistic Ratio +20% / 1.5% |
|---|---|---|---|
| A. 100-room business hotel | ¥16,709 ¥68,769 | ¥20,886 ¥85,961 | ¥26,853 ¥110,522 |
| B. 150-room city hotel | ¥35,129 ¥136,680 | ¥43,911 ¥170,852 | ¥56,457 ¥219,669 |
| C. 40-room ryokan | ¥52,910 ¥247,168 | ¥66,138 ¥308,962 | ¥85,032 ¥397,242 |
Source: Estimates by MetroEngines Research & Consulting (top = year-1 per room; bottom = 15-year cumulative per room; assumptions disclosed in the tables at the end)
Between the optimistic and pessimistic cases, first-year tax per room ranges from ¥16,709 to ¥26,853 for the business hotel, ¥35,129 to ¥56,457 for the city hotel and ¥52,910 to ¥85,032 for the ryokan — roughly −20% to +29% versus the mid case. The proportional range is the same on a 15-year cumulative basis. In a business plan, check where you sit within this band against your fixed asset ledger and local ordinance before adopting the mid-case figure.
Next, a two-way grid combining those two variables. For the 100-room business hotel (building investment of ¥1.20 billion), rows show the ratio of depreciable assets to building investment, columns show the tax rate, and each cell shows first-year tax per room.
| Share of building investment | Acquisition cost per room |
1.4% Standard rate |
1.5% | 1.6% | 1.7% |
|---|---|---|---|---|---|
| 10.0% | ¥1,200,000 | ¥14,322 | ¥15,345 | ¥16,368 | ¥17,391 |
| 12.0% | ¥1,440,000 | ¥17,186 | ¥18,414 | ¥19,641 | ¥20,869 |
| 14.6% (base case) | ¥1,750,000 | ¥20,886 | ¥22,378 | ¥23,869 | ¥25,361 |
| 17.0% | ¥2,040,000 | ¥24,347 | ¥26,086 | ¥27,825 | ¥29,564 |
| 20.0% | ¥2,400,000 | ¥28,644 | ¥30,690 | ¥32,736 | ¥34,782 |
Source: Estimates by MetroEngines Research & Consulting (shaded cell is this article’s base case; valuation by the old declining-balance method with half-year depreciation in the acquisition year; taxable base rounded down to ¥1,000, tax rounded down to ¥100)
The top-left of the grid (10.0% ratio, standard 1.4% rate) gives ¥14,322 per room; the bottom-right (20.0% ratio, 1.7%) gives ¥34,782 per room. For the same 100-room hotel with ¥1.20 billion of building investment, the combination of asset mix and municipality alone opens a 2.4x gap in first-year tax. Moving the ratio by one step (about 2–3pt) has roughly three times the effect of moving the tax rate by 0.1pt, so asset mix matters more than the tax rate. Deciding FF&E and business equipment specifications at the design stage also decides the next 15 years of holding tax.
ADR Equivalent — ¥72 to ¥302 per Room Night; 1.6% of ADR for the Ryokan
Next we convert the tax into a per-night figure: we set an occupancy assumption and divided by the number of room nights sold per year. ADR is the median of our estimated settled ADR (closed past months) by hotel type.
| Model | Estimated settled ADR | Occupancy (assumption) | Year 1 / night | % of ADR | Year 5 / night | % of ADR |
|---|---|---|---|---|---|---|
| A. 100-room business hotel | ¥14,098 | 80% | ¥72 | 0.51% | ¥21 | 0.15% |
| B. 150-room city hotel | ¥26,943 | 75% | ¥160 | 0.60% | ¥43 | 0.16% |
| C. 40-room ryokan | ¥18,710 | 60% | ¥302 | 1.61% | ¥108 | 0.58% |
ADR source: MetroEngines Research & Consulting (estimated settled ADR, monthly medians for September 2025 – August 2026. A = Tokyo business hotels, N=914 properties; B = Tokyo city hotels, N=107 properties; C = Shizuoka ryokan, N=450 properties / each N is the median of monthly sample sizes)
The business hotel’s first-year 0.51% may look small in an NOI discussion. But the ryokan’s first-year 1.61% is not negligible. Of an ADR of ¥18,710, about ¥302 per night goes to depreciable asset tax, separately from the fixed asset tax on the building. For ryokan, whose GOP margins are thin to begin with, this adds up enough to move yields at the first decimal place.
And don’t forget the effect of the 5% floor. For the 100-room business hotel’s ¥175 million in depreciable assets, the floor is ¥8,750,000, which translates into ¥122,500 in tax a year (¥1,225 per room), payable indefinitely as long as that group of assets is held. It is ¥392,000 a year (¥2,613 per room) for the 150-room city hotel and ¥153,400 a year (¥3,835 per room) for the 40-room ryokan. Assuming in the terminal period of a DCF that “depreciable asset tax converges to zero” is a mistake.
The Year After a Renovation, the Tax Bill Jumps 3.53x
Depreciable asset tax bites in a business plan not in normal years but in the year after a renovation. When guest room FF&E is replaced wholesale, the old assets are disposed of and the new assets re-enter the taxable base at acquisition cost. That creates a spike.
Using the 100-room business hotel model, we estimated a case where guest room FF&E (room furniture, beds, TVs, bedding, carpets, refrigerators, etc.; original acquisition cost ¥52,000,000) is fully replaced in year 8. Allowing for construction cost inflation, the replacement cost was set at 1.20x the original, or ¥62,400,000 (¥624,000 per room).
Source: Estimates by MetroEngines Research & Consulting (100-room business hotel, full replacement of guest room FF&E in year 8)
Without the replacement, year-9 tax would have fallen to ¥265,500. With it, tax jumps to ¥936,100, or 3.53x — from ¥2,655 to ¥9,361 per room. Business plans that consider a major renovation must build into cash flow not only construction costs and ADR lift but also the increase in depreciable asset tax from the following year onward.
Also note the third line in the chart above — the case where the disposal is not reported. If the old assets are physically removed but not dropped from the return, their assessed values stay in the taxable base at the 5% floor. The excess burden from these “ghost assets” is ¥36,400 a year in this model, or ¥266,000 over 15 years (¥2,660 per room). The amount is not large, but the trouble is that it never stops unless the assets are removed from the filing, and it piles up with every renovation.
The practical fix is simple: prepare a disposal list at the same time the renovation is carried out, and reflect it in the January 31 filing the following year. It helps to make reconciling the contractor’s cost breakdown against the fixed asset ledger one of the closing items of every renovation project.
Leasing vs Ownership Changes Who Must File
Who files and who pays? The principle is that the owner is taxed (Local Tax Act, Article 343, paragraph 1). From there, three patterns emerge.
| Type | Filing and taxpayer | Treatment in the business plan |
|---|---|---|
| Owned | The hotel owner/operator itself | Recorded in NOI as a direct cost, as in this article’s estimates |
| Leased (including non-title-transfer finance leases) | In principle, the leasing company (as owner) | No direct tax burden, but it is passed through in lease payments. Without checking the breakdown of lease payments, costs can be double-counted or under-counted |
| Installment sales with retention of title | Deemed jointly owned by seller and buyer (Article 342, paragraph 3), but in practice the buyer is treated as the taxpayer | Filed and recorded by the buyer |
| Tenant-installed fit-out | The tenant that installed it (Article 343, paragraph 10) | A cost on the operator’s side. State who bears it in the lease agreement |
Source: Compiled by MetroEngines Research & Consulting from the Local Tax Act and “Handling of the Enforcement of the Local Tax Act (Municipal Taxes),” Chapter 3 (checked September 9, 2026)
Leasing FF&E means no depreciable asset tax on your own books, but the cost is included in the lease payments. When assessing NOI, you cannot compare against an ownership case without separating out the fixed-asset-tax equivalent embedded in lease payments. When comparing acquisition structures, accuracy improves if you request documents such as a fixed asset tax reduction calculation confirmed by the Japan Leasing Association.
When the Taxable-Base Special Measure Applies — Advanced Equipment Introduction Plans
A representative way to reduce depreciable asset tax is the special measure on the taxable base for equipment covered by an approved Advanced Equipment Introduction Plan under the Act on Enhancement of Small and Medium-sized Enterprises Business (one of the so-called “Wagamachi” local special measures). Under the FY2025 tax reform, eligibility now covers equipment acquired between April 1, 2025 and March 31, 2027.
| Item | Details |
|---|---|
| Eligible parties | Small and medium-sized businesses with an approved Advanced Equipment Introduction Plan (corporations with capital of ¥100 million or less, sole proprietors with 1,000 or fewer employees, etc.; excluding subsidiaries of large companies). Note that for the “SME” definition required for plan approval, ryokan/hotel businesses must have capital of ¥50 million or less, or 200 or fewer employees, as set out by industry |
| Reduction | Commitment to wage increases of 1.5% or more: taxable base reduced to one-half for 3 years Commitment to wage increases of 3% or more: taxable base reduced to one-quarter for 5 years |
| Eligible equipment and minimum acquisition cost | Machinery ¥1.6 mn or more / measuring and testing tools ¥300,000 or more / tools, furniture and fixtures ¥300,000 or more / building services ¥600,000 or more (excluding those functioning as one with the building) |
| Other requirements | An investment plan confirmed by an approved business innovation support organization with an average annual return on investment of 5% or more; used directly for production, sales or similar activities; not second-hand |
| Deadline | Equipment acquired by March 31, 2027 |
Source: Compiled by MetroEngines Research & Consulting from the Small and Medium Enterprise Agency, “Support Through the Advanced Equipment Introduction Scheme,” and published materials from Kakogawa City and Yokohama City (checked September 9, 2026). Applies only in municipalities whose basic plan for promoting introduction has been approved, and the scope of eligible equipment may be limited by the municipality’s plan
In the 100-room business hotel model, if commercial kitchen equipment (¥20,000,000), laundry equipment (¥6,000,000) and PMS and other terminals (¥9,000,000) — ¥35,000,000 in total — qualified for the special measure, then with a 1.5% wage-increase commitment the cumulative reduction over three years would be about ¥472,600 (¥4,726 per room).
Source: Estimates by MetroEngines Research & Consulting (eligible equipment ¥35,000,000; assumes a wage-increase commitment of 1.5% or more and a 1/2 reduction for 3 years)
To avoid confusion, one more point. The SME Business Enhancement Tax Incentive (immediate depreciation or a tax credit of 10% of acquisition cost, available until March 31, 2027, with the lodging industry among the designated businesses) is a national tax measure and has no effect on depreciable asset tax. Fixed asset tax allows no reduction entries, special depreciation or accelerated depreciation, so even if immediate depreciation has brought the corporate-tax book value down to ¥1, the depreciable asset’s assessed value is calculated independently using the residual-value rate for its useful life. Fully expensing an asset for national tax does not bring local tax to zero. The national-tax framework for special depreciation of hotel buildings is a separate topic.
1.4% Is Only the “Standard Rate” — Some Municipalities Charge More
The 1.4% set out in Article 350 of the Local Tax Act is merely the standard rate, and municipalities may set a higher rate by ordinance. Izumo City in Shimane Prefecture, for instance, states in its published materials that its tax rate on depreciable assets is 1.5%. When comparing candidate sites, do not finalize numbers estimated at the standard rate. The tax rate is not the only running cost that varies by municipality; we have examined the same structure for waste disposal fees (a 2.6x gap between municipalities) and hotel water and sewer costs, which vary 2.1x by municipality.
| Tax rate | Year-1 annual tax | Per room | Difference vs standard rate |
|---|---|---|---|
| 1.4% (standard rate) | ¥2,088,600 | ¥20,886 | — |
| 1.5% | ¥2,237,800 | ¥22,378 | +¥149,200 |
| 1.6% | ¥2,386,900 | ¥23,869 | +¥298,300 |
| 1.7% | ¥2,536,100 | ¥25,361 | +¥447,500 |
Source: Estimates by MetroEngines Research & Consulting (100-room business hotel, based on a year-1 taxable base of ¥149,187,000). The applicable rate depends on the ordinance of the municipality where the property is located
A word on the exemption threshold as well. No depreciable asset tax is levied if the taxable base is below ¥1.5 million (Article 351). However, a hotel or ryokan is very unlikely to fall below it. For assets with a 5-year useful life, first-year value falls below the threshold only if acquisition cost is under ¥1,839,362; assuming guest room FF&E of ¥650,000 per room, the break-even point is equivalent to 2.8 rooms. Lodging facilities with three or more rooms can generally be assumed to be subject to filing and tax.
1,500 to 2,000 New Properties Enter the Filing Obligation Every Year
The filing obligation arises the moment a property opens. Counting new openings by year within our coverage gives 1,723 properties in 2022 (average 30 rooms), 2,012 in 2023 (average 22 rooms), 1,979 in 2024 (average 20 rooms), 1,745 in 2025 (average 24 rooms) and 1,494 in 2026 (average 25 rooms). Every year, 1,500 to 2,000 properties — roughly 37,000 to 52,000 rooms — are newly added to the pool of taxpayers who must file by January 31.
Source: MetroEngines Research & Consulting (based on confirmed listings on major booking sites, N=8,953 properties / 2022–2026 total)
* New opening counts are based on confirmed listings on major booking sites. Listings appear several months before opening, so counts for recent months and years will rise as further listings are reflected. In particular, the 1,494 properties for 2026 are expected to increase with additions during the year and should be treated as a lower bound of what is observed so far. Also, 719 (48.1%) of 2026 openings are vacation rental homes, some of which hold depreciable assets below the exemption threshold.
Geographically, the top prefectures for 2026 openings are Hokkaido (149), Tokyo (90), Okinawa (90), Shizuoka (84) and Kyoto (73). The heavy weighting of resort areas such as Hokkaido, Okinawa, Shizuoka, Nagano and Yamanashi reflects the large supply of vacation rentals and cottages. Small resort properties hold fewer depreciable assets per property, but their operators often lack a dedicated tax function, so their risk of filing omissions is relatively high.
Source: MetroEngines Research & Consulting (2026 openings based on confirmed listings on major booking sites, top 15 prefectures)
Building It Into Business Plan NOI — An 8-Point Checklist
| Check item | What to look at |
|---|---|
| 1. Buildings vs depreciable assets | Sort the contractor’s cost breakdown against the classification table of the municipality where the property is located. Assume kitchens, laundry, power receiving/transforming equipment, exterior works and signage fall under depreciable assets |
| 2. Applicable tax rate | Check the ordinance to see whether the municipality applies an above-standard rate. Going from 1.4% to 1.5% adds about ¥150,000 a year in the 100-room model |
| 3. First-year peak | The first year of operation carries the heaviest burden, coinciding with the period of thin cash flow around opening. Build that in |
| 4. Renovation-year increase | Tax jumps in the year after a major renovation — 3.53x in this model. Draw the tax curve together with the renovation plan |
| 5. Disposal filing | Reflect assets removed in a renovation in the following January 31 filing. If you forget, tax continues indefinitely at the 5% floor |
| 6. Floor in the terminal period | Assessed value has a floor of 5% of acquisition cost. Do not let depreciable asset tax converge to zero in the later years of a DCF |
| 7. Procurement structure | For leased assets the leasing company is the taxpayer. Separate out the tax equivalent included in lease payments and compare with the ownership case |
| 8. Eligibility for special measures | Check whether an Advanced Equipment Introduction Plan (for assets acquired by March 31, 2027) can be approved before making the capex decision. Approval cannot be obtained after the fact |
Source: Compiled by MetroEngines Research & Consulting
Note on regulations: Tax rates, exemption thresholds, taxable-base special measures and the classification of buildings and depreciable assets all vary by municipality and are subject to legislative change. This article is based on primary sources as of September 9, 2026. In practice, always confirm with the property tax division of the municipality where the property is located (in Tokyo’s 23 wards, the Metropolitan Tax Office). The three models in this article are estimates built up from assumptions and do not represent any actual property.
Full List of Estimate Assumptions
The estimates in this article are built up from the assumptions below. They are not figures for any actual property but models that provisionally assume a typical asset mix for each hotel type. So that readers can recalculate using their own fixed asset ledgers, we disclose the useful life and acquisition cost of every asset.
Model A: 100-room business hotel (limited service) (depreciable assets total ¥175,000,000 / ¥1,750,000 per room)
| Area | Asset | Useful life | Acquisition cost |
|---|---|---|---|
| Guest rooms | Guest room furniture (desks, chairs, nightstands, etc. / hospitality use) | 5 yrs | ¥18,000,000 |
| Guest rooms | Beds (frames and mattresses) | 8 yrs | ¥15,000,000 |
| Guest rooms | In-room individual AC (wall-mounted room air conditioners) | 6 yrs | ¥13,000,000 |
| Guest rooms | Guest room TVs and audio equipment | 5 yrs | ¥5,500,000 |
| Guest rooms | Bedding, curtains and other textiles | 3 yrs | ¥5,500,000 |
| Guest rooms | Guest room carpets (hospitality-use floor coverings) | 3 yrs | ¥4,500,000 |
| Guest rooms | Refrigerators, electric kettles and other electrical appliances | 6 yrs | ¥3,500,000 |
| Common areas | Power receiving/transforming and outdoor electrical equipment | 15 yrs | ¥20,000,000 |
| Common areas | Commercial kitchen equipment (breakfast venue) | 10 yrs | ¥20,000,000 |
| Common areas | Large public bath and sauna equipment | 13 yrs | ¥12,000,000 |
| Common areas | Exterior works and parking paving (asphalt) | 10 yrs | ¥14,000,000 |
| Common areas | Lobby and common-area furniture (hospitality use) | 5 yrs | ¥12,000,000 |
| Common areas | In-house LAN, Wi-Fi, security cameras, PA system | 6 yrs | ¥12,000,000 |
| Common areas | PMS, front desk terminals, guest room lock system | 4 yrs | ¥9,000,000 |
| Common areas | Laundry equipment (washers and dryers) | 6 yrs | ¥6,000,000 |
| Common areas | Signboards and signage | 3 yrs | ¥5,000,000 |
Model B: 150-room city hotel (full service) (depreciable assets total ¥560,000,000 / ¥3,733,333 per room)
| Area | Asset | Useful life | Acquisition cost |
|---|---|---|---|
| Guest rooms | Guest room furniture (hospitality use) | 5 yrs | ¥57,000,000 |
| Guest rooms | Beds (frames and mattresses) | 8 yrs | ¥39,000,000 |
| Guest rooms | Bedding, curtains and other textiles | 3 yrs | ¥14,250,000 |
| Guest rooms | Guest room TVs and audio equipment | 5 yrs | ¥13,500,000 |
| Guest rooms | Guest room carpets (hospitality-use floor coverings) | 3 yrs | ¥12,000,000 |
| Guest rooms | Refrigerators and other electrical appliances | 6 yrs | ¥9,000,000 |
| Guest rooms | Interior decorations | 8 yrs | ¥8,250,000 |
| Common areas | Commercial kitchen equipment (restaurants and banquets) | 10 yrs | ¥90,000,000 |
| Common areas | Banquet hall and restaurant furniture and fixtures (hospitality use) | 5 yrs | ¥65,000,000 |
| Common areas | Power receiving/transforming equipment and backup power (generator) | 15 yrs | ¥60,000,000 |
| Common areas | Banquet hall audio, lighting and video equipment | 5 yrs | ¥35,000,000 |
| Common areas | Lobby and common-area furniture (hospitality use) | 5 yrs | ¥30,000,000 |
| Common areas | In-house LAN, security cameras, PA system | 6 yrs | ¥25,000,000 |
| Common areas | Exterior works and paving | 10 yrs | ¥25,000,000 |
| Common areas | PMS, POS and terminals | 4 yrs | ¥20,000,000 |
| Common areas | Tableware and kitchen utensils (ceramic/glass) | 2 yrs | ¥18,000,000 |
| Common areas | Laundry equipment | 6 yrs | ¥15,000,000 |
| Common areas | Storage-battery power equipment | 6 yrs | ¥12,000,000 |
| Common areas | Signboards and signage | 3 yrs | ¥12,000,000 |
Model C: 40-room ryokan (hot spring, two meals included) (depreciable assets total ¥219,200,000 / ¥5,480,000 per room)
| Area | Asset | Useful life | Acquisition cost |
|---|---|---|---|
| Guest rooms | Guest room furniture (low tables, Japanese-style furniture, etc. / hospitality use) | 5 yrs | ¥12,800,000 |
| Guest rooms | In-room open-air bath equipment (select rooms) | 13 yrs | ¥12,000,000 |
| Guest rooms | Bedding, yukata, floor cushions and other textiles | 3 yrs | ¥5,600,000 |
| Guest rooms | Guest room TVs and audio equipment | 5 yrs | ¥2,800,000 |
| Guest rooms | Carpets and other floor coverings (hospitality use) | 3 yrs | ¥2,400,000 |
| Guest rooms | Refrigerators, electric hot-water pots and other electrical appliances | 6 yrs | ¥1,600,000 |
| Common areas | Large public bath and open-air bath equipment (filtration, circulation, heating) | 13 yrs | ¥38,000,000 |
| Common areas | Commercial kitchen equipment (kaiseki cuisine) | 10 yrs | ¥32,000,000 |
| Common areas | Power receiving/transforming equipment and hot-spring heating ancillary equipment | 15 yrs | ¥25,000,000 |
| Common areas | Banquet hall and dining room furniture and fixtures (hospitality use) | 5 yrs | ¥18,000,000 |
| Common areas | Tableware and kitchen utensils (ceramic/glass) | 2 yrs | ¥12,000,000 |
| Common areas | Gardens and landscaping | 20 yrs | ¥12,000,000 |
| Common areas | Lobby and lounge furniture (hospitality use) | 5 yrs | ¥12,000,000 |
| Common areas | Laundry equipment | 6 yrs | ¥8,000,000 |
| Common areas | In-house LAN and security cameras | 6 yrs | ¥8,000,000 |
| Common areas | Exterior works and paving (asphalt) | 10 yrs | ¥8,000,000 |
| Common areas | PMS and terminals | 4 yrs | ¥5,000,000 |
| Common areas | Signboards and signage | 3 yrs | ¥4,000,000 |
Source: Estimates by MetroEngines Research & Consulting. Per-room construction cost assumptions are based on ranges by hotel type from our earlier research (including per-tsubo costs based on the MLIT Statistics on Building Construction Starts)
| Common assumption | Setting and rationale |
|---|---|
| Tax rate | 1.4% (standard rate under Local Tax Act, Article 350). 1.5–1.7% also shown in the sensitivity analysis |
| Valuation method | Old declining-balance method. Acquisition year: (1 − depreciation rate ÷ 2); subsequent years: (1 − depreciation rate). Floor of 5% of acquisition cost (Fixed Asset Valuation Standards, Chapter 3) |
| Rounding | Taxable base rounded down to ¥1,000; tax rounded down to ¥100 |
| Useful life | Per Appended Tables 1 and 2 of the Ministerial Ordinance on Useful Lives of Depreciable Assets |
| Acquisition timing | All assets deemed acquired in a lump sum during the year before opening; the opening fiscal year is treated as tax year 1 |
| Taxable-base special measures | Not applied in the base estimates (the special-measure case is estimated in a separate section) |
| Renovation scenario | Guest room FF&E (originally ¥52,000,000) fully replaced in year 8. Replacement cost 1.20x the original. Old assets disposed of |
| Occupancy | A = 80%, B = 75%, C = 60% (all are estimate assumptions, not our estimated occupancy rates) |
| ADR | Our estimated settled ADR (monthly medians, September 2025 – August 2026). A = Tokyo business hotels ¥14,098 (N=914 properties), B = Tokyo city hotels ¥26,943 (N=107 properties), C = Shizuoka ryokan ¥18,710 (N=450 properties). Each N is the median of monthly sample sizes |
Source: MetroEngines Research & Consulting
Summary — Putting the Third Fixed Asset Tax Into the Plan
Depreciable asset tax is levied every year, separately from fixed asset tax on land and buildings. In our three-model estimate, first-year tax ranges from ¥20,886 per room (100-room business hotel) to ¥66,138 (40-room ryokan). Over 15 years the ryokan reaches ¥308,962 per room, 3.6x the business hotel. On a per-night basis, it takes up 1.61% of ADR at the ryokan in year one.
This tax tends to slip out of plans for three reasons. First, it is confused with fixed asset tax on the building and missed on both counts. Second, the 3.53x spike in the year after a major renovation gets buried in discussions of construction costs and ADR lift. Third, because of the 5% floor on assessed value, the tax alone keeps running forever after depreciation expense has reached zero.
Put the other way, simply addressing these three points makes a business plan more accurate: sort buildings from depreciable assets using the local classification table, confirm the applicable rate in the ordinance, draw the tax curve together with the renovation plan, and make the disposal filing a closing item of every renovation. Advanced Equipment Introduction Plans cover assets acquired by March 31, 2027, and approval must be obtained before the investment decision. Whether you are developing, acquiring or underwriting, this is an area where there is still room to build it in now.
Related Articles
- Hotel Water & Sewer Costs Vary 2.1x by Municipality: ¥7.85mn NOI Gap
- Hotels at Year 10: The Renovation Gap Is +13.6% Below 100 Rooms
References and Sources
■ Laws and regulations (checked: September 9, 2026)
- Local Tax Act: Article 341 (definitions of terms relating to fixed asset tax), Article 342 (taxable objects), Article 343 (taxpayers), Article 349-2 (taxable base of fixed asset tax on depreciable assets), Article 350 (tax rate), Article 351 (exemption threshold), Article 383 (filing of fixed assets), Article 17-5 (time limits on corrections and determinations)
- Fixed Asset Valuation Standards, Chapter 3: Depreciable Assets (Ministry of Internal Affairs and Communications notice) — Ministry of Internal Affairs and Communications publication
- Ministerial Ordinance on Useful Lives of Depreciable Assets, Appended Table 1 (tangible depreciable assets other than machinery and equipment) and Appended Table 2 (machinery and equipment) — National Tax Agency useful life tables
- Act on Enhancement of Small and Medium-sized Enterprises Business (Advanced Equipment Introduction Plans) — Small and Medium Enterprise Agency, “Support Through the Advanced Equipment Introduction Scheme”
- Small and Medium Enterprise Agency, “SME Business Enhancement Tax Incentive” (national tax; available until March 31, 2027)
■ Municipal publications (classification of buildings and depreciable assets, valuation, tax rates)
- Chigasaki City, “Classification of Buildings and Depreciable Assets for Building Services”
- Nishinomiya City, “Classification of Buildings and Depreciable Assets”
- Fujisawa City, “Calculating the Assessed Value and Tax on Depreciable Assets”
- Takasaki City, “Valuation and Tax Calculation” (comparison of fixed asset tax and national tax treatment)
- Kobe City, “Valuation Method for Depreciable Assets”
- Tama City, “Laws and Regulations on Fixed Asset Tax (Depreciable Assets)” (statutory basis; taxpayer for leased assets)
- Izumo City, “How Depreciable Assets Are Taxed” (example of a 1.5% rate)
- Kakogawa City, “Applying for Approval of Advanced Equipment Introduction Plans and the Fixed Asset Tax Special Measure (from April 1, 2025)”
- Yokohama City, “Special Measure on the Taxable Base of Fixed Asset Tax for New Equipment Acquired Under Advanced Equipment Introduction Plans”
■ Data sources
Regulations and statutory provisions are based on e-Gov Laws and Regulations Search and the Ministry of Internal Affairs and Communications’ “Fixed Asset Valuation Standards”; useful lives are based on the “Ministerial Ordinance on Useful Lives of Depreciable Assets” (National Tax Agency useful life tables). The classification of buildings and depreciable assets, valuation methods and tax rates were cross-checked against published materials from nine municipalities. New opening counts are our own tally (2022–2026, based on confirmed listings on major booking sites). Estimated settled ADR is based on monthly medians from our data (September 2025 – August 2026; Tokyo business hotels N=914 properties / Tokyo city hotels N=107 properties / Shizuoka ryokan N=450 properties). Checked September 9, 2026.
■ Estimate assumptions
The depreciable assets in the three models provisionally assume a typical asset mix by hotel type and are not figures for any actual property. The acquisition cost and useful life of every asset are disclosed in the assumption tables at the end of the article. Valuation uses the old declining-balance method: half-year depreciation (1 − depreciation rate ÷ 2) in the acquisition year and (1 − depreciation rate) thereafter, with a floor of 5% of acquisition cost. The taxable base is rounded down to ¥1,000 and tax to ¥100, with the standard 1.4% rate as the base. Occupancy rates used for the ADR equivalent are 80% for Model A (full year; estimate assumption as of September 2026), 75% for Model B (same) and 60% for Model C (same). All are assumed values by hotel type, not measured occupancy rates compiled by us. The sensitivity analysis varies two variables: the ratio of depreciable assets to building investment (±20% from base; 10.0–20.0% in the grid) and the tax rate (1.4–1.7%).
■ Limitations and caveats
(1) Tax rates, exemption thresholds and taxable-base special measures vary with local ordinances and legislative changes, so in practice always confirm with the property tax division of the relevant municipality. (2) The extent to which building services are included in building valuation differs between municipalities, and whether the same equipment is treated as a depreciable asset can change. This article sets out the published standards of several municipalities, but they are not a uniform national standard. (3) This article presents model estimates built up from assumptions and does not guarantee the tax amount for any specific property. (4) The party required to file for leased assets depends on the contract type. (5) Estimated settled ADR is an estimate and differs from each property’s actual settled rates and accounting figures.
■ Market data
- MetroEngines Research & Consulting — Estimated settled ADR (prefecture × hotel type, September 2025 – August 2026); new openings (based on confirmed listings on major booking sites, 2022–2026, N=8,953 properties)
- Ministry of Land, Infrastructure, Transport and Tourism, “Statistics on Building Construction Starts” (per-tsubo costs underlying the per-room construction cost assumptions)