

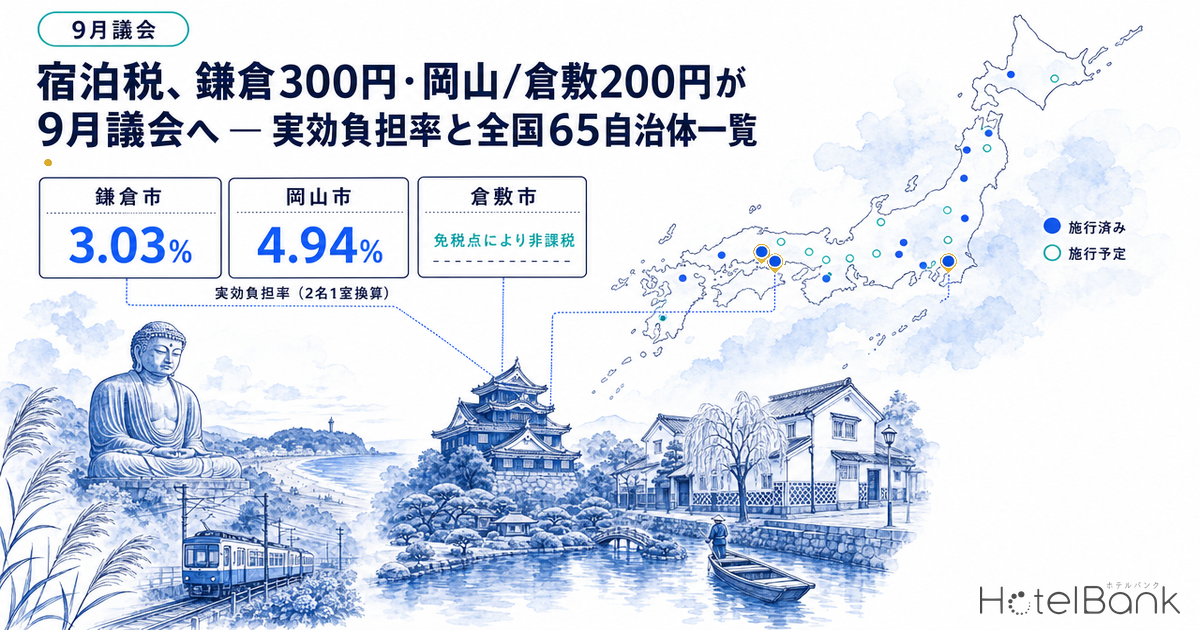
On August 24, 2026, the mayor of Kamakura, and on the following day the mayor of Okayama, each announced plans to submit a lodging tax ordinance to their September regular council sessions. Kurashiki has already run a public comment process in July on a draft ordinance setting the tax at ¥200 per person per night, and the Hakone town council is deliberating a lodging tax ordinance at its September regular session, which opened at the end of August. Institutional groundwork for local tourism funding has reached a clear peak in autumn 2026.
This article tabulates the tax designs of the three cities whose bills converged on these “September councils” (Kamakura, Okayama and Kurashiki), estimates the effective burden rate by applying each tax amount to the city’s prevailing room rates, and maps the nationwide distribution of municipalities with a lodging tax in effect or scheduled as of 2027. Finally, it sets out the practical issues for accommodation operators. It does not evaluate the merits of any individual municipality’s design.
Metric Definitions Used in This Article
- ADR (estimated settled ADR): An estimated settled room rate (tax-excluded equivalent), calculated by applying a property-type adjustment factor to the lowest-plan price level each property publishes on major booking sites (per room, 2 guests per room). Checked against property-level results disclosed by listed hotel REITs (91 properties, most recent 3 months), the median error is about 7%. It is an estimate and differs from each property’s actual settled prices and accounting figures. Area-level ADR is the median of the covered properties (the level of a typical property in the area).
- Listed price: The average published price across all plans, from room-only to meal-inclusive (per room, 2 guests per room, tax included). Because its basis differs from the estimated settled ADR, the two are clearly distinguished throughout this article.
- Effective burden rate: Lodging tax amount ÷ room charge per person per night. This article estimates it in two ways: “1 guest per room,” treating the estimated settled ADR (per room) as one person’s charge, and “2 guests per room,” dividing it by two.
- Data source: MetroEngines Research (period: the 12 settled months from September 2025 to August 2026)
- — Kamakura ¥300 and Okayama ¥200 lodging tax bills go to the September 2026 regular council sessions. Kurashiki has completed public comment on a ¥200 draft
- — The effective burden rate on estimated settled ADR (2 guests per room) is 4.94% in Okayama and 3.03% in Kamakura; 2.47% and 1.51% at 1 guest per room
- — In Kurashiki, the ¥5,000 exemption threshold puts the typical per-guest rate at 2 guests per room (about ¥4,200) in the untaxed zone, so the same ¥200 produces a different outcome from Okayama
- — Under a flat amount, the burden rises as rates fall; Okayama’s ¥200 exceeds the 3% rate below about ¥6,700 per guest-night
- — Operators need to start special-collector registration, collection rules for bookings that straddle the effective date, and system changes 6 to 12 months before the tax takes effect
Three Cities at the September Councils — Tax Amount, Exemption Threshold and Timing
First, a side-by-side view of the three designs. All three share a flat amount per person per night, but they differ on the tax amount and the treatment of an exemption threshold. Kamakura is ¥300; Okayama and Kurashiki are ¥200. On the exemption threshold, Okayama intends to make no exceptions, including for low-priced stays and school trips, whereas Kurashiki’s draft exempts stays under ¥5,000 per person per night. Whether a threshold exists turns out to be decisive in the effective burden estimates below.
| Item | Kamakura (Kanagawa) | Okayama City (Okayama) | Kurashiki (Okayama) |
|---|---|---|---|
| Tax amount | ¥300 per person per night | ¥200 per person per night | ¥200 per person per night |
| Method | Flat amount (uniform) | Flat amount (uniform) | Flat amount (uniform) |
| Exemption threshold | Reported as a “uniform ¥300”; no exemption threshold has been specified | None (no exceptions planned, including low-priced stays and school trips) | Stays under ¥5,000 per person per night are not taxed |
| Taxable scope | About 370 hotels, ryokan, private lodgings (minpaku) and other facilities in the city | Accommodation facilities in the city | Accommodation facilities in the city |
| Planned start | Targeting October 2027 | Within FY2027 (mid-year) targeted | FY2027 or later targeted |
| Expected revenue | About ¥150 million per year | About ¥280 million per year | Not disclosed at the draft stage |
| Council process | Plan to submit announced Aug 24; submitted to the September regular session opening Sept 2 | Plan to submit announced Aug 25; submitted to the September regular session opening Sept 1 | Public comment on the draft ordinance held July 3–31 |
| Context | Second in Kanagawa Prefecture (Yugawara went first in April 2026) | Okayama City’s first non-statutory earmarked tax | A review committee concluded in June 2026 that “a uniform flat amount is appropriate” |
Source: Compiled by HotelBank Editorial Team from each city’s announcements and press reports (July–August 2026)
The same “¥200 for stays of ¥5,000 or more” design has also been adopted by Izumo in Shimane Prefecture, so a common template is emerging in the Chugoku region. Kamakura’s bill covers about 370 facilities in the city and is set to include private lodgings (minpaku) in the taxable scope.
Applying the Tax to Actual Rates — Estimated Settled ADR, Not Listed Price
Which price goes in the denominator largely determines the effective burden estimate. Under most ordinances, the tax base is the “accommodation charge,” meaning a room-only equivalent that excludes meals, service charges and consumption tax. Using the all-plan average listed price, which includes meal-inclusive plans, would therefore understate the burden.
The chart below compares the listed price (all-plan average, tax included) and the estimated settled ADR (tax-excluded equivalent) for the three cities and the main comparison municipalities. In Kurashiki, the listed price of ¥23,800 compares with an estimated settled ADR of ¥8,500, a ratio of 2.8x. Two-meal plans at ryokan around the Bikan historical quarter push up the listed price, while many of the rooms that actually sell are at business hotels near the station. All estimates in the rest of this article use the estimated settled ADR as the denominator.
Source: Prepared by HotelBank Editorial Team from MetroEngines Research (average of the 12 settled months, September 2025–August 2026)
| Municipality | Listed price (all-plan avg., tax incl.) | Estimated settled ADR (tax-excl. equiv.) | Ratio | Listed properties N | Settled ADR sample N |
|---|---|---|---|---|---|
| Kamakura | ¥33,900 | ¥19,800 | 1.71x | 75–111 | 15–19 |
| Okayama City (4 wards combined) | ¥15,700 | ¥8,100 | 1.94x | 61–104 | 49–53 |
| Kurashiki | ¥23,800 | ¥8,500 | 2.81x | 67–84 | 42–43 |
| Morioka | ¥15,100 | ¥7,300 | 2.05x | 44–49 | 40–44 |
| Nasu | ¥34,200 | ¥19,900 | 1.72x | 195–260 | 49–54 |
| Hakone | ¥51,800 | ¥26,400 | 1.96x | 278–386 | 170–187 |
| Tokyo | ¥25,500 | ¥14,500 | 1.75x | 1,652–2,417 | 1,067–1,145 |
| Osaka Prefecture | ¥18,200 | ¥10,400 | 1.76x | 871–1,250 | 623–653 |
| Kyoto City (11 wards combined) | ¥33,900 | ¥17,000 | 2.00x | 1,324–1,908 | 410–434 |
Source: Prepared by HotelBank Editorial Team from MetroEngines Research (September 2025–August 2026, 12 settled months average; N is the monthly minimum–maximum)
*For Okayama City and Kyoto City, ward-level rows are weighted by the number of listed properties to return to a city-wide level. Kamakura’s settled ADR sample of 15–19 properties is relatively small, so its month-to-month swings are larger than in other cities.
Effective Burden Estimates — Okayama 4.94%, Kurashiki Zero Due to the Exemption Threshold
A flat-amount lodging tax is levied “per person per night,” whereas the rates we track are per room. We therefore estimated the effective burden in two ways: a room used by one guest (charge per person = estimated settled ADR) and a room used by two guests (charge per person = estimated settled ADR ÷ 2). Actual occupants per room vary by property and guest mix, so the two figures are best read as an upper and lower bound.
Source: Prepared by HotelBank Editorial Team from MetroEngines Research (each ordinance’s tax amount applied to the September 2025–August 2026 12 settled months average)
| Municipality | Tax structure | Estimated settled ADR (per room) | Rate per guest-night (2 guests per room) | Tax | Effective burden (2 guests per room) | Effective burden (1 guest per room) |
|---|---|---|---|---|---|---|
| Morioka | Flat ¥200, no exemption threshold | ¥7,347 | ¥3,674 | ¥200 | 5.44% | 2.72% |
| Okayama City | Flat ¥200, no exemption threshold (planned) | ¥8,091 | ¥4,046 | ¥200 | 4.94% | 2.47% |
| Kyoto City | 5-tier graduated | ¥16,986 | ¥8,493 | ¥400 | 4.71% | 2.35% |
| Osaka Prefecture | 3-tier graduated, ¥5,000 exemption threshold | ¥10,358 | ¥5,179 | ¥200 | 3.86% | 1.93% |
| Kamakura | Flat ¥300 (planned) | ¥19,804 | ¥9,902 | ¥300 | 3.03% | 1.51% |
| Hakone | Flat ¥350 (target April 2028) | ¥26,385 | ¥13,192 | ¥350 | 2.65% | 1.33% |
| Nasu | 6-tier graduated | ¥19,863 | ¥9,932 | ¥100 | 1.01% | 1.51% |
| Tokyo (from April 2027) | 3% rate, ¥13,000 exemption threshold | ¥14,531 | ¥7,266 | ¥0 | 0.00% | 3.00% |
| Kurashiki | Flat ¥200, ¥5,000 exemption threshold (planned) | ¥8,450 | ¥4,225 | ¥0 | 0.00% | 2.37% |
Source: Prepared by HotelBank Editorial Team from MetroEngines Research (blue shading marks the three cities whose bills went to the September councils)
Three points stand out from the estimates.
First, Okayama’s ¥200 produces a relatively high burden for a flat-amount tax because its rates are low. At 4.94% for 2 guests per room and 2.47% even for 1 guest, it sits close to the 3% rate Tokyo will introduce in April 2027. By contrast, Hakone (¥350), with an estimated settled ADR in the ¥26,000 range, stays at 1.33–2.65%. A flat amount is structurally heavier in areas with lower rates.
Second, Kurashiki’s ¥5,000 exemption threshold bites across a wide range of 2-guest stays. Kurashiki’s estimated settled ADR is about ¥8,500; split between two guests, that is about ¥4,200 per person, below the threshold. Taxability is of course determined booking by booking based on the actual accommodation charge, so not every 2-guest stay will be exempt, but the fact that the city’s typical rate sits near the threshold affects both revenue projections and collection practice. It is probably no coincidence that Kurashiki has not published a revenue estimate at the draft stage, given how hard this line is to read.
Third, Kamakura’s ¥300 lands in the middle on burden because its rates are high. At 1.51–3.03%, it is below Kyoto City (2.35–4.71%) and Osaka Prefecture (1.93–3.86%). Working back from a taxable base of about 370 facilities and projected revenue of ¥150 million a year implies roughly 500,000 taxable guest-nights a year.
Flat-Amount Burden Swings Widely by Rate Band — The Tax Curve
The difference in character between flat-amount and flat-rate taxes can be visualized with a burden curve plotted against the room charge per guest-night. A flat amount traces a hyperbola that shoots up as rates fall; a flat rate is a horizontal line. Designs with an exemption threshold drop to zero below it.
Source: Prepared by HotelBank Editorial Team from each municipality’s ordinance or draft ordinance
Okayama’s ¥200 overtakes Tokyo’s 3% rate at ¥6,700 per guest-night. For inventory in the ¥3,000–5,000 band, such as dormitories, capsule hotels and room-only budget properties, the burden reaches 4–7%, while above ¥15,000 it stays at about 1.3% or less. Kamakura’s ¥300 crosses over at ¥10,000; given the city’s estimated settled ADR of ¥19,800, the typical per-guest rate at 2 guests per room (about ¥9,900) sits right around that line.
The 6-tier graduated design adopted by Nasu smooths this hyperbola into steps, ranging from ¥100 below ¥10,000 to ¥3,000 at ¥100,000 or more. Kurashiki’s ¥5,000 exemption threshold likewise works to contain the upward swing at the low end. The three design options — “flat amount + exemption threshold,” “graduated” and “flat rate” — can be read as different answers to the same question.
Nationwide Distribution as of 2027 — 43 Points in Effect, 15 Scheduled
Lodging taxes are non-statutory earmarked taxes under the Local Tax Act, set by each municipality by ordinance. Starting with Tokyo in 2002, followed by Osaka Prefecture in 2017 and Kyoto City in 2018, they have spread rapidly over the past two years. We confirmed effective dates for 61 municipalities (Tokyo is counted once, for its 2002 introduction, and not again for its April 2027 switch to a flat rate), of which 31 took effect in 2026 and 13 are scheduled for 2027.
Source: Prepared by HotelBank Editorial Team from each municipality’s ordinances and published materials (N=61 municipalities)
The map below plots these municipalities by status. Where a prefecture and its capital city both levy the tax — Miyagi/Sendai, Hokkaido/Sapporo and Fukuoka Prefecture/Fukuoka City — they are combined into a single point, giving 58 pins. Adding the four municipalities deliberating at their September regular sessions (Kamakura, Okayama, Kurashiki and Hakone) brings the total shown to 62 points.
Source: Prepared by HotelBank Editorial Team from each municipality’s ordinances and published materials
The distribution is densest in Hokkaido (the prefectural tax plus 19 municipalities) and Nagano (the prefectural tax plus 4 municipalities), to which Okinawa (the prefectural tax plus 6 municipalities, effective February 2027) is being added. Conversely, gaps remain in Tohoku, northern Kanto, Shikoku and Hokuriku, where Morioka (October 2026), Yamagata (April 2027, planned) and Nasu (October 2026) are the early movers. In the Chugoku region, Okayama, Kurashiki and Izumo are moving after Hiroshima Prefecture (April 2026) and Matsue (December 2025), and the map is filling in toward FY2027.
By design type, flat amounts are the most common nationwide, followed by graduated and flat-rate designs. Flat rates are limited to Tokyo (April 2027), Yamagata, Tomakomai and Kitahiroshima (all planned), Kutchan and Okinawa Prefecture; because revenue automatically tracks rising rates, they tend to be adopted in areas with strong rate growth. A comprehensive list of tax amounts and effective dates nationwide is available in Japan Lodging Tax 2026: All 62 Municipalities.
Practical Issues for Operators — Registration, Collection Timing and System Changes
Between enactment and the effective date, there is a preparation period of about one year in Kamakura and roughly one to one and a half years in Okayama and Kurashiki. The work operators need to do in that time falls into four broad areas.
| Issue | Details | When to start |
|---|---|---|
| Registering as a special collector | Guests are the taxpayers, and the facility collects, files and remits the tax as a special collector. Registration with the municipality (per facility) is generally required before the effective date, and private lodgings (minpaku) and simple lodging facilities are included. Kamakura covers about 370 facilities including minpaku, so home-sharing operators carry the same obligation. | 3–6 months before the effective date (in line with the municipality’s registration window) |
| Collection timing and bookings via booking sites | Taxability is mainly determined on a “stay-date basis”: the ordinance in force on the actual night of stay applies, not the booking or payment date. Advance bookings that straddle the effective date are taxable, so operators need to decide in advance whether to collect on site or add the tax at booking for reservations accepted before the tax starts. Morioka also advises that “guests who booked in advance are subject to the tax.” For prepaid and pay-now plans via booking sites, whether the tax is included in the payment or collected on site differs by site and plan, so it needs to be sorted out plan by plan. | 6–12 months before the effective date (counting back from when bookings open) |
| System changes | Reservation and property management systems, self-checkout machines, receipt and invoice formats, and accounting codes (deposits received) all need to be updated. Kurashiki’s design with an exemption threshold requires logic that apportions the “accommodation charge per person per night” across guests, so the scope of changes is wider than for Okayama’s uniform flat amount. Chains with properties in several municipalities need per-property parameter management, since tax amounts, thresholds and exemption rules differ by municipality. | 6–9 months before the effective date (check application windows where municipalities subsidize system costs) |
| Price display and guest communication | Because the lodging tax is separate from the room charge, whether it is included in the displayed price or shown separately changes how rates appear on booking sites. Showing it separately keeps the displayed price unchanged but increases the explanation burden at on-site payment. Many facilities in municipalities where the tax is already in effect show it separately and collect it on site. | 3–6 months before the effective date |
Source: Prepared by HotelBank Editorial Team from each municipality’s published materials and guidance for accommodation operators
Especially where two cities in the same prefecture, like Okayama and Kurashiki, start at around the same time, operators running multiple properties in the prefecture will handle two rule sets in parallel: the same tax amount, but with and without an exemption threshold. Kurashiki’s design requires a “¥5,000 per person per night” test, and how the charge is apportioned when several guests share a room will shape the specification of system changes. Running your own booking data against the draft to estimate the taxable share, without waiting for the ordinance to be finalized, gives a clearer sense of the scale of system changes and the revenue impact.
Subsidy programs are also worth checking. Some municipalities where the tax is already in effect offer subsidies for system changes needed to handle the lodging tax. Application windows are often set around six months before the effective date, so it is worth confirming with the municipality’s tourism department early after the ordinance passes.
Summary
The three cities that moved in the September 2026 council rush all adopt a flat amount per person per night, but their designs split on the tax amount (Kamakura ¥300 / Okayama and Kurashiki ¥200) and the exemption threshold (none in Okayama / stays under ¥5,000 exempt in Kurashiki). Applied to estimated settled ADR, the effective burden at 2 guests per room is 4.94% in Okayama, 3.03% in Kamakura and 0.00% in Kurashiki (exempt due to the threshold), confirming that the same “flat ¥200” can produce very different results depending on the combination of rate level and exemption threshold.
With these three cities and Hakone added, the number of municipalities with a lodging tax in effect or scheduled is expected to reach 65. For operators, the three issues to start on 6 to 12 months before the effective date are special-collector registration, collection rules for bookings that straddle the effective date, and system changes including exemption-threshold logic. Please check each city’s published materials for the status of the ordinances and confirmed effective dates.
Related Articles
- Japan Lodging Tax 2026: All 62 Municipalities, Rates and ADR Burden
- Furusato Tax Curbs vs. Lodging Tax: Local Government Revenue Shift Hits Regional Hotels
References and Sources
■ Market data
- MetroEngines Research — estimated settled ADR and listed prices (period: the 12 settled months from September 2025 to August 2026)
■ Municipal announcements and published materials
- Okayama City, “Results of the public comment on ‘Okayama City’s Approach to a Lodging Tax (Draft)'” (Japanese)
- Nasu Town, “Introduction of the Nasu Town Lodging Tax” (taxation scheduled from October 2026) (Japanese)
- Kyoto City, “About the Lodging Tax” (revised for stays from March 1, 2026) (Japanese)
- Osaka Prefecture, “The Lodging Tax System Is Changing” (revised September 1, 2025) (Japanese)
■ Press reports
- Kanagawa Shimbun, “Kamakura to introduce lodging tax; plans to submit ordinance to council, second in the prefecture” (press conference, August 24, 2026) (Japanese)
- TV Asahi network (ANN), “Kamakura plans lodging tax of ¥300 per person per night; about ¥150 million in annual revenue expected” (Japanese)
- Sanyo Shimbun, “Okayama City to introduce lodging tax in mid-FY2027; ordinance to be proposed at September council” (August 25, 2026) (Japanese)
- KSB Setonaikai Broadcasting, “¥200 per person per night: Kurashiki drafts lodging tax ordinance, opens public comment” (July 3, 2026) (Japanese)
- Chugoku Shimbun, “Okayama and Kurashiki to introduce lodging tax; ¥200 per night, ordinances to be submitted” (Japanese)
- Nikkei, “Lodging taxes in Okayama, Kurashiki and Izumo (Shimane): ¥200 for stays of ¥5,000 or more” (Japanese)
- Town News, “Hakone town council opens September regular session; lodging tax ordinance among items” (August 29, 2026) (Japanese)
- Kanagawa Shimbun, “Hakone plans lodging tax as Japan’s first ‘non-statutory ordinary tax'” (Japanese)
- Iwate Ryokan Hotel Association, “[Morioka] Lodging tax starts October 1, 2026” (Japanese)
- TOKYO MX, “Tokyo lodging tax to become a 3% flat rate from next April; private lodgings also covered” (Japanese)
- Shimotsuke Shimbun, “Nasu lodging tax expected to raise ¥114 million in first year” (Japanese)