

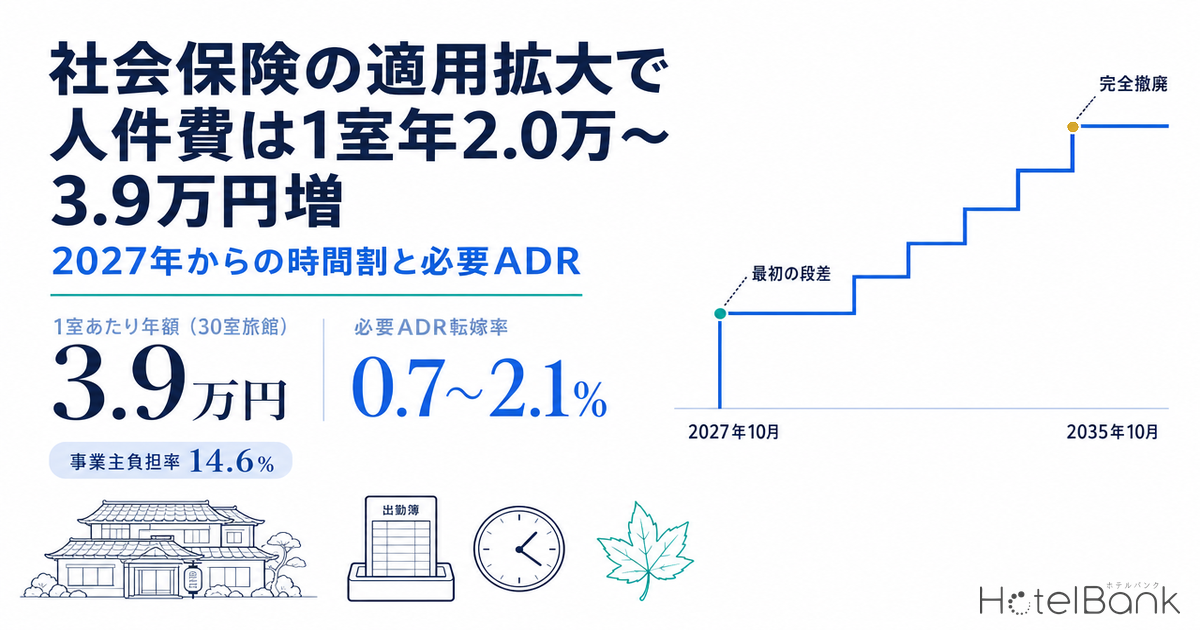
Japan’s pension reform law — the Act Partially Amending the National Pension Act and Related Laws to Strengthen the Pension System in Light of Socioeconomic Change, promulgated on June 20, 2025 — widens eligibility for employee health insurance and the Employees’ Pension Insurance (kosei nenkin) in stages from 2026 through 2035. For the hotel industry, the key point is that the law already fixes when the expansion reaches which size of employer. Unlike wage revisions, which change every year with the outcome of negotiations, the effective dates are locked in by statute and cabinet order. For anyone building a post-acquisition NOI, this makes it one of the few cost drivers that can be priced in ahead of time.
This article lays out that timetable from primary sources, builds up the employer’s contribution per part-time worker from the published rates, and converts it into an “annual cost per room” and a “required ADR pass-through rate” for three models: 30, 100 and 200 rooms. Finally, it connects the result to NOI underwriting and DSCR at acquisition.
Metric Definitions Used in This Article
- ADR (Average Daily Rate): An estimated settled rate (tax-excluded equivalent), calculated by applying a property-type adjustment factor to the lowest-plan price each property publishes on OTAs and similar channels (2 guests per room, per-room price, tax included). Checked against property-level results disclosed by listed hotel REITs (91 properties, most recent 3 months), the median error is about 7%. These are estimates and differ from each property’s actual settled prices and accounting figures. Area-level ADR is the median of the covered properties (the level of a typical property in the area).
- OCC (Occupancy Rate): The annual base in the model uses the Japan Tourism Agency’s Overnight Travel Statistics Survey annual room occupancy by property type. Our own estimates, shown for reference, are the share of sold rooms in total rooms in an area (estimated from OTA sales inventory) and differ from the actual occupancy of each property as a whole.
- Employer contribution rate: The employer’s share, as a percentage of standard monthly remuneration, of the half-and-half split of health insurance, Employees’ Pension Insurance, long-term care insurance and the child and child-rearing support levy, plus the child and child-rearing contribution (paid entirely by the employer).
- NOI, DSCR and cap rate: NOI is net operating income (a simplified room-revenue-based figure in this article’s model). DSCR is annual NOI ÷ annual debt service and shows the headroom for loan repayment. The cap rate is NOI divided by asset value and is used to convert changes in NOI into changes in asset value.
- Data sources: MetroEngines Research & Consulting / Ministry of Health, Labour and Welfare (MHLW), Japan Pension Service, Japan Health Insurance Association (Kyokai Kenpo) / Statistics Bureau, Ministry of Internal Affairs and Communications / Japan Tourism Agency
*The system details in this article are based on information published and draft cabinet orders as of September 16, 2026. Some implementation details are left to future cabinet and ministerial orders and may change.
- — In October 2027 the employer-size requirement drops to 36 or more insured employees under the Employees’ Pension Insurance, then to 21 or more (October 2029) and 11 or more (October 2032), before being abolished in October 2035. The timing of each step is fixed by law.
- — The employer contribution is 14.575% of standard monthly remuneration (under age 40, FY2026 national average rates). Prefectural spread is 0.67 points, from 14.23% in Niigata to 14.90% in Saga.
- — Across the three models, the increase is ¥20,000–¥39,000 per room per year, and the required ADR pass-through is 0.67% (200 rooms), 1.11% (100 rooms) and 2.06% (30-room ryokan).
- — What drives the gap in pass-through rates is not wages but occupancy. At a 38.4% annual room occupancy (Japan Tourism Agency, full-year 2025 preliminary), a ryokan sells about half as many room-nights as a business hotel, so its pass-through rate is roughly 1.9 times higher.
- — In the 100-room model, DSCR only moves from 1.63 to 1.57 even with zero pass-through, but capitalized at a 5.0% cap rate the cost equals 3.7% of the purchase price — the impact shows up in bid prices.
Bottom Line — Up to ¥39,000 per Room per Year; Required ADR Pass-Through of 0.7–2.1%
The conclusion first. One: for the hotel industry, the real event is not the removal of the wage requirement in October 2026 but the stepwise lowering of the employer-size requirement starting in October 2027. As explained below, rising minimum wages have already largely hollowed out the wage requirement, so its removal creates almost no step in costs.
Two: the size of the step falls within ¥20,000–¥39,000 per room per year. Converted into a required ADR pass-through, that is 0.7–2.1%, or ¥70–¥280 of ADR. Compared with ADR growth over the past few years, this is within a range that pricing can absorb.
Three: because the effective dates are fixed, the cost can be built into the acquisition business plan year by year. The seller’s historical results naturally do not include this step, so the buyer has to add it to the model. Put the other way, a buyer who can bid a price that still works after adding it can bid more accurately than one who has not.
The Timetable — The Employer-Size Requirement Goes from 51+ to Zero over 10 Years
The pension reform law was enacted on June 13, 2025 and promulgated on June 20 of the same year as Act No. 74. The current requirements for covering part-time workers are five: scheduled working hours of 20 or more per week, monthly wages of ¥88,000 or more, expected employment of more than two months, not being a student, and the size of the employer (51 or more people insured under the Employees’ Pension Insurance). The reform removes the wage requirement and the employer-size requirement.
The key detail is how “employees” are counted. The employer-size requirement counts not headcount but the number of people insured under the Employees’ Pension Insurance. Part-timers and casual staff whose scheduled hours are under three-quarters of a regular worker’s are not currently insured and are not counted. So a ryokan with 80 people on staff is treated as a “30-person employer” if 30 of them are full-time equivalents. In an industry like hospitality, with a high share of part-time workers, apparent headcount and the headcount used for the test can differ sharply.
| Effective date | What changes | What it means for hotel operators |
|---|---|---|
| October 1, 2026 Draft cabinet order | Wage requirement for part-time workers (¥88,000+/month) abolished. Workers under the minimum-wage reduction exception whose monthly wage falls below ¥88,000 are, in principle, not insured, but a mechanism lets them join on request. | Applies only to employers that meet the employer-size requirement. As explained below, the practical impact is limited. |
| September 2027 | Cap on standard monthly remuneration for the Employees’ Pension Insurance raised from ¥650,000 to ¥680,000 (new grade 33). Raised further in stages to ¥710,000 in September 2028 and ¥750,000 in September 2029. | Affects general managers and executives earning ¥665,000+ per month. A fixed increase that does not scale with room count. |
| October 1, 2027 | Employer-size requirement lowered to 36 or more pension-insured employees (currently 51+). | The first step for employers with 36–50 full-time equivalents. Limited-service hotels of around 200 rooms are likely to be affected. |
| October 1, 2029 | Employer-size requirement lowered to 21 or more. At the same time, the exempt-industry status for sole proprietorships is removed, making sole-proprietor establishments in lodging, food service and similar industries that regularly employ 5+ people mandatory-coverage establishments. However, establishments existing at the effective date remain exempt for the time being. | Employers with 21–35 full-time equivalents are brought in. Owner-operated ryokan stay as they are for now under the transitional measure, but note that it does not carry over upon incorporation or succession. |
| October 1, 2032 | Employer-size requirement lowered to 11 or more. | Small and mid-sized ryokan and small hotels with 11–20 full-time equivalents are brought in. |
| October 1, 2035 | Employer-size requirement abolished entirely. | Regardless of size, all part-time workers working 20+ hours per week with expected employment of more than two months are covered. |
Costing It — Employer Share Is 14.6% of Standard Monthly Remuneration, with a 0.67pt Prefectural Range
When coverage widens, the amount that lands on the employer is found by stacking up the contribution rates. The FY2026 (Reiwa 8) rates are as follows.
| Insurance / contribution | Rate (employer + employee) | Employer share | Scope / source |
|---|---|---|---|
| Employees’ Pension Insurance | 18.300% | 9.150% | Uniform nationwide, split 50/50 (Japan Pension Service) |
| Health insurance (Kyokai Kenpo) | 9.90% (national avg.) | 4.950% | By prefecture. From 10.55% in Saga to 9.21% in Niigata (Japan Health Insurance Association, FY2026, applied from March premiums) |
| Child and child-rearing support levy | 0.230% | 0.115% | Added uniformly nationwide from April 2026 premiums (paid in May) |
| Long-term care insurance (Category 2) | 1.620% | 0.810% | Ages 40–64 only, uniform nationwide |
| Child and child-rearing contribution | 0.360% | 0.360% | Paid entirely by the employer; based on pension standard monthly remuneration |
| Total (under 40) | — | 14.575% | Prefectural range 14.23% (Niigata) to 14.90% (Saga) |
| Total (ages 40–64) | — | 15.385% | Prefectural range 15.04% to 15.71% |
One practical point to note: the standard monthly remuneration for the Employees’ Pension Insurance has a floor of ¥88,000, while the health insurance floor is ¥58,000. So even for workers earning under ¥88,000 a month, the pension premium and the child and child-rearing contribution are calculated on a base of ¥88,000. The lower the wage, the higher the employer contribution relative to that wage.
By wage band, the annual employer contribution per part-time worker works out as follows. National average rates are used, and standard monthly remuneration is assigned using the Kyokai Kenpo grade table.
| Monthly wage | Standard monthly remuneration (health / pension) | Employer share per month (under 40) | Employer share per year (under 40) | Employer share per year (40–64) |
|---|---|---|---|---|
| ¥60,000 | ¥58,000 / ¥88,000 | ¥11,306 | ¥135,678 | ¥141,316 |
| ¥80,000 | ¥78,000 / ¥88,000 | ¥12,320 | ¥147,834 | ¥155,416 |
| ¥88,000 | ¥88,000 / ¥88,000 | ¥12,826 | ¥153,912 | ¥162,466 |
| ¥100,000 | ¥98,000 / ¥98,000 | ¥14,284 | ¥171,402 | ¥180,928 |
| ¥110,000 | ¥110,000 / ¥110,000 | ¥16,032 | ¥192,390 | ¥203,082 |
| ¥125,000 | ¥126,000 / ¥126,000 | ¥18,364 | ¥220,374 | ¥232,621 |
| ¥145,000 | ¥142,000 / ¥142,000 | ¥20,696 | ¥248,358 | ¥262,160 |
| ¥180,000 | ¥180,000 / ¥180,000 | ¥26,235 | ¥314,820 | ¥332,316 |
The prefectural gap is 0.67 points. For a property with 10 part-time workers at a standard monthly remuneration of ¥126,000, that works out to a difference of about ¥100,000 a year between Niigata and Saga. Small on its own, but when an operator running properties in several prefectures compares GOP by site, it amounts to a location-driven head start or handicap of that size.
Statutory Welfare Costs Vary by Location — Employer Contribution Rates Across 47 Prefectures
Health insurance rates are set by each prefectural branch of Kyokai Kenpo, so statutory welfare costs differ by location even at the same wage. The size and shade of each circle show the employer contribution rate (under 40, FY2026).
| Saga | 14.90% | Health 10.55% |
| Hokkaido | 14.77% | Health 10.28% |
| Tokushima | 14.74% | Health 10.24% |
| Yamaguchi | 14.70% | Health 10.15% |
| Osaka | 14.69% | Health 10.13% |
| Ibaraki | 14.38% | Health 9.52% |
| Iwate | 14.38% | Health 9.51% |
| Fukushima | 14.38% | Health 9.50% |
| Okinawa | 14.35% | Health 9.44% |
| Niigata | 14.23% | Health 9.21% |
Employer contribution rate = (health insurance rate + child and child-rearing support levy 0.23%) ÷ 2 + Employees’ Pension 9.15% + child and child-rearing contribution 0.36%. Shown for under-40s; excludes long-term care insurance (employer 0.81%). Rates are revised every fiscal year, so multi-year models should treat them as variables subject to revision rather than fixed values.
The Lodging Workforce — 58.8% Non-Regular, 1.6x the All-Industry Average
The impact of the expansion differs by industry because the share of part-time workers differs. In the Statistics Bureau’s Labour Force Survey, the lodging industry (intermediate classification) had 554,000 employees excluding executives on average in January–July 2026, of whom 326,000 — 58.8% — were non-regular staff. Of these, part-timers and casual workers numbered 279,000, or 50.3%.
In the same survey’s 2025 average, the non-regular share across all industries was 36.5%. Lodging is 22.3 points higher. Moreover, the lodging non-regular share in the same period a year earlier (January–July 2025 average) was 56.8%, so the share has risen by 2.0 points rather than falling. The population subject to the expansion is not shrinking.
Being non-regular is not the same as being covered, however. Coverage requires scheduled working hours of 20 or more per week, so on-call staff working around 15 hours a week remain outside. The model estimates below set headcounts after explicitly assuming that a certain share of non-regular workers work 20+ hours a week.
Seen the other way, this structure means lodging is an industry highly sensitive to the rule change. High sensitivity also means a wider gap between operators who prepare in advance and those who don’t. Where to draw the 20-hour line, and how to explain the change to staff whose take-home pay will change on enrollment, are issues that can be settled before 2027.
Three-Model Estimate — ¥20,000–¥39,000 per Room per Year, Required ADR Pass-Through of 0.67–2.06%
Using the rates and workforce structure above, we calculate the annual increase for three models of different room counts. All assumptions are stated. The number of full-time equivalents (= pension-insured employees) determines when coverage arrives; the number and wage level of newly covered part-time workers determine the amount.
| Assumptions and results | C: 200 rooms Limited-service (urban, corporate) | B: 100 rooms Business hotel (regional city, corporate) | A: 30 rooms Ryokan (regional) |
|---|---|---|---|
| Pension-insured employees (full-time equivalents) | 40 | 24 | 12 |
| When the expansion reaches the property | Oct 2027 | Oct 2029 | Oct 2032 |
| Newly covered part-time workers | 16 | 10 | 6 |
| Average monthly wage of those covered | ¥145,000 | ¥125,000 | ¥110,000 |
| Annual employer contribution per person | ¥253,200 | ¥224,700 | ¥196,100 |
| Annual increase | ¥4,051,000 | ¥2,247,000 | ¥1,177,000 |
| Annual cost per room | ¥20,300 | ¥22,500 | ¥39,200 |
| Assumed OCC (Japan Tourism Agency, 2025) | 75.3% | 75.3% | 38.4% |
| Annual room-nights sold (per room) | 274.8 | 274.8 | 140.2 |
| Assumed ADR (estimated settled ADR) | ¥11,000 | ¥7,300 | ¥13,600 |
| Required ADR pass-through (per night) | approx. ¥74 | approx. ¥82 | approx. ¥280 |
| Required ADR pass-through rate | 0.67% | 1.11% | 2.06% |
C 200 rooms, limited-service
The most people, but the lightest once divided by rooms: ¥20,000 per room per year, a 0.67% pass-through. Coverage arrives earliest, in October 2027 — about a year away. With high occupancy and 274.8 room-nights sold per room per year, the cost is only about ¥74 per night.
B 100 rooms, business hotel
Coverage arrives in October 2029, a little over three years away. ¥22,500 per room per year, a 1.11% pass-through. Because the regional-city rate level (estimated settled ADR ¥7,300) is the denominator, the pass-through rate is 1.7 times that of C. The lower a market’s rates, the higher the pass-through for the same amount.
A 30 rooms, ryokan
Coverage arrives in October 2032, six years away. The smallest amount, but the heaviest burden: ¥39,000 per room per year, a 2.06% pass-through. The reason is occupancy — at a 38.4% annual room occupancy, a ryokan sells few room-nights and cannot spread the same cost thinly.
Holding the annual cost per room at Model B’s approx. ¥22,500 and expanding the “occupancy and rate determine the pass-through” pattern seen in the three models across two axes — annual (full-year) room occupancy and estimated settled ADR — gives the following.
| Annual room occupancy (full-year) | ¥6,000 | ¥7,300 (Model B) | ¥9,000 | ¥11,000 (Model C) | ¥13,600 (Model A) |
|---|---|---|---|---|---|
| 40% Close to ryokan (38.4%) | 2.56% | 2.10% | 1.71% | 1.40% | 1.13% |
| 50% | 2.05% | 1.68% | 1.37% | 1.12% | 0.91% |
| 60% | 1.71% | 1.40% | 1.14% | 0.93% | 0.76% |
| 75.3% Business hotels, full-year | 1.36% | 1.11% | 0.91% | 0.74% | 0.60% |
| 85% | 1.21% | 0.99% | 0.80% | 0.66% | 0.53% |
For the same annual amount, a property at 40% occupancy and ¥6,000 ADR needs a 2.56% pass-through, while one at 85% occupancy and ¥13,600 ADR needs only 0.53% — a gap of about 4.8 times. At the acquisition screening stage, simply plugging the target’s full-year occupancy and rate into this table gives a rough sense of how much of the social insurance expansion must be absorbed through pricing.
Owner-Operated Ryokan — The October 2029 End of Industry Exemption, and When the Transitional Measure Falls Away
The lodging industry has one more issue specific to it. Today, among sole-proprietor establishments that regularly employ five or more people, those in the 17 industries specified by law are mandatory-coverage establishments, but agriculture, forestry, fisheries, lodging, food service and some others are excluded — the so-called exempt industries. In October 2029 this exemption ends, and sole-proprietor lodging establishments also become mandatory-coverage establishments.
However, establishments existing at the effective date are exempted for the time being under a transitional measure. So owner-operated ryokan and minshuku operating as of October 2029 will continue as before for now.
What matters for investors and prospective successors starts here. The transitional measure is tied to “establishments existing at the effective date” and is not necessarily carried over when the owner changes. When a sole proprietorship incorporates, the corporation becomes a mandatory-coverage establishment regardless of headcount, so it is covered before the transitional measure even comes into question. In other words:
| Situation | Treatment from October 2029 | Impact on the business plan |
|---|---|---|
| Continues as a sole proprietorship | Exempt for the time being under the transitional measure. However, no end date for “the time being” has been set so far. | No step for now, but the risk remains that an end date is set later. |
| Incorporation | Corporations are mandatory-coverage establishments regardless of headcount. Full-time-equivalent staff are enrolled immediately. Part-time workers follow the employer-size schedule. | Statutory welfare costs for full-time staff start at the point of incorporation. |
| Transfer to a third party / M&A | Mandatory coverage if the acquirer is a corporation. | Costs absent from the seller’s historical P&L appear on the buyer’s P&L. |
| New openings from October 2029 | Mandatory coverage if a sole-proprietor establishment regularly employs 5+ people. | Build it into the new-opening business plan from the start. |
In lodging succession deals, the seller is often a sole proprietor. If the target’s workforce composition (the number of full-time equivalents and of part-time workers working 20+ hours a week) is pinned down during due diligence, post-acquisition statutory welfare costs can be calculated mechanically as in the table above. The tax side of succession — Japan’s special business succession tax scheme, which covers transfers made by December 2027 — is a separate issue worth reviewing alongside this one.
Linking to Investment Decisions — How to Place the Steps in NOI Underwriting and DSCR
In acquisition practice, the buyer layers expected future cost increases onto the seller’s trailing NOI. The social insurance expansion is one of the few items that can be placed “with certainty,” since its effective dates are fixed. Here we compare a conservative scenario and a pass-through scenario using the 100-room business hotel (Model B).
Purchase price ¥1.2 billion (¥12 million per room) / NOI ¥60 million (NOI yield 5.0%) / LTV 60% = ¥720 million loan / interest rate 2.0%, level payments, 25-year term → annual debt service ¥36.9 million / base DSCR 1.63. An annual increase of ¥2.247 million in statutory welfare costs arises from October 2029.
| Scenario | NOI | NOI yield | DSCR | vs. base |
|---|---|---|---|---|
| Current (through September 2029) | ¥60.00M | 5.00% | 1.63 | — |
| From October 2029, zero pass-through | ¥57.75M | 4.81% | 1.57 | -0.06 |
| Zero pass-through + wages up 3% a year, as of 2035 | ¥57.32M | 4.78% | 1.55 | -0.08 |
| Pass-through scenario (ADR +1.11%) | ¥60.00M | 5.00% | 1.63 | ±0.00 |
Even with zero pass-through, DSCR falls by only 0.06 — nowhere near threatening covenants. What matters more than covenants is the value once capitalized at a cap rate. A ¥2.25 million drop in NOI, at a 5.0% cap rate, means ¥45 million of asset value, or 3.7% of the purchase price. In a bid decided by a few percent, that is too large to ignore.
It is also worth pinning down the size needed in the pass-through scenario. Additional revenue carries distribution costs and similar deductions, so recovering ¥2.247 million at the NOI level requires more than that in nominal revenue.
| Distribution-cost deduction rate | Required additional revenue | Required ADR pass-through | ADR (¥7,300 base) |
|---|---|---|---|
| 0% (direct sales only) | ¥2.25M | 1.11% | ¥7,300 → ¥7,400 |
| 10% | ¥2.50M | 1.24% | ¥7,300 → ¥7,400 |
| 15% | ¥2.64M | 1.31% | ¥7,300 → ¥7,400 |
The interest rate assumption has a far larger effect. At 1.5% and 3.0%, DSCR splits into 1.73 and 1.45; that 0.28 gap is about 4.7 times the 0.06 attributable to the rule change. Put differently, the social insurance expansion is not large enough to sway the discussion of financing terms. It is still worth placing in the annual model because, with the effective dates fixed, leaving it out guarantees the model will miss — and the amount is small enough that including it will not make the modeler look overly conservative.
The same exercise for the 30-room ryokan model (A): with a ¥360 million purchase price, NOI of ¥18 million (5.0% yield), 55% LTV, 2.2% interest and a 20-year term, annual debt service is ¥12.34 million and DSCR is 1.46. Absorbing the ¥1.177 million annual increase from October 2032 with zero pass-through lowers DSCR to 1.36. Here too, the same rule change bites relatively harder the lower the occupancy and the smaller the property. Conversely, this is also the segment with the most room to absorb the cost by lifting the occupancy floor and designing room rates.
Summary — A Cost with a Visible Timetable Can Be Priced In
To sum up, four points.
1. The real step is the employer-size requirement. The October 2026 removal of the wage requirement lost practical meaning once the minimum wage passed ¥1,016 and creates almost no cost step. The four dates to place in the annual model are October 2027 (36+), October 2029 (21+), October 2032 (11+) and October 2035 (abolished).
2. The count is pension-insured employees, not headcount. In lodging, with its high share of part-time workers, the number of people on staff and the number used for the test differ sharply. When your own company is brought in depends on how many full-time equivalents it has.
3. Occupancy determines the per-room burden. The three models’ required ADR pass-through rates — 0.67%, 1.11% and 2.06% — differ threefold, but the gap comes from differences in annual room-nights sold, not wage levels. Raising the occupancy floor directly compresses the required pass-through.
4. The price impact shows up in valuation more than in DSCR. DSCR falls by only about 0.06, but capitalized at a 5.0% cap rate the cost equals 3.7% of the purchase price. The more a buyer wants to sharpen its bids, the more it pays to place the cost year by year.
Faced with a rule change, the hardest cost to handle is one whose timing is unknown. This expansion is the opposite: its arrival dates are fixed by law. For the nine years from 2027 to 2035, the business plan can state how much lands in which year. Being able to write it down also means being able to choose, before each year arrives, whether to absorb it through occupancy, rate or productivity. Cutting labor hours through labor-saving investment is one option, and subsidies for such investment can shorten the payback period; securing staff, including through Japan’s Specified Skilled Worker program, is another lever worth examining alongside it.
Related Articles
- Japan Ends the ¥1.06M Wage Threshold Oct 2026: Hotel Shift Design
- Japan Minimum Wage 2026: Chiba & Aichi ¥1,195, Oct 1-15 Rollout
References and Sources
■ Data Sources
Effective dates are from MHLW and Japan Pension Service publications and the Pension Reform Act (Act No. 74 of 2025); contribution rates from the FY2026 rates and standard monthly remuneration grade tables of the Japan Health Insurance Association and Japan Pension Service; lodging employment composition from the Statistics Bureau’s Labour Force Survey (Basic Tabulation) (January 2025–July 2026); and annual room occupancy from the Japan Tourism Agency’s Overnight Travel Statistics Survey, full-year 2025 (preliminary). ADR is MetroEngines Research & Consulting’s estimated settled ADR (12-month average, September 2025–August 2026, median by prefecture, N=47 prefectures for both business hotels and ryokan; Model C is the average of 6 prefectures: Tokyo, Osaka, Kyoto, Fukuoka, Kanagawa and Aichi). Reference estimated occupancy is based on major booking-site listings (June–August 2026, 12 major prefectures, 1,371 properties / 36,517 rooms).
■ Model Assumptions
Employer contribution rate = (health insurance rate 9.90% + child and child-rearing support levy 0.23%) ÷ 2 + Employees’ Pension 9.15% + child and child-rearing contribution 0.36%; long-term care insurance 0.81% is added for ages 40–64, with 35% of covered workers assumed to be aged 40–64. Standard monthly remuneration follows the grade table, with the ¥88,000 pension floor applied. The three models’ pension-insured employee counts (40, 24, 12), newly covered workers (16, 10, 6) and average monthly wages (¥145,000, ¥125,000, ¥110,000) are assumed values. Required ADR pass-through = annual cost per room ÷ (365 × annual room occupancy) ÷ ADR. DSCR for Model B assumes a ¥1.2 billion purchase, ¥60 million NOI, 60% LTV, 2.0% interest and 25-year level payments (annualized); Model A assumes a ¥360 million purchase, ¥18 million NOI, 55% LTV, 2.2% interest and a 20-year term. The wage growth scenario is 3% a year.
■ Limitations
System details are based on information published and draft cabinet orders as of September 16, 2026 and may change with future cabinet and ministerial orders. Bonuses, commuting allowances and grade changes from wage revisions are not considered. NOI is a simplified room-revenue-only model excluding F&B, other departments and management fees. Estimated settled ADR is an estimate (median error of about 7% against property-level disclosures by listed hotel REITs). Reference estimated occupancy is based on OTA sales inventory and is defined differently from the Japan Tourism Agency’s annual room occupancy. Contribution rates are revised every fiscal year. Coverage in individual cases is determined by the competent pension office.
■ Laws and Regulations (Primary Sources)
- MHLW, “Expansion of Social Insurance Coverage” (Japanese)
- MHLW, “Pension Reform Act (Act No. 74 of 2025): Main Amendments” (Japanese)
- Japan Pension Service, “Expansion of Health Insurance and Employees’ Pension Insurance Coverage to Part-Time Workers” (Japanese)
- Japan Pension Service, “Covered Establishments and Insured Persons” (Japanese)
■ Contribution Rates
- Japan Health Insurance Association, “FY2026 Kyokai Kenpo Contribution Rates Revised from March Premiums (Paid in April)” (Japanese)
- Japan Health Insurance Association, “Notice of FY2026 Contribution Rates” (Japanese) (health insurance national average 9.90%, long-term care 1.62%, child and child-rearing support levy 0.23%)
■ Government Statistics
- Statistics Bureau, Labour Force Survey (Basic Tabulation), employees by industry and employment type (e-Stat table ID: 0003074713, January 2025–July 2026)
- Statistics Bureau, Labour Force Survey (Detailed Tabulation), Annual Average Results (Japanese) (all-industry non-regular share 36.5%, 2025 average)
- Japan Tourism Agency, Overnight Travel Statistics Survey (2025, annual, preliminary) (Japanese) (room occupancy by property type)
- Japan Tourism Agency press release, Overnight Travel Statistics Survey (2025, annual, preliminary) (Japanese)
■ Minimum Wage
- MHLW, “Nationwide List of Regional Minimum Wages” (FY2026 revision: national weighted average ¥1,177, lowest ¥1,085)
■ Market Data
- MetroEngines Research & Consulting — estimated settled ADR (September 2025–August 2026, by prefecture / property type, N=47 prefectures), estimated occupancy (based on major booking-site listings, June–August 2026, 12 major prefectures / 1,371 properties, 36,517 rooms)
Note: The system details in this article are based on laws, draft cabinet orders and government materials published as of September 16, 2026. Some implementation details are left to future cabinet and ministerial orders and may change. All estimates are simplified models with stated assumptions; actual coverage is determined by the competent pension office, and investment decisions should rest on a detailed feasibility study.