

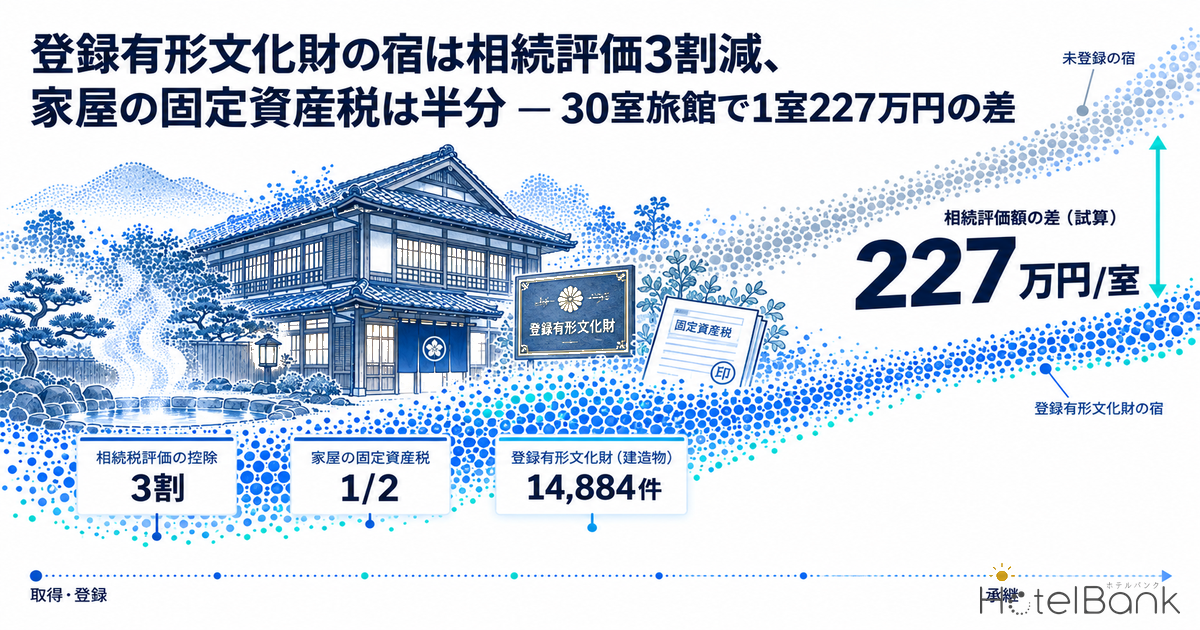
When you acquire and restore a wooden ryokan or modern-era hotel built in the Meiji, Taisho or early Showa period, or when you hand one down to the next generation, whether the building is listed as a national Registered Tangible Cultural Property changes both the annual holding tax and the inheritance-time valuation. Under the Local Tax Act, the taxable base for fixed asset tax on the building is halved, and under the national property valuation rules 30% is deducted from the value of both the building and its site. On the other hand, works that significantly alter the exterior must be notified at least 30 days in advance.
In this article we check the Act on Protection of Cultural Properties, the Local Tax Act, the Basic Circular on Property Valuation and municipal tax-reduction guidelines against their original texts, then model a 30-room, predominantly wooden onsen ryokan to show, per room, the annual holding tax and the inheritance valuation with and without registration. All rules and rates were confirmed against primary sources on September 14, 2026.
Scope of This Article
A separate HotelBank analysis of the 31 municipalities with Building Standards Act exemption ordinances covered the entry question: exemption from building confirmation, i.e. whether a historic building can be built or used as lodging at all. This article deals with registration under the Act on Protection of Cultural Properties and narrows its scope to the cost of continuing to own the building and passing it on. Note that becoming a Registered Tangible Cultural Property does not automatically exempt a building from the Building Standards Act (automatic exemption applies only to designated properties such as National Treasures and Important Cultural Properties). Machiya road-frontage requirements and stock distribution are outside this article’s scope; machiya appear here only as examples.
Metric Definitions Used in This Article
- Holding tax: In this article, the fixed asset tax levied every year on land and buildings (the model uses the standard rate of 1.4%). City planning tax, which applies inside urbanization promotion areas (capped at 0.3%), is shown separately for reference.
- Taxable base: The amount to which the tax rate is applied. It is derived from the fixed asset tax assessed value after special measures and burden adjustments. The special measure for Registered Tangible Cultural Property buildings halves this taxable base.
- Inheritance tax valuation: The value at inheritance under the Basic Circular on Property Valuation. Buildings are valued at the fixed asset tax assessed value × 1.0; land is valued by the roadside-price (rosenka) or multiplier method.
- Estimates: Tax amounts and valuations in this article are reference figures calculated from published laws and circulars and our stated assumptions. Actual tax depends on each municipality’s assessment and the individual inheritance situation, so please consult a tax accountant for specific cases.
- Data sources: Agency for Cultural Affairs, National Tax Agency, Ministry of Internal Affairs and Communications (e-Gov law search), municipal ordinance databases, MetroEngines Research & Consulting
- — Registration runs on notification; designation runs on permission. There are 14,884 Registered Tangible Cultural Properties (structures), about 5.7 times the 2,605 National Treasures and Important Cultural Properties (structures). For an old inn, registration is the realistic option.
- — Halving the building’s fixed asset tax is set by statute. Under Article 349-3(11) of the Local Tax Act, the taxable base of a building that is a Registered Tangible Cultural Property is halved. The site is outside this provision; whether it is relieved depends on each municipality’s reduction guidelines.
- — At inheritance, both building and site get a 30% deduction. This rests on Sections 24-8 and 89-2 of the Basic Circular on Property Valuation. In the 30-room model, the valuation falls from ¥227 million to ¥158.9 million, a gap of ¥2.27 million per room.
- — The big payoff comes at succession. The annual holding tax saving is ¥630,000 (¥21,000 per room). The inheritance tax saving, assuming a 40% marginal rate, is about ¥27.24 million, equal to roughly 43 years of the statutory saving alone.
- — Interiors and wet areas can be changed. Interior-only remodeling needs no notification regardless of scale. Notification is required only for works that alter more than one quarter of the normally visible exterior, and for relocation.
Designation vs. Registration — Permission-Based Important Cultural Properties and Notification-Based Registered Properties
The Act on Protection of Cultural Properties has two mechanisms for protecting buildings. National Treasures and Important Cultural Properties fall under designation: a carefully selected set of important structures, combining strict regulation (alterations require permission) with generous protection. The registration system, introduced by an amendment that took effect on October 1, 1996 (Heisei 8), is described by the Agency for Cultural Affairs as “a lenient protection measure based on notification, guidance and advice,” positioned as a complement to designation.
The registration criterion is, in principle, a structure more than 50 years old that meets one of three tests: it “contributes to the historic landscape of the nation,” it “has become a model of design,” or it “is not easy to reproduce.” Registration starts with the owner’s request; candidates are put forward through the municipal and prefectural boards of education and, after a report from the Council for Cultural Affairs, entered in the Register of Cultural Properties. The most recent report was issued on July 17, 2026.
The counts make the difference clear. According to the Agency for Cultural Affairs’ “Number of Designated Cultural Properties,” as of September 1, 2026 there were 14,884 Registered Tangible Cultural Properties (structures) and 2,605 Important Cultural Properties (structures) (5,597 buildings, including 233 National Treasures). For an owner who wants to keep running a Meiji-, Taisho- or early Showa-era ryokan or Western-style building as lodging, registration is in most cases the option actually available.
| Item | Important Cultural Property (structure) | Registered Tangible Cultural Property (structure) | Unregistered old building |
|---|---|---|---|
| Count (Sep 1, 2026) | 2,605 (5,597 buildings) | 14,884 | — |
| Alterations | Permission required | Notification (30 days in advance) | No procedure under the Cultural Properties Act |
| Fixed asset tax / city planning tax | Building and site exempt (Local Tax Act Art. 348(2)(viii)) | Building: taxable base halved (Art. 349-3(11)) Site: depends on municipal guidelines | Taxed normally |
| Inheritance tax valuation | 70% deducted from building and site values | 30% deducted from building and site values | No deduction |
| National repair subsidy | Subsidy for conservation repairs | 1/2 of design and supervision costs for conservation repairs, etc. | — |
| Building Standards Act | Exempt (Art. 3(1)(i)) | Not automatically exempt (Art. 3(1)(iii) route via ordinance) | Applies |
Inheritance Tax — Sections 24-8 and 89-2 Deduct 30% from Both Building and Site
Inheritance-tax valuation rules are set out in the National Tax Agency’s Basic Circular on Property Valuation. Section 24-8 (valuation of residential land used as the site of a cultural property building) values the site at “the value as if it were not the site of a cultural property building,” minus that value multiplied by a deduction ratio for each category. The ratios are 0.7 for Important Cultural Properties, 0.3 for Registered Tangible Cultural Properties and 0.3 for traditional buildings.
For the building itself, Section 89-2 (valuation of a cultural property building) likewise deducts the 24-8 ratio from the value the building would have if it were not a cultural property. Because the base valuation of a building (Section 89) is its fixed asset tax assessed value × 1.0, a Registered Tangible Cultural Property building is valued at 70% of its fixed asset tax assessed value. The reference point here is the fixed asset tax assessed value, a separate calculation from the fixed asset tax measure that halves the taxable base. Take care not to conflate the two effects.
The Agency for Cultural Affairs’ program brochure also lists, among the incentives, “a 3/10 deduction from inheritance valuation (including land) (NTA circular).” The deduction covers the registered structure and the site that forms a unit with it. Using the building for a lodging business does not change the requirements. Where a corporation owns the property, the same valuation rules feed into the net-asset method used to value its shares, but how much they matter depends on which share-valuation method applies. Confirm this with a tax accountant at the succession-planning stage.
Fixed Asset Tax — Halving the Building Is Statutory; Relief for the Site Depends on the Municipality
Fixed asset tax treats the building and the site differently. Article 349-3(11) of the Local Tax Act sets the taxable base of a building that is a “Registered Tangible Cultural Property as provided in Article 58(1) of the Act on Protection of Cultural Properties” at “one half of the price that would be the taxable base.” This is a statutory measure applied uniformly nationwide, and via Article 702 it also extends to city planning tax (the Agency for Cultural Affairs summarizes it as “taxation at 1/2”).
In the same article, however, the land under the building is included only for buildings that are Registered Monuments or that form Important Cultural Landscapes; the site of a Registered Tangible Cultural Property is not covered by the statutory measure. Whether the site gets relief is decided individually by each municipality through reduction provisions in its tax ordinance or through guidelines. We checked actual guidelines against their original texts.
| Jurisdiction / basis | Covered | Relief | How to read it |
|---|---|---|---|
| (National, statutory) Local Tax Act Art. 349-3(11) | Buildings that are Registered Tangible Cultural Properties | Taxable base halved | Uniform nationwide. Site not included |
| Wakasa Town, Tottori Guidelines on fixed asset tax reduction for Registered Tangible Cultural Properties (Public Notice No. 87 of 2014, effective Apr 1, 2015) | Buildings registered as Registered Tangible Cultural Properties and their premises | 1/2 of the combined taxable base | Example extending relief to the site of nationally registered properties |
| Sakuragawa City, Ibaraki Guidelines for fixed asset tax reduction under Art. 71(1) of the Sakuragawa City Tax Ordinance (Public Notice No. 31 of 2008) | Structures registered by the Minister of Education as tangible cultural properties other than Important Cultural Properties (Appended Table 1) | 1/2 | Reduced as “fixed assets with special circumstances” under the city tax ordinance |
| Nagano City, Nagano Overview of the Registered Cultural Property system (updated Mar 9, 2026) | Buildings | Fixed asset tax reduced to 1/2 | Explains the statutory building measure; no mention of extending it to the site |
| Shisui Town, Chiba Guidelines on fixed asset tax and city planning tax reduction for Town-Registered Tangible Cultural Properties (effective Oct 1, 2023) | Buildings, sites and sites used for effective utilization of “Town-Registered Tangible Cultural Properties” under the town’s ordinance | 1/2 of the fixed asset tax and city planning tax amount | Example of a town’s own registration system, separate from national registration |
| Rikuzentakata City, Iwate Guidelines on fixed asset tax reduction (Public Notice No. 184 of 2013) | Land and buildings designated under prefectural or city cultural property ordinances | Full | Example of full exemption for local designation (reference) |
The comparison shows that some municipalities have guidelines extending relief to the site of nationally registered properties, while others only explain the statutory building measure. Checking with the local municipality’s property tax division whether guidelines for the site exist at the acquisition or succession-planning stage makes holding-tax projections more accurate. Because the text of Wakasa’s guidelines does not make clear how they interact with the statutory measure on the building portion, the model below applies them to the site only.
Modeling a 30-Room Wooden Ryokan — Holding Tax ¥21,000–41,000 Lower per Room per Year; Inheritance Value ¥2.27m Lower per Room
Now we turn the rules into money. The model is a predominantly wooden onsen ryokan that meets the registration criterion of being at least 50 years old in principle. Consistent with HotelBank’s earlier per-room fixed asset tax analysis of hotels, the land’s taxable base is set at 70% of its assessed value and the fixed asset tax rate at 1.4%.
■ Model Assumptions
- Property: a 30-room, predominantly wooden, 90-year-old onsen ryokan (assumed to meet the 50-year registration criterion), owned by an individual.
- Building fixed asset tax assessed value: ¥90 million (¥3 million per room). Because old wooden buildings have often reached the floor of the depreciation adjustment factor, no age-related change in value is assumed.
- Land fixed asset tax assessed value: ¥120 million. Taxable base at 70% of assessed value: ¥84 million (the cap for commercial land).
- Tax rate: fixed asset tax 1.4% (standard rate). City planning tax of 0.3% is shown separately as a reference for properties inside urbanization promotion areas.
- Inheritance tax valuation: building = fixed asset tax assessed value × 1.0 = ¥90 million. For land, using the rule of thumb that roadside prices are about 80% of the official land price and fixed asset tax assessed values about 70%, we used 8/7 of the fixed asset tax assessed value, or ¥137 million (rounded to the nearest ¥1 million).
- Inheritance tax saving: a simplified calculation applying a 40% or 45% marginal rate (bracket rates in the National Tax Agency’s quick-reference table) to the reduction in valuation. In practice, brackets are applied to each statutory share, so the result depends on the composition of heirs.
- Three cases: A = unregistered; B = registered (statutory building measure only); C = registered, in a municipality whose guidelines also halve the tax on the site.
| Case | Building tax | Land tax | Annual fixed asset tax | Per room | vs. A (per room) |
|---|---|---|---|---|---|
| A Unregistered | ¥1.260m | ¥1.176m | ¥2.436m | ¥81,200 | — |
| B Registered (statutory building measure) | ¥0.630m | ¥1.176m | ¥1.806m | ¥60,200 | −¥21,000 (−25.9%) |
| C Registered + site reduction guidelines | ¥0.630m | ¥0.588m | ¥1.218m | ¥40,600 | −¥40,600 (−50.0%) |
| Reference: city planning tax 0.3% | A ¥522,000 → B ¥387,000 | A ¥17,400 → B ¥12,900 | −¥4,500 | ||
The annual saving is ¥630,000 (¥21,000 per room) in Case B with the statutory building measure alone, and ¥1.218 million (¥40,600 per room) in Case C, where the site guidelines also apply. The reduction rate is 25.9% for B and 50.0% for C. B does not reach one half because land accounts for 48% of the holding tax, and the statutory measure does not touch that portion. The higher the land value — the center of an onsen town or the area in front of a tourist station — the more the presence or absence of site guidelines matters.
The link with renovation is also worth noting. When renovation raises the building’s assessed value, each ¥10 million adds ¥140,000 a year in tax if the building is unregistered, but only ¥70,000 if registered. Because halving the taxable base applies whatever the assessed value, the more room renovations raise the building’s value, the larger the saving from registration becomes.
Registration lowers the inheritance valuation from ¥227 million (¥7.567 million per room) unregistered to ¥158.9 million (¥5.297 million per room). The gap is ¥68.1 million, or ¥2.27 million per room. Applying a 40% marginal rate to the gap gives an inheritance tax saving of about ¥27.24 million (¥908,000 per room); at 45% it is about ¥30.65 million (¥1.022 million per room). For reference, if the same building were an Important Cultural Property the deduction would be 70%, bringing the valuation down to ¥68.1 million (¥2.27 million per room).
Setting the recurring holding-tax saving next to the inheritance-tax saving, which applies only once at succession, shows which effect dominates. In Case B, with the statutory building measure only, it takes about 43 years of ¥630,000 annual savings to match the ¥27.24 million inheritance tax saving. Even in Case C, with site guidelines, it takes about 22 years. In other words, the economic value of registration is heavily concentrated at the point of succession. For an owner facing succession within ten years, registration is worth considering less as a holding-cost measure than as a succession-cost measure. For operating companies and funds that acquire and restore properties, the benefit during the holding period amounts to at most halving annual fixed asset tax; the valuation gap matters when the exit is a handover to an individual owner or family company.
Sensitivity Analysis — How Valuation Assumptions and Heirs’ Tax Brackets Change the Conclusion
The model so far depends on one set of values — building ¥90 million, land ¥120 million (inheritance valuation ¥137 million) — and on a 40% marginal rate. We therefore vary the assumptions and show two outputs on two axes: (1) the per-room gap in inheritance valuation, and (2) how many years of the annual holding-tax saving from the statutory building measure (Case B) the inheritance tax saving is equivalent to.
| Building fixed asset tax assessed value (¥m/room) \ Site inheritance valuation (¥m/room) | 2.00 | 3.00 | 4.57 (this model) | 6.00 | 8.00 |
|---|---|---|---|---|---|
| 1.00 | 0.90 | 1.20 | 1.67 | 2.10 | 2.70 |
| 2.00 | 1.20 | 1.50 | 1.97 | 2.40 | 3.00 |
| 3.00 (this model) | 1.50 | 1.80 | 2.27 | 2.70 | 3.30 |
| 4.00 | 1.80 | 2.10 | 2.57 | 3.00 | 3.60 |
| 5.00 | 2.10 | 2.40 | 2.87 | 3.30 | 3.90 |
| Marginal rate \ Site inheritance valuation ÷ building fixed asset tax assessed value | 0.5 | 1.0 | 1.52 (this model) | 2.0 | 3.0 |
|---|---|---|---|---|---|
| 10% | 6 yrs | 9 yrs | 11 yrs | 13 yrs | 17 yrs |
| 20% | 13 yrs | 17 yrs | 22 yrs | 26 yrs | 34 yrs |
| 30% | 19 yrs | 26 yrs | 32 yrs | 39 yrs | 51 yrs |
| 40% (this model) | 26 yrs | 34 yrs | 43 yrs | 51 yrs | 69 yrs |
| 50% | 32 yrs | 43 yrs | 54 yrs | 64 yrs | 86 yrs |
Table (1) shows that whatever the per-room values of building and site, 30% of their sum drops out of the inheritance valuation. Plugging in the values of a property under consideration gives a rough sense of the valuation gap that will apply at succession.
In Table (2), for the building-measure-only case the number of years does not depend on room count or the level of valuations; it is determined solely by the heirs’ marginal rate and the ratio of site value to building value. Against about 43 years in this model (40% rate, ratio 1.52), when the amount received per statutory share is small and the bracket stays at 10–20%, the figure shrinks to 6–17 years for properties with a low site ratio, and fixed asset tax relief during the holding period carries relatively more weight. Conversely, at 40–50% brackets and in places such as onsen-town centers where the site is worth at least twice the building, it exceeds 50 years, and the economic value of registration is concentrated almost entirely at succession. Whether to treat registration as a “holding-cost measure” or a “succession-cost measure” should be judged property by property along these two axes.
When regional banks and shinkin banks assess collateral and business viability, note that the 30% deduction in inheritance valuation is a “tax valuation rule” and does not mean the market price falls by 30%. The difference in annual holding tax depending on whether site guidelines exist (¥588,000 in this model), by contrast, can be factored directly into business-viability assessments as a cash-flow difference.
National Subsidies — Half of Design and Supervision Costs for Conservation Repairs, 65% in Depopulated Areas
Beyond tax, the Agency for Cultural Affairs’ “Guidelines for National Subsidies for Repair Projects of Registered Tangible Cultural Property Structures” (revised April 1, 2020) provide two subsidies. The first is the design and supervision project for conservation repairs, available to owners (or managing organizations). It covers the design and supervision costs of repair works — dismantling repairs, re-roofing, partial exterior repairs, structural reinforcement and the like — and accompanying equipment works such as air-conditioning, water supply and drainage, electrical and fire protection. The subsidy rate is 50% in principle, 65% for municipalities whose area is designated as depopulated, and 80% within Okinawa Prefecture for the time being.
Adoption comes with conditions. Eligible projects must be “models of conservation and utilization” that contribute to community development or regional revitalization making use of the historic landscape. For repair works, the eligible cost is the total project cost minus the sum of expected revenue increases over the five years following completion of the repairs. For uses such as lodging, where revenue is expected to rise after repairs, this deduction shrinks the eligible cost — something to build into the financing plan. The second subsidy, the public utilization project (preparing conservation and utilization plans, installing equipment, seismic measures, etc.), is limited to local governments and corporations the Commissioner for Cultural Affairs deems appropriate.
As for low-interest loans, the Agency’s program brochure lists three incentives for Registered Tangible Cultural Property structures — repair subsidies, inheritance tax and fixed asset tax — and we could find no mention of a loan program. Renovation funding should therefore be structured as ordinary business financing, where loan tenor has a large bearing on the price at which a deal can close.
Renovation Freedom — No Notification for Interiors and Wet Areas; 30-Day Notice for Altering More Than a Quarter of the Exterior or Relocating
The natural question about registration is how far it constrains renovation. Article 64(1) of the Act on Protection of Cultural Properties requires anyone intending to alter the existing state of a Registered Tangible Cultural Property to notify the Commissioner for Cultural Affairs at least 30 days before the intended date. However, “maintenance measures,” “emergency measures necessary due to extraordinary disasters” and “measures based on orders to alter the existing state under other laws” are exempt. When notified, the Commissioner may give necessary guidance, advice or recommendations (Art. 64(3)). Because this is not a permission system, filing the notification and then proceeding with the works is not itself blocked.
The scope of maintenance measures is set in Article 17 of the “Rules on Registration Procedures and Notification Forms for Registered Tangible Cultural Properties”: for structures, cases “where the extent to which the normally visible exterior is impaired is one quarter or less of that exterior (excluding relocation).” The Agency’s brochure is more specific, explaining that interior-only remodeling counts as a maintenance measure, as do repairs of damage such as roof leaks and wall cracks. Nagano City’s guide likewise states that “remodeling and repairs limited to interiors, regardless of their scale or content” are maintenance measures.
| Example of works | Notification | Basis / practical reading |
|---|---|---|
| Updating guest-room interiors, converting Japanese-style rooms to Japanese-Western rooms (interior only) | Not required | Interior-only remodeling is a maintenance measure (Agency brochure) |
| Updating baths, toilets, washbasins and other wet areas (indoors) | Not required | Interior-limited renovation. Exhaust and intake vents on the exterior count toward the exterior area |
| Re-roofing, repainting exterior walls (without changing form or color) | Not required | Works that do not change form, material or color are maintenance measures regardless of scale (Nagano City guide) |
| Repairing roof leaks and wall cracks | Not required | Repair of damage is a maintenance measure |
| Changing windows or cladding within one quarter of the visible exterior | Not required | Rules Art. 17 |
| Altering more than one quarter of the exterior, extensions that change the exterior, relocation | Notify 30 days in advance | Act Art. 64. The Commissioner may give guidance, advice or recommendations |
| Changing floor plans | Depends on content | The brochure lists it as an example of alteration, while treating interior-limited renovation as notification-free. Consult the board of education in advance if structure is affected |
Most renovations that strengthen a guest room’s product are completed within interiors, equipment and wet areas. A room renovation on the order of ¥3 million per room, as assumed in HotelBank’s earlier renovation cost analysis, is also centered on interior and equipment updates. Registration starts to bind with investments that touch the exterior and main structure: extensions to add rooms, façade overhauls, major changes to window layouts. If you want to change these, the 30-day notification and the possibility of guidance, advice or recommendations need to be built into the schedule.
It is also worth checking the record of de-registration. According to the Agency’s registration count data (as of January 1, 2020), of 631 cumulative de-registrations, 202 were “de-registered due to alteration” and 37 due to loss, with the rest resulting from transfer to national, prefectural or municipal designation. If you plan major exterior changes, confirming in advance whether registration — and with it the tax relief — can be kept is a precondition for an investment decision that looks ahead to succession. Note also that a non-penal fine of up to ¥50,000 is provided for failing to notify and similar cases (Act Art. 203).
Registered Properties in Use as Lodging — 9 Facilities Verified in the National Database
Finally, we checked, one by one in the Agency for Cultural Affairs’ “Database of National Cultural Properties,” Registered Tangible Cultural Properties that are still used as lodging today. Names, registration dates and the number of registered structures were all confirmed in the database on September 14, 2026. Each facility continues to use Meiji-to-early-Showa buildings as guest rooms, dining halls or bathhouses, showing that registration and lodging operations can coexist. Registration dates also vary widely, from Mukaitaki (向瀧) in Aizuwakamatsu, registered on December 20, 1996 in the system’s first year, to Gamagori Classic Hotel (蒲郡クラシックホテル), registered in 2022.
| Facility | Location | Registered structures | Main registered structures and registration date |
|---|---|---|---|
| Mukaitaki (向瀧) | Aizuwakamatsu, Fukushima | 4 | Guest-room wing (Kagetsu-no-ma, Ume-no-ma, etc.) and others / Dec 20, 1996 |
| Sekizenkan (積善館) | Nakanojo, Gunma | 1 | Sekizenkan Sanso (1936) / Jun 12, 1997 |
| Fujiya Hotel (富士屋ホテル) | Hakone, Kanagawa | 7 | Main Building (1891), Kikkaso and others / Dec 12, 1997 |
| Arai Ryokan (新井旅館) | Izu, Shizuoka | 15 | Watari-no-Hashi bridge corridor (1899) and others / Sep 2, 1998 |
| Unzen Kanko Hotel (雲仙観光ホテル) | Unzen, Nagasaki | 1 | Unzen Kanko Hotel (1935) / Jan 31, 2003 |
| Kanaguya (金具屋) | Yamanouchi, Nagano | 4 | Kanaguya Ryokan Saigetsuro (1936) / Jul 1, 2003; Annex Rinsenkaku bathhouse / Oct 28, 2011; and others |
| Nikko Kanaya Hotel (日光金谷ホテル) | Nikko, Tochigi | 5 | Main Building (1893; extended and remodeled 1936) and others / Nov 10, 2005 |
| Mampei Hotel (万平ホテル) | Karuizawa, Nagano | 1 | Alps Wing (1936) / Nov 2, 2018 |
| Gamagori Classic Hotel (蒲郡クラシックホテル) | Gamagori, Aichi | 4 | Main Building (former Gamagori Hotel main building, 1934) and others / Feb 17, 2022 |
The registered structures at these nine facilities extend beyond main buildings and guest-room wings to connecting corridors, bathhouses, tea rooms and dining halls. When several buildings at one inn are registered, both the fixed asset tax building measure and the inheritance deduction apply building by building and site by site, so which buildings to register can be designed per building, weighing tax benefits against renovation freedom. A practical combination is to keep updating guest-room wings mainly on the inside while protecting the main building or entrance hall, whose exterior carries the most value, through registration.
Conclusion — Design Registration Building by Building as a Succession-Cost Measure
The tax effects of Registered Tangible Cultural Property status rest on two pillars: halving the taxable base of the building’s fixed asset tax (Local Tax Act, uniform nationwide) and a 30% deduction in the inheritance valuation of building and site (Basic Circular on Property Valuation). Fixed asset tax on the site is outside the statutory measure; some municipalities, such as Wakasa and Sakuragawa, halve it through reduction guidelines, while others do not. In the 30-room wooden ryokan model, the annual holding tax saving is ¥21,000–40,600 per room, the inheritance valuation gap is ¥2.27 million per room, and the inheritance tax saving equals about 22–43 years of holding-tax savings.
Renovation freedom is not as narrow as it may seem. Interiors, wet areas and exterior repairs that do not change form or color need no notification; notification is required only for altering more than a quarter of the exterior and for relocation. The core national subsidy is half of the design and supervision costs of conservation repairs, and for lodging use the expected revenue increase over the five years after repairs is deducted from eligible costs. For owners facing succession within ten years, operating companies that acquire and pass on old inns, and the financial institutions that handle valuation, registration is both a “conservation system” and a succession option that can be designed building by building.
Note: Tax amounts and valuations in this article are estimates applying laws and circulars to stated assumptions. Fixed asset tax assessed values are determined by each municipality, and inheritance tax depends on the composition of heirs, other assets and the application of special measures such as the small-scale residential land exception. Reduction guidelines and their conditions may be revised, so please confirm current practice with the relevant municipality, board of education and a tax accountant before making acquisition, registration or succession decisions.
References and Sources (all checked Sep 14, 2026)
■ Data Sources
Agency for Cultural Affairs “Number of Designated Cultural Properties” (as of Sep 1, 2026) and “Database of National Cultural Properties”; e-Gov law search (Act on Protection of Cultural Properties, Local Tax Act, Rules on Registration Procedures and Notification Forms for Registered Tangible Cultural Properties); National Tax Agency “Basic Circular on Property Valuation” Sections 24-8, 89 and 89-2 and Tax Answer No. 4155; ordinance databases and program guides of five municipalities. All confirmed against primary sources on September 14, 2026.
■ Model Assumptions
A 30-room, predominantly wooden, 90-year-old onsen ryokan (individually owned). Building fixed asset tax assessed value ¥90 million; land fixed asset tax assessed value ¥120 million (taxable base ¥84 million, inheritance valuation ¥137 million); fixed asset tax 1.4% (city planning tax 0.3% as reference). Inheritance tax saving is a simplified calculation multiplying the valuation gap by marginal rates of 40% and 45%. The sensitivity analysis varies building and site values and the marginal rate (10–50%).
■ Limitations
Because fixed asset tax assessed values are set individually by municipalities, depreciation adjustments, burden adjustment measures, the small-scale residential land exception and the composition of heirs are not reflected in the model. The cumulative holding tax and inheritance tax saving are compared simply, without discounting or reassessment. The municipal reduction guidelines are five illustrative examples and do not cover nationwide practice. The Registered Tangible Cultural Properties operating as lodging are nine facilities matched by name in the national database, not a complete count.
■ Systems and Laws
- Agency for Cultural Affairs, “Registered Tangible Cultural Properties (Structures)” (Japanese)
- Agency for Cultural Affairs, “Registration Criteria for Registered Tangible Cultural Properties” (Japanese)
- Agency for Cultural Affairs, “Number of Designated Cultural Properties” (as of Sep 1, 2026, Japanese)
- Agency for Cultural Affairs, “Number of Registered Tangible Cultural Properties (Structures)” (as of Jan 1, 2020, cumulative de-registrations, Japanese)
- Agency for Cultural Affairs, “Guide to the Registered Tangible Cultural Property Structures System” (Mar 2020, Japanese)
- e-Gov law search, “Act on Protection of Cultural Properties,” Arts. 57 and 64 (Japanese)
- e-Gov law search, “Rules on Registration Procedures and Notification Forms for Registered Tangible Cultural Properties,” Art. 17 (Japanese)
- Agency for Cultural Affairs, “Guidelines for National Subsidies for Repair Projects of Registered Tangible Cultural Property Structures” (revised Apr 1, 2020, Japanese)
- Agency for Cultural Affairs, “Database of National Cultural Properties”
■ Taxation
- e-Gov law search, “Local Tax Act,” Art. 348(2)(viii), Art. 349-3(11) and Art. 702 (Japanese)
- Agency for Cultural Affairs, “For Individuals and Corporations Owning Cultural Properties” (Japanese)
- National Tax Agency, “Basic Circular on Property Valuation,” Section 24-8 (valuation of residential land used as the site of a cultural property building, Japanese)
- National Tax Agency, “Basic Circular on Property Valuation,” Sections 89 and 89-2 (valuation of buildings and of cultural property buildings, Japanese)
- National Tax Agency, Tax Answer No. 4155 “Inheritance Tax Rates” (laws as of Apr 1, 2026, Japanese)
■ Municipal Reduction Guidelines and Program Guides
- Wakasa Town, Tottori, “Guidelines on Fixed Asset Tax Reduction for Registered Tangible Cultural Properties” (Japanese)
- Sakuragawa City, Ibaraki, “Guidelines for Fixed Asset Tax Reduction under Art. 71(1) of the Sakuragawa City Tax Ordinance” (Japanese)
- Nagano City, Nagano, “Overview of the Registered Cultural Property System” (Japanese)
- Shisui Town, Chiba, “Guidelines on Fixed Asset Tax and City Planning Tax Reduction for Shisui Town-Registered Tangible Cultural Properties” (Japanese)
- Rikuzentakata City, Iwate, “Guidelines on Fixed Asset Tax Reduction” (Japanese)
■ Estimates and Analysis
- MetroEngines Research & Consulting — estimates of holding tax and inheritance valuation; compilation of the locations of inns operating in registered structures