

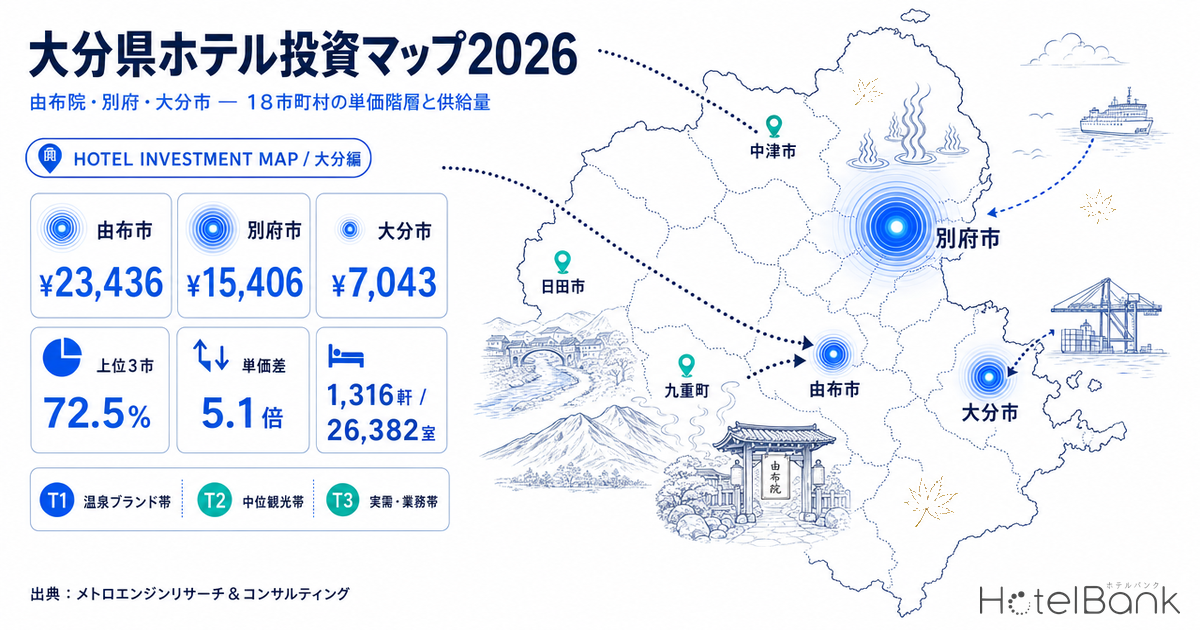
HotelBank has already covered Oita Prefecture from the angle of demand and pricing design: inventory pickup for September stays, booking curves by property type for Saturday, October 3, and the meal premium charged for breakfast and dinner. This article takes a different approach. It is not about how bookings are progressing, but a “static map” of where rooms sit across the prefecture’s 18 municipalities and what they sell for. It is the Oita edition of our prefecture-by-prefecture investment map series, which has so far covered Ishikawa, Toyama, Yamaguchi, Nara, Nagasaki, Wakayama, Niigata, Ehime, Mie, Fukui, Iwate, Kumamoto, Kagoshima, Ibaraki and Yamanashi. It is also the first investment map we have published with Oita as its subject.
The conclusion first. Oita’s lodging market is three completely different markets sharing one prefecture. Yufu City (small, high-rate) has an estimated contracted ADR of ¥23,436 and 7.5 rooms per property. Beppu City (mid-rate, high-volume) is at ¥15,406 with 8,467 rooms, one of the largest room stocks in Kyushu. Oita City (large, business-demand boxes) is at ¥7,043 with 63.0 rooms per property. These three cities account for 72.5% of the prefecture’s daily revenue potential. For investors, the opportunity lies in the “boxes not yet built” within each of these three structures: specifically, 100-room upper-midscale hotels in Beppu, mid-sized products in Yufuin, and the above-¥10,000 band in Oita City. We test this using estimated contracted ADR for all 18 municipalities, the size distribution of a property master covering 1,316 properties and 26,382 rooms, rate observations for 169 properties, estimated OCC in the peak month, and five years of new openings.
Metric Definitions Used in This Article
- ADR (Average Daily Rate): An estimated contracted rate (tax-exclusive equivalent), calculated by applying property-type correction factors to the lowest publicly listed plan on OTAs (per room, 2 guests, tax included). Checked against property-level results disclosed by listed hotel REITs (91 properties, most recent 3 months), the median error is about 7%. These are estimates and differ from each property’s actual contracted rates and accounting figures. Area-level ADR is the median of the properties covered (the level of a typical property in the area).
- Listed price: The average across all plans on OTAs (from room-only to meal-inclusive), per room for 2 guests (tax included). Because its basis differs from estimated contracted ADR, the text explicitly labels it “listed price.”
- OCC (Occupancy): Rooms sold as a share of total rooms in the area (estimated from OTA sales inventory). It is based on how inventory sold on OTAs is being absorbed and differs from a property’s actual overall occupancy.
- RevPAR: Estimated contracted ADR × estimated OCC. In this article it is a reference figure using estimated OCC for August 2026 (the peak month).
- Daily revenue potential: Room stock × RevPAR. An indicator for comparing the relative market size of municipalities; it is not actual revenue.
- Data source: MetroEngines Research & Consulting
- — Oita’s estimated contracted ADR averaged ¥14,784 over 12 months, the highest of Kyushu’s seven prefectures (1.21x second-place Saga at ¥12,173). Ryokan account for 38.5% of room stock, which lifts the prefecture average.
- — Rates across the 18 municipalities differ by 5.1x (Yufu City ¥23,436 vs. Tsukumi City ¥4,602). Rooms per property differ by 8.4x: Yufuin, Beppu and Oita City sit in the same prefecture but have separate industry structures.
- — By market size (room stock × RevPAR), Beppu accounts for 39.4% of the prefecture and the top three cities for 72.5%. In practice, the investment search area narrows to Beppu, Yufuin and Oita City.
- — There are three supply gaps, all in the “upper bands”: 100-room hotels above ¥20,000 in Beppu, above ¥13,000 in Oita City, and mid-sized high-rate properties in Yufuin. The 193 properties opened over the past five years average just 12.8 rooms, and none of that supply targets these gaps.
- — Our model shows repositioning an existing ryokan yields the highest GOP yield at 12.8%, above any new build (total investment ¥780 million; 10.8% even in the most conservative case). Beppu has 1,133 rooms priced below ¥9,000 in estimated contracted ADR.
Executive Summary — 18 Municipalities, a 5.1x Spread in Rates
Let us first pin down the overall picture in numbers. The lodging property master that MetroEngines Research & Consulting tracks for Oita Prefecture contains 1,316 properties and 26,382 rooms (those whose municipality could be identified from their address). Calculating estimated contracted ADR from the properties with observable OTA prices, the prefecture-wide average for the latest 12 months is ¥14,784 (September 2025 to August 2026, monthly sample N=436–470 properties), +3.5% from ¥14,282 a year earlier.
This prefecture average is the highest of Kyushu’s seven prefectures. On the same 12 months and the same estimated contracted ADR basis, Oita’s ¥14,784 is followed by Saga at ¥12,173 (N=145–157 properties), Fukuoka at ¥11,733 (N=460–476), Kumamoto at ¥10,685 (N=366–401), Nagasaki at ¥7,957 (N=249–258), Miyazaki at ¥7,055 (N=158–169) and Kagoshima at ¥6,980 (N=300–322). That is 1.21x second-place Saga and 2.12x last-place Kagoshima. That Oita outranks Fukuoka, home to Kyushu’s largest metropolitan area, shows how unusual its lodging market is. The reason is simple: a large share of Oita’s room stock is onsen ryokan. Of the 1,316 properties in the master, 507 (38.5%) are ryokan, far outnumbering the 134 business hotels and 15 city hotels. Taking the 12-month average estimated contracted ADR by property type, ryokan are at ¥18,265 (N=321 properties) and resort hotels at ¥18,862 (N=41), versus ¥6,642 for business hotels (N=93) and ¥9,988 for city hotels (N=15). There is a step of roughly 2.8x between onsen-oriented and business-oriented properties. A single prefecture average blends these two different markets together. That is why we need to break it down by municipality.
18-Municipality Matrix — Rate Tier × Supply × Property Size
The table below is the core of this article. For each municipality, it lists estimated contracted ADR (12-month average), listed price (all-plan average, for reference), number of properties and rooms, rooms per property, the share of ryokan, estimated OCC in the peak month, and the RevPAR and daily revenue potential derived from them. Tiers are based on estimated contracted ADR: T1 = above ¥14,000 (onsen brand band), T2 = ¥8,000–14,000 (mid-tier leisure band), T3 = below ¥8,000 (business and local-demand band).
| Municipality | Est. contracted ADR | Listed price | Properties | Rooms | Rooms/prop. | Ryokan share | Est. OCC Aug 2026 | RevPAR | Daily revenue potential (¥M) |
|---|---|---|---|---|---|---|---|---|---|
| T1 Yufu City | ¥23,436 | ¥45,476 | 359 | 2,683 | 7.5 | 45% | 85.9% | ¥20,132 | 54.0 |
| T1 Himeshima Village* | ¥17,056 | ¥33,295 | 7 | 50 | 7.1 | 29% | — | — | — |
| T1 Kokonoe Town | ¥16,700 | ¥28,033 | 120 | 1,383 | 11.5 | 54% | 92.9% | ¥15,514 | 21.5 |
| T1 Beppu City | ¥15,406 | ¥31,966 | 312 | 8,467 | 27.1 | 41% | 88.3% | ¥13,603 | 115.2 |
| T1 Hita City | ¥14,795 | ¥35,460 | 86 | 1,404 | 16.3 | 44% | 87.7% | ¥12,975 | 18.2 |
| T2 Hiji Town* | ¥11,887 | ¥37,206 | 8 | 507 | 63.4 | 0% | 81.9% | ¥9,735 | 4.9 |
| T2 Kitsuki City* | ¥11,226 | ¥18,154 | 21 | 348 | 16.6 | 10% | 99.6% | ¥11,181 | 3.9 |
| T2 Kunisaki City | ¥9,007 | ¥18,785 | 31 | 464 | 15.0 | 55% | 92.6% | ¥8,340 | 3.9 |
| T2 Taketa City | ¥8,996 | ¥24,060 | 65 | 685 | 10.5 | 34% | 91.4% | ¥8,222 | 5.6 |
| T2 Usuki City | ¥8,274 | ¥27,041 | 22 | 359 | 16.3 | 64% | 90.9% | ¥7,521 | 2.7 |
| T3 Saiki City* | ¥7,534 | ¥17,239 | 57 | 833 | 14.6 | 18% | 88.0% | ¥6,630 | 5.5 |
| T3 Kusu Town* | ¥7,448 | ¥16,234 | 17 | 176 | 10.4 | 24% | 79.9% | ¥5,951 | 1.0 |
| T3 Bungotakada City* | ¥7,147 | ¥17,485 | 14 | 150 | 10.7 | 43% | 93.5% | ¥6,682 | 1.0 |
| T3 Oita City | ¥7,043 | ¥13,531 | 107 | 6,743 | 63.0 | 15% | 89.9% | ¥6,332 | 42.7 |
| T3 Usa City* | ¥6,732 | ¥20,073 | 22 | 517 | 23.5 | 23% | 78.0% | ¥5,251 | 2.7 |
| T3 Nakatsu City | ¥6,500 | ¥14,511 | 43 | 1,164 | 27.1 | 30% | 92.3% | ¥6,000 | 7.0 |
| T3 Bungo-ono City* | ¥6,005 | ¥13,137 | 13 | 246 | 18.9 | 0% | 94.2% | ¥5,657 | 1.4 |
| T3 Tsukumi City* | ¥4,602 | ¥10,536 | 12 | 203 | 16.9 | 33% | 95.2% | ¥4,381 | 0.9 |
Here is what the table shows, point by point.
First, the rate peak is in Yufu City, not Beppu. Yufu City’s estimated contracted ADR is ¥23,436: 1.40x second-ranked Kokonoe Town (¥16,700) and 1.52x Beppu City (¥15,406). On a listed-price basis (all-plan average) it reaches ¥45,476, the only municipality in the prefecture above ¥40,000. Yufuin Onsen, sometimes called “the Karuizawa of Kyushu,” is known as a cluster of high-end ryokan, and that reputation shows up clearly in actual OTA prices. Compared with onsen towns of similar standing across the prefectural border, the effective rate gap between Kurokawa Onsen and Yufuin had narrowed to ¥665 under the Kyushu travel subsidy (Kyushu Ouen-wari).
Second, rate and supply move in opposite directions. Yufu City counts 359 properties but only 2,683 rooms, or 7.5 rooms per property. Beppu City has 312 properties and 8,467 rooms, or 27.1 rooms per property. Oita City has 107 properties and 6,743 rooms, or 63.0 rooms per property. Rooms per property differ by 8.4x within the same prefecture. Yufuin is “a cluster of small inns,” Beppu is “a dense concentration of mid-sized onsen hotels,” and Oita City is “a cluster of large business hotels”: entirely different industry structures.
Third, occupancy alone does not tell these markets apart. Estimated OCC in August 2026 (the peak month) was 92.9% in Kokonoe Town, 92.3% in Nakatsu City and 91.4% in Taketa City. High-rate onsen towns and low-rate business locations alike sit around 90%. In the peak month, occupancy in every municipality is close to its ceiling. What separates the municipalities is rate, not occupancy. This matters for investment decisions: upside comes not from adding occupancy but only from how rates and room counts are designed.
Re-ranking by Market Size — Beppu 39.4%, Top 3 Cities 72.5%
A rate ranking gives investors only half the picture. Rate alone does not tell you whether Yufu City at ¥23,436 or Beppu City at ¥15,406 is the bigger market. You have to multiply by room stock.
So we calculated daily revenue potential, “rooms × RevPAR,” for each municipality. The ranking changes substantially from the rate ranking. Beppu City comes first at ¥115.2 million per day, 39.4% of the prefecture total (¥292.1 million). Yufu City is second at ¥54.0 million (18.5%) and Oita City third at ¥42.7 million (14.6%). These three cities make up 72.5%. Kokonoe Town follows with ¥21.5 million (7.4%) and Hita City with ¥18.2 million (6.2%); the remaining 13 municipalities combined account for only 11.4%.
When funds or regional banks look for investment opportunities in Oita, the practical target area narrows to three cities: Beppu, Yufuin and Oita City. Kokonoe Town and Hita City form a second group, and everywhere else is a matter of judging individual deals on their own merits.
Inside the Three Markets — Broken Down by Room Count × Rate Band
Now we go down to individual properties. For the 169 properties and 14,027 rooms with 20 or more rooms and estimated contracted ADR observed for 12 consecutive months, we cross-tabulated room-count bands against rate bands. Small inns with fewer than 20 rooms are excluded: they are numerous, their rates vary widely, and they are rarely investment targets.
| Size | <¥9k | ¥9–13k | ¥13–20k | ¥20–30k | ¥30k+ |
|---|---|---|---|---|---|
| 20–29 rooms | 92 | 45 | 96 | 27 | 0 |
| 30–49 rooms | 74 | 149 | 227 | 244 | 76 |
| 50–99 rooms | 336 | 259 | 269 | 150 | 233 |
| 100–199 rooms | 421 | 465 | 161 | 0 | 0 |
| 200+ rooms | 210 | 244 | 591 | 791 | 0 |
| Size | <¥9k | ¥9–13k | ¥13–20k | ¥20–30k | ¥30k+ |
|---|---|---|---|---|---|
| 20–29 rooms | 79 | 20 | 0 | 0 | 0 |
| 30–49 rooms | 117 | 0 | 0 | 0 | 0 |
| 50–99 rooms | 760 | 0 | 0 | 0 | 0 |
| 100–199 rooms | 1,638 | 488 | 190 | 0 | 0 |
| 200+ rooms | 677 | 240 | 0 | 0 | 0 |
Beppu City fills every cell of the 5×5 grid except three. No other onsen destination in Kyushu covers such a wide range of price and size bands at once. The gap is in the lower right: the 100+ rooms × above ¥20,000 cells. One 791-room property above 200 rooms sits in the ¥20,000–30,000 band, but in the 100–199 room band the ceiling is 161 rooms at ¥13,000–20,000, with nothing above. Above ¥30,000 there are only 309 rooms across all size bands (all in the 30–99 room bands).
Oita City, by contrast, packs almost everything into the left third of the grid. Of its 4,209 rooms, 3,271 (77.7%) are below ¥9,000 in estimated contracted ADR, and above ¥13,000 there is just one property with 190 rooms (4.5%). Although it is the prefectural capital, it ranks 14th in the prefecture on rate.
Yufu City raises a different issue from the other two cities. Only 14 properties with 610 rooms have 20 or more rooms, just 22.7% of the city’s 2,683-room stock. There is not a single property with 100 or more rooms. The 20–49 room band has 9 properties with 292 rooms, and the 50–99 room band has 4 properties with 287 rooms. Rates are high, but properties are small, so each deal is small too. This structure is why deals large enough for fund ticket sizes in the prefecture are concentrated in Beppu and Oita City.
Supply Gaps — Three White Spaces
WS1 100-room upper-midscale in Beppu
100–199 rooms × above ¥20,000
Of Beppu City’s 2,883 rooms in properties with 100+ rooms, only one 791-room property above 200 rooms is priced above ¥20,000. The ceiling for the 100–199 room band is 161 rooms at ¥13,000–20,000. A band that is big enough for fund ticket sizes and can still command high rates is empty.
WS2 Above-¥10,000 band in Oita City
All sizes × above ¥13,000
190 of 4,209 rooms (4.5%). 77.7% are concentrated below ¥9,000, and upper-band products are absent. Despite demand drivers as the prefectural capital, a port and a manufacturing cluster, the lodging product is uniform.
WS3 Mid-sized products in Yufuin
50–120 rooms × above ¥20,000
Yufu City has only 610 rooms in properties with 20+ rooms, and none with 100+. Above ¥20,000 with 50+ rooms there are just 2 properties with 135 rooms. Working within local rules on landscape and scale, there is still room to build scale through multi-building layouts.
None of these three gaps exists “because there is no demand.” Two pieces of evidence support the demand side.
The first is occupancy. Estimated OCC in August 2026 was 88.3% in Beppu City (N=169 properties / 5,938 rooms), 85.9% in Yufu City (N=190 properties / 1,897 rooms) and 89.9% in Oita City (N=42 properties / 4,658 rooms). It is the peak month, but all three are effectively at full-house levels. The second is rate growth. Prefecture-wide estimated contracted ADR rose 3.5% YoY, and during the winter onsen season rates ran at around ¥16,000–17,000 or higher for three straight months: ¥16,436 in November 2025, ¥17,297 in December and ¥17,261 in January 2026. The track record of existing stock shows that rates have room to rise.
Supply Pipeline — 193 Properties and 2,478 Rooms in 5 Years, Shrinking to 12.8 Rooms on Average
Even if a gap exists, the investment opportunity shrinks if supply aimed at it is already underway. We checked new openings over the past five years.
| Year opened | Properties | Rooms | Avg. rooms | Projects over 100 rooms |
|---|---|---|---|---|
| 2022 | 19 | 409 | 21.5 | One 177-room business hotel in front of Beppu Station |
| 2023 | 45 | 518 | 11.5 | One 269-room limited-service hotel with onsen in Beppu |
| 2024 | 39 | 417 | 10.7 | One 239-room business hotel with natural hot spring in Oita City |
| 2025 | 50 | 664 | 13.3 | One 255-room business hotel in front of Oita Station |
| 2026 | 40 | 470 | 11.8 | One 161-room resort hotel in Beppu |
| 5-year total | 193 | 2,478 | 12.8 | Only one per year |
Over five years, 193 properties with 2,478 rooms entered the market, equal to 9.4% of the existing 26,382-room stock. On the numbers alone that is not small, but as the 12.8-room average shows, it is overwhelmingly small-format product: whole-house rentals, small ryokan, glamping and villas (for example, Beppu Hontei, a whole-house rental in Beppu that opened in 2026 and accommodates up to three families). Only one project per year exceeded 100 rooms, five in five years.
Moreover, those five projects (177 rooms in front of Beppu Station, 269 rooms in Beppu, 239 rooms in Oita City, 255 rooms in front of Oita Station and 161 rooms in Beppu) are all limited-service or mid-tier resort products in terms of rate band. Over these five years, not one project competed directly with WS1 (100-room hotels above ¥20,000 in Beppu) or WS2 (above ¥13,000 in Oita City).
Looking ahead: in Yufu City, a hotel with 39 rooms, all with private hot-spring baths, is scheduled to open in April 2027, with the top room categories featuring a private sauna and outdoor pool (FHG hotels, “seven x seven Yufuin,” press release of September 2, 2026). This project partly addresses WS3 (mid-sized, high-rate product in Yufuin), but at 39 rooms it will not significantly change Yufuin’s existing structure as “a cluster of small, high-rate properties.” It is reasonable to expect Oita’s supply pipeline to keep flowing toward small, high-rate product for the time being.
Investment Environment — Beppu Station Area Posts Kyushu’s Top Land Value Gain; Listed REITs Own 3 Properties with 695 Rooms
From a land acquisition standpoint, hotel sites in Oita are clearly in a rising phase. In the 2026 roadside land prices (rosenka), Ekimae-dori in Ekimae-machi, Beppu, reached ¥135,000 per ㎡, up 17.4% year over year, the highest rate of increase among Kyushu’s seven prefectures. Continued hotel openings and retail development nearby are cited as the drivers (TOS Online, July 1, 2026). On a published land price basis, Beppu City’s 2025 average was ¥52,862/㎡ (+1.98% YoY) and the average benchmark land price for commercial land was ¥81,830/㎡ (+4.60%). Yufu City’s average land price was ¥67,100/㎡ (+3.07%), second in the prefecture.
Let us also check listed hotel REIT holdings. Three properties with 695 rooms in Oita Prefecture are held by listed REITs, all by Invincible Investment Corporation (8963).
| Property | Location | Rooms | Acquired | Acquisition price | Brand category |
|---|---|---|---|---|---|
| Kamenoi Hotel Beppu (亀の井ホテル 別府) | Beppu City | 322 | Oct 2017 | ¥8,870M | Resort |
| ART HOTEL Oita (アートホテル大分) | Oita City | 228 | Jul 2024 | ¥5,484M | Full-service |
| Hotel MyStays Oita (ホテルマイステイズ大分) | Oita City | 145 | Feb 2018 | ¥1,604M | Limited-service |
Acquisition price per room is ¥27.55 million for Kamenoi Hotel Beppu, ¥24.05 million for ART HOTEL Oita and ¥11.06 million for Hotel MyStays Oita. Because they were acquired at different times, a direct comparison is not possible, but the most recent deal, ART HOTEL Oita acquired in 2024, at ¥24.05 million per room offers one benchmark for acquiring an existing hotel of over 100 rooms in Oita.
Invincible’s reported operating results for July 2026 across its 101 domestic hotels were OCC of 86.3% (+1.9pt YoY), ADR of ¥15,100 (−1.0%) and RevPAR of ¥13,039 (+1.2%). These are nationwide portfolio figures, not Oita-specific results, but they reflect a recent trend in regional cities: occupancy rising while rates stay flat, in a portfolio centered on limited-service hotels.
Development and Repositioning Scenarios — Repositioning Existing Stock Beats New Builds on Yield
Building on the structure above, we modeled four scenarios in Beppu City: three new builds and one acquisition and repositioning of an existing onsen ryokan. Land cost uses Beppu City’s average benchmark land price for commercial land of ¥81,830/㎡. Construction costs use assumed unit costs by property type that reflect recent increases in construction costs. GOP (Gross Operating Profit) is total revenue from rooms, food and beverage, etc., minus direct operating costs such as labor, cost of sales and utilities. It excludes depreciation, interest, rent and property tax. GOP yield is GOP divided by total investment: a measure of the business’s own earning power before financing terms, depreciation and taxes.
| Item | A. Limited-service | B. Upper-midscale WS1 | C. Small luxury | D. Ryokan repositioning Recommended |
|---|---|---|---|---|
| Rooms / room size | 160 rooms / 20㎡ | 120 rooms / 28㎡ | 50 rooms / 45㎡ | 60 rooms (existing) |
| Assumed est. contracted ADR | ¥9,000 | ¥17,000 | ¥35,000 | ¥9,000→¥15,000 |
| Assumed occupancy (annual) | 85% | 80% | 70% | 78% |
| Gross floor area (tsubo) | 1,424 tsubo | 1,613 tsubo | 1,238 tsubo | — |
| Construction / renovation cost | ¥2.99B | ¥3.87B | ¥4.08B | ¥0.42B |
| Land / acquisition cost | ¥0.12B | ¥0.16B | ¥0.25B | ¥0.36B |
| Total investment | ¥3.11B | ¥4.03B | ¥4.33B | ¥0.78B |
| Rooms revenue (annual) | ¥447M | ¥596M | ¥447M | ¥256M |
| Total revenue (annual) | ¥514M | ¥805M | ¥693M | ¥333M |
| GOP margin / GOP | 45% / ¥231M | 33% / ¥266M | 25% / ¥173M | 30% / ¥100M |
| GOP yield (current cost) | 7.4% | 6.6% | 4.0% | 12.8% |
| GOP yield (after construction-period inflation) | 6.5% | 5.7% | 3.5% | 11.7% |
Here is how to read it.
Among the three new builds, limited-service (A) has the highest yield. Its construction cost is lowest and its GOP margin is high. However, the sub-¥9,000 band that A targets is also the most crowded in Beppu City (4 properties with 631 rooms of 100+ room scale already sit in that band). Upper-midscale (B) yields slightly less than A, but there is currently no directly competing property at 100–199 rooms above ¥20,000. How to weigh the 0.8pt yield gap against the difference in competitive environment and rate upside is the core of the WS1 investment decision.
Small luxury (C) has the lowest yield in Beppu City. High-specification construction costs weigh heavily, and at 50 rooms fixed costs are hard to absorb. That said, this assumes an ADR of ¥35,000 in Beppu; in Yufu City the same product might achieve higher rates. Yufu City’s above-¥30,000 band actually contains 7 properties with 333 rooms.
The highest yield comes not from a new build but from repositioning an existing onsen ryokan (D). Assuming a 60-room ryokan acquired at ¥6 million per room, ¥7 million per room spent renovating rooms, baths and dining, and estimated contracted ADR raised from ¥9,000 to ¥15,000, the GOP yield is 12.8% (11.7% after inflation). Total investment of ¥780 million is one-quarter to one-fifth of the new-build scenarios and fits the ticket sizes of regional banks and mid-sized funds.
Beppu City has 8,467 onsen rooms, among the most in Kyushu, and within the 61 observed properties with 20+ rooms (5,160 rooms), 1,133 rooms sit below ¥9,000 in estimated contracted ADR. The upside of lifting this band to ¥13,000–20,000 is the most realistic investment opportunity in Oita; that is what this article’s data shows. Existing properties already have hot-spring rights, locations and a track record of attracting guests. Layering room specifications and pricing design on top of that can reach yields that new builds cannot.
| Sensitivity (Scenario D) | Base | ADR −10% | Occupancy −5pt | Both |
|---|---|---|---|---|
| Est. contracted ADR | ¥15,000 | ¥13,500 | ¥15,000 | ¥13,500 |
| Occupancy (annual) | 78% | 78% | 73% | 73% |
| Rooms revenue | ¥256M | ¥231M | ¥240M | ¥216M |
| GOP | ¥100M | ¥90M | ¥94M | ¥84M |
| GOP yield | 12.8% | 11.5% | 12.0% | 10.8% |
| Est. contracted ADR \ Occupancy (annual) | 72% | 76% | 80% | 84% | 88% |
|---|---|---|---|---|---|
| ¥15,000 | 5.2% | 5.5% | 5.8% | 6.1% | 6.4% |
| ¥16,000 | 5.6% | 5.9% | 6.2% | 6.5% | 6.8% |
| ¥17,000 | 5.9% | 6.3% | 6.6% | 6.9% | 7.2% |
| ¥18,000 | 6.3% | 6.6% | 7.0% | 7.3% | 7.7% |
| ¥19,000 | 6.6% | 7.0% | 7.4% | 7.7% | 8.1% |
Viewed on these two axes, the decision criterion for WS1 becomes clear. Scenario B only catches up with Scenario A (limited-service, 7.4% GOP yield) at an estimated contracted ADR of ¥19,000 with occupancy of 80% or more, or ¥18,000 with 88% occupancy. The base case of ¥17,000 × 80% stays at 6.6%, and a downside to ¥15,000 × 72% drops it to 5.2%. In other words, WS1 is not a case of “fill the gap and win.” The condition for success is whether a hotel in Beppu’s 100–199 room band can clearly break through the current ceiling of ¥13,000–20,000 and hold rates around ¥19,000 year-round. The 7 properties with 333 rooms above ¥30,000 in Yufu City show that higher rates exist in the prefecture, but that track record is for small, high-rate products; whether a 100-room hotel can achieve the same rate is a separate question. Conversely, if a brand and operating setup that meets these conditions can be secured, the absence of direct competitors is a significant entry advantage.
Conclusion — Oita’s Upside Lies in “Lifting Up” More Than “Building New”
Mapping Oita’s lodging market by municipal rate tier and supply comes down to three points.
1. There are three separate markets in the prefecture. Yufu City (estimated contracted ADR ¥23,436, 7.5 rooms per property), Beppu City (¥15,406, 27.1 rooms per property, 8,467 rooms) and Oita City (¥7,043, 63.0 rooms per property). Rates differ by 5.1x and rooms per property by 8.4x. Describing the market with a single prefecture average is meaningless.
2. Market size is concentrated in Beppu. Measured as daily revenue potential (room stock × RevPAR), Beppu City accounts for 39.4% of the prefecture, followed by Yufu City at 18.5% and Oita City at 14.6%. The top three cities make up 72.5%. In practice, the search for investment opportunities narrows to these three cities.
3. Supply gaps are in the “upper bands.” 100-room hotels above ¥20,000 in Beppu, above ¥13,000 in Oita City, and mid-sized high-rate product in Yufuin: in each case demand-side occupancy is around 90%, yet no product is in place. And the 193 properties opened over the past five years average just 12.8 rooms, so no supply is heading into these gaps.
As for investment approach, repositioning existing stock clearly beats new builds on yield. Among Beppu City’s observed properties with 20+ rooms, 1,133 rooms sit below ¥9,000 in estimated contracted ADR. A plan to lift these rooms into the ¥13,000–20,000 band models out at a GOP yield of 12.8% on total investment of around ¥780 million (11.7% after inflation, 10.8% in the most conservative case). For operators seeking onsen ryokan turnaround deals in Kyushu, Oita is one of the few areas that combines all three conditions: deep stock, rate upside and occupancy support.
⚠ Notes on Reading the Data
Estimated contracted ADR in this article is an estimate derived by applying property-type corrections to public OTA prices and differs from each property’s actual contracted rates and accounting figures. Municipal figures focus on the 9 municipalities whose monthly sample was always 8 properties or more (Yufu City, Kokonoe Town, Beppu City, Hita City, Kunisaki City, Taketa City, Usuki City, Oita City and Nakatsu City); others are shown as reference values. In particular, figures for Himeshima Village (monthly sample of 1 property), Kusu Town (1–2 properties), Bungo-ono City (2 properties), Kitsuki City and Tsukumi City (3 properties) are strongly influenced by the prices of a handful of properties and cannot be treated as representative of the area. Estimated OCC is the result for August 2026 (the peak month), not an annual occupancy level. Figure 5 values from September 2026 onward are estimates based on selling prices listed on OTAs at the time of the survey and will change as check-in dates approach. New opening data is based on confirmed OTA listings, so counts for recent months may increase as more listings appear. The development and repositioning scenarios are simplified models; actual investment decisions require a detailed feasibility study.
References and Sources
■ Data Sources
Municipal and prefectural estimated contracted ADR is the 12-month average (September 2025 to August 2026) of a monthly series of estimated contracted rates (tax-exclusive equivalent), derived by applying property-type correction factors to the lowest plan publicly listed on OTAs (2 guests, per room, tax included) (prefecture-wide monthly sample N=436–470 properties). Property and room counts come from our lodging property master of 1,316 properties and 26,382 rooms (those whose municipality could be identified from their address). The property-level rate distribution covers 169 properties and 14,027 rooms with 20+ rooms and rates observed for 12 consecutive months. Estimated OCC is the monthly average for August 2026, estimated from how inventory sold on OTAs is being absorbed (Beppu City N=169 properties / 5,938 rooms, Yufu City N=190 properties / 1,897 rooms, Oita City N=42 properties / 4,658 rooms). New openings are based on confirmed OTA listings (2022–2026, N=193 properties). J-REIT holdings are based on cross-checking our ownership master (as of August 31, 2026, domestic only) against each investment corporation’s disclosures.
■ Model Assumptions
The development and repositioning scenarios are simplified models for Beppu City. Land cost uses the average benchmark land price for commercial land in Beppu City of ¥81,830/㎡; construction costs use assumed unit costs by property type (A ¥2.1M/tsubo, B ¥2.4M/tsubo, C ¥3.3M/tsubo). Rooms revenue = estimated contracted ADR × rooms × occupancy × 365 days; the ratio of total revenue (including ancillary revenue) to rooms revenue is set by property type (limited-service 1.15x, upper-midscale 1.35x, small luxury 1.55x, ryokan repositioning 1.30x). GOP margins by type are A 45% / B 33% / C 25% / D 30%. GOP yield = GOP ÷ total investment, without financing terms, depreciation or taxes. The post-inflation case compounds construction costs at +5% per year, assuming opening in 2029 with a construction midpoint in 2028. Scenario D assumes a 60-room existing ryokan acquired at ¥6M per room and renovated at ¥7M per room, with estimated contracted ADR raised from ¥9,000 to ¥15,000. All occupancy rates are assumed annual figures and differ in basis from the estimated OCC in the text (actual results for the peak month of August 2026).
■ Limitations
Estimated contracted ADR is an estimate based on public OTA prices and does not match each property’s actual contracted rates or accounting figures (median error of about 7% against property-level disclosures by listed hotel REITs). Municipal figures focus on the 9 municipalities whose monthly sample was always 8 properties or more; figures for small-sample municipalities such as Himeshima Village, Kusu Town, Bungo-ono City, Kitsuki City and Tsukumi City are reference values that cannot be treated as representative of the area. Estimated OCC is based on the absorption of inventory listed on OTAs and differs from a property’s actual overall occupancy; it is also the level for the peak month of August 2026, not the full year. Daily revenue potential (room stock × RevPAR) is an indicator for comparing relative market size, not actual revenue. New opening data is based on confirmed OTA listings, so recent months may increase. The development and repositioning scenarios use simplified cost assumptions and do not account for additional costs of major repairs, seismic retrofitting or change of use, securing an operator, or local landscape and zoning regulations. Actual investment decisions require a detailed feasibility study.
■ Market Data
- MetroEngines Research & Consulting — Estimated contracted ADR (18 municipalities in Oita Prefecture, Sep 2025–Aug 2026, monthly sample N=436–470 properties), property master of 1,316 properties / 26,382 rooms, property-level ADR for 169 properties, estimated OCC (August 2026), new openings (based on confirmed OTA listings, 2022–2026, N=193 properties), J-REIT ownership master (as of August 31, 2026)
■ Government Statistics and Public Data
- Ministry of Land, Infrastructure, Transport and Tourism (MLIT), “Statistics on Building Construction Starts” — Construction cost per tsubo by structure (2025)
- MLIT, “Land Price Publication / Prefectural Land Price Survey” — Land price levels in Beppu City and Yufu City
■ REITs, Land Prices and Openings
- Invincible Investment Corporation, “Portfolio List”
- Invincible Investment Corporation, “Monthly Operating Results, July 2026” (August 25, 2026)
- TOS Online, “Rosenka: Beppu Station Area Posts Highest Increase in Kyushu” (July 1, 2026)
- Tochidai Data, “Land Prices, Published Land Prices and Benchmark Land Prices in Beppu City” (2025)
- Diamond Real Estate Research Institute, “Oita Prefecture Land Price and Price per Tsubo Ranking 2025”
- FHG hotels Co., Ltd., “seven x seven Yufuin to Open April 2027” press release (September 2, 2026)