

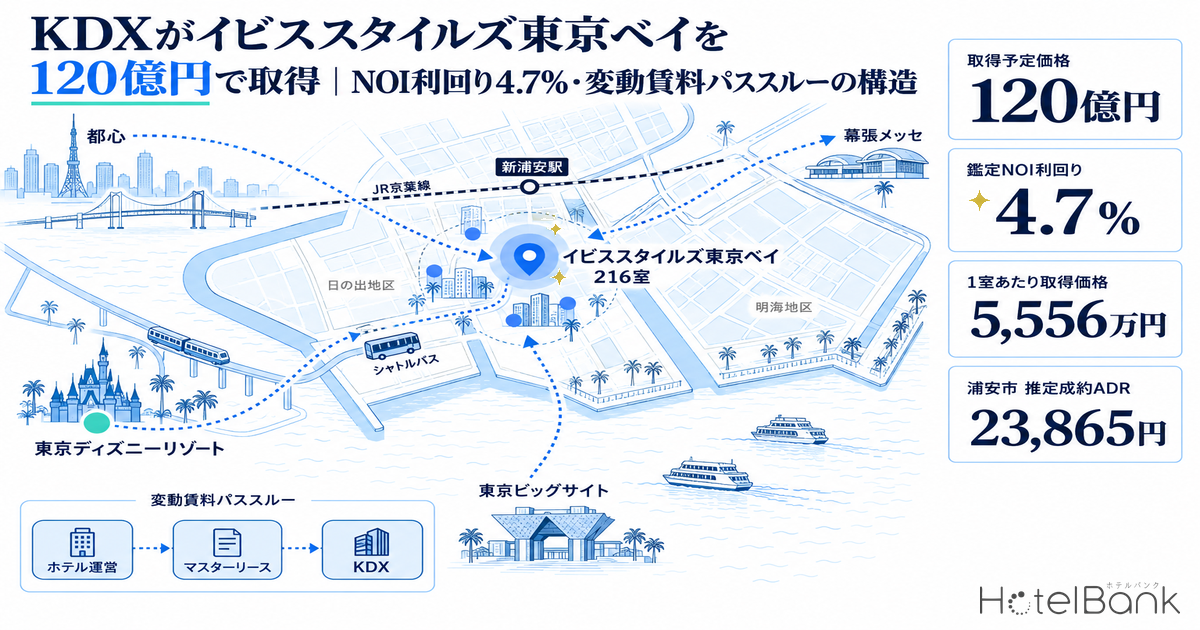
On September 24, 2026, diversified REIT KDX Realty Investment Corporation (KDX不動産投資法人, TSE: 8972) announced that it will acquire ibis Styles Tokyo Bay (イビススタイルズ東京ベイ; 216 rooms) in Urayasu, Chiba Prefecture, for ¥12.0 billion. The appraisal NOI yield is 4.7%, the price works out to about ¥55.56 million per room, and the rent is a pass-through variable rent linked to the hotel’s operating performance. This article breaks down the deal’s rent structure and yields, estimates the rent burden by working back from Urayasu’s estimated settled ADR (trailing 12-month average of about ¥23,900), and examines the Shin-Urayasu location, which draws on three demand sources: leisure from Tokyo Disney Resort, events at Makuhari Messe and Tokyo Big Sight, and business travel to central Tokyo.
Metric Definitions Used in This Article
- ADR (average daily rate): An estimated settled rate (tax-exclusive equivalent), calculated by applying a segment-specific adjustment factor to the lowest publicly listed plan price on OTAs and similar channels (two guests per room, per-room price, tax-inclusive). Checked against property-level results disclosed by listed hotel REITs (91 properties, most recent three months), the median error is about 7%. These are estimates and differ from each property’s actual settled rates and accounting figures. Area-level ADR is the median of the covered properties (the level of a typical property in the area). REIT-disclosed settled ADR is shown excluding consumption tax, and the estimated settled ADR in this article is likewise on a tax-exclusive-equivalent basis.
- OCC (occupancy rate): The share of rooms sold out of the total rooms in the area (an estimate based on OTA sales inventory; consistency checks against REIT monthly disclosures show accuracy within a few percentage points). It is an estimate based on how OTA inventory is absorbed and differs from the actual occupancy of each property as a whole.
- Booking curve / LT: The trajectory of remaining OTA inventory toward the check-in date. LT (lead time) = days until check-in. This article uses LT45 to LT1 only.
- Appraisal NOI, NCF and cap rate: Figures from the real estate appraisal report (Japan Real Estate Institute, valuation date August 1, 2026) disclosed by KDX Realty Investment Corporation.
- Data sources: MetroEngines Research (ADR, OCC); KDX Realty Investment Corporation timely disclosure; Ministry of Land, Infrastructure, Transport and Tourism (MLIT) Real Estate Information Library (land prices).
- — ¥12.0 billion price, 4.7% NOI yield: KDX is buying the 216-room hotel (¥55.56 million per room) for slightly less than 10% below its ¥13.1 billion appraised value (cap rate 4.0%). The NCF-basis yield is 4.4%.
- — Pass-through variable rent: Rent equals the tenant’s pre-tax profit and is settled every three months, so upside in ADR or occupancy shows up in the REIT’s rent on a quarterly basis.
- — Rent is about 39% of room revenue: Estimated using Urayasu’s estimated settled ADR of ¥23,865 (Sep 2025–Aug 2026 average, N=29–30 properties) and an assumed 85% occupancy. Even in a conservative case it stays at 48.9%.
- — Summer ADR fell year on year, yet about 90% of inventory sold: ADR was -14.4% in July 2026 and -11.5% in August, while estimated OCC was 90.6% (August 2026; 15 properties / 3,057 rooms, based on listings on major booking sites). The market is absorbing roughly 2,000 rooms of new supply.
- — Hotels spreading to diversified REITs: After the deal, KDX will own 8 hotel assets worth ¥74.1 billion (5.9% of its portfolio). Within Urayasu, Invincible Investment Corporation and Japan Hotel REIT Investment Corporation own four properties between them, acquired at roughly ¥28–54 million per room.
Summary — Why KDX Wants a 4.0%-Cap Limited-Service Hotel on Variable Rent
In short, this deal shows a diversified REIT adding hotels in a form that lets it capture rent upside. In its disclosure, KDX describes hotels as “variable-rent hotel assets on which we are currently focusing our investment.” After the acquisition, the REIT’s hotel holdings will total 8 properties worth ¥74.1 billion, raising their share of the portfolio (348 properties, ¥1.2529 trillion) to 5.9%.
The yield level is also worth noting. The appraisal uses a cap rate of 4.0% and a DCF discount rate of 3.8%, i.e. the asset is valued at a yield of around 4%. Because the purchase price is slightly less than 10% below the appraised value, however, the NOI yield on the purchase price rises to 4.7%. The seller, MPHOT GK (合同会社MPHOT), is an interested party under Japan’s Act on Investment Trusts and Investment Corporations, and KDX decided on the acquisition after deliberation and approval by its compliance committee in line with internal rules.
On the market side, Urayasu’s estimated settled ADR averaged about ¥23,900 over the latest 12 months, roughly 2.4 times the median for Chiba Prefecture as a whole (about ¥10,100 over the same period). Dividing the appraisal’s assumed rent (operating revenue of ¥628.39 million) by revenue at this ADR, with an assumed 85% occupancy, about 39% of room revenue flows to the property owner as rent.
The Full Transaction — Hotels Account for 2 of 7 Assets in a ¥39.2 Billion Portfolio Reshuffle
The transaction is an asset reshuffle combining the acquisition of one office building, four residential properties and two hotels with the sale of one healthcare facility. The two hotels are scheduled to be acquired on October 1, 2026, and the four residential properties on November 2. KDX explains that, in an inflationary environment, it is acquiring recently built offices and rental apartments where rent increases are expected, along with variable-rent hotel assets.
| Property | Use | Location | Planned acquisition / sale price (¥ million) | Appraisal NOI yield |
|---|---|---|---|---|
| TCS-HD Yokohama Building (TCS-HD横浜ビル) | Office | Yokohama, Kanagawa | 6,080 | 3.9% |
| Presio Sakura Shukugawa (プレジオさくら夙川) | Residential | Nishinomiya, Hyogo | 4,530 | 3.9% |
| Presio Umeda (プレジオ梅田) | Residential | Osaka City, Osaka | 4,480 | 3.7% |
| Presio Tezukayama (プレジオ帝塚山) | Residential | Osaka City, Osaka | 3,100 | 4.0% |
| Presio Nagata (プレジオ長田) | Residential | Higashiosaka, Osaka | 2,979 | 4.2% |
| ibis Styles Tokyo Bay (イビススタイルズ東京ベイ) | Hotel | Urayasu, Chiba | 12,000 | 4.7% |
| BEB5 Okinawa Seragaki (BEB5沖縄瀬良垣) | Hotel | Kunigami District, Okinawa | 6,057 | 6.2% |
| (Sale) Ten (天) | Healthcare | Sapporo, Hokkaido | 2,390 | — |
The seven acquisitions total ¥39.2 billion, of which ibis Styles Tokyo Bay, at ¥12.0 billion, is the largest. Its 4.7% appraisal NOI yield sits in the middle: above the offices and residential assets (3.7–4.2%) and below the Okinawa resort property (6.2%). In the post-transaction breakdown by use, hotels will total 8 properties worth ¥74.1 billion (5.9% of investment). Subtracting the two hotels in this deal from the disclosed post-transaction figures implies that KDX held 6 hotels worth about ¥56.1 billion beforehand, so a single transaction lifts its hotel investment by roughly 30%.
Note that the data our editorial team uses to match REIT-owned properties covers the holdings of seven major hotel-focused REITs: Ichigo Hotel REIT Investment Corporation (3463), Invincible Investment Corporation (8963), Nippon Hotel & Residential Investment Corporation (3472), Japan Hotel REIT Investment Corporation (8985), Hoshino Resorts REIT (星野リゾート・リート投資法人, 3287), Mori Trust Reit (8961) and Kasumigaseki Hotel REIT (401A). Hotels held by diversified REITs such as KDX fall outside this scope, and as of September 28, 2026, ibis Styles Tokyo Bay was not among the holdings of these seven REITs. It is one example of how hotel investors are broadening from hotel-focused REITs to diversified REITs and private funds.
How the Pass-Through Variable Rent Works — The Tenant’s Pre-Tax Profit Becomes the Rent
The rent structure is a pass-through arrangement with a master lease company in between. KDX signs a master lease with Kenedix Property Design (ケネディクス・プロパティ・デザイン), which subleases the hotel to the operating entity (tenant), Shin-Urayasu Hotel Management GK (新浦安ホテルマネージメント合同会社). Day-to-day operations are handled by Accor group’s AAPC Japan (エイ・エイ・ピー・シー・ジャパン) as operator under a management agreement. Because the master lease company pays KDX the same amount it receives in sublease rent, the hotel’s performance flows straight into the REIT’s rental income.
| Item | Details |
|---|---|
| Master lease company | Kenedix Property Design (planned) |
| Master lease type | Pass-through |
| Tenant / hotel management company | Shin-Urayasu Hotel Management GK |
| Operator | AAPC Japan (Accor) |
| Rent formula | Tenant’s pre-tax net income − corporate, inhabitant and enterprise taxes booked in the previous period (floored at ¥0) |
| Rent calculation period | Every three months (Apr–Jun, Jul–Sep, Oct–Dec, Jan–Mar) |
| Master lease fee | (GOP − management fee − asset replacement reserve) × 5% |
| Lease term | October 1, 2026 to December 31, 2030 (automatically renewed annually thereafter) |
| Seller | MPHOT GK (interested party) |
The appraisal report shows operating expenses of only ¥59.65 million (9.5% of operating revenue) against operating revenue of ¥628.39 million. Maintenance and utility costs are borne by the tenant and are not included; expenses consist of the PM fee (¥30.45 million), taxes and public dues (¥24.23 million), repairs (¥3.53 million) and insurance (¥1.44 million). No deduction for vacancy is booked either, as this is “reflected in the cap rate.” Subtracting capital expenditure (¥8.61 million) and an FF&E (furniture, fixtures and equipment) reserve (¥31.77 million) from NOI gives NCF of ¥528.54 million; capitalizing this at 4.0% gives a direct capitalization value of ¥13.2 billion.
Reading the Yields — Price at 91.6% of Appraisal, 4.7% NOI Yield and 4.4% NCF Yield
| Metric | Value | Notes |
|---|---|---|
| Planned acquisition price | ¥12,000 million | ¥55.6 million per room |
| Appraised value | ¥13,100 million | ¥60.6 million per room |
| Value by direct capitalization | ¥13,200 million | Cap rate 4.0% |
| Value by DCF method | ¥12,900 million | Discount rate 3.8%, terminal cap rate 4.1% |
| Cost approach value | ¥8,380 million | Land 77.1%, building 22.2%, FF&E 0.7% |
| Appraisal NOI | ¥568,684 thousand | 4.7% of acquisition price |
| Appraisal NCF | ¥528,542 thousand | 4.4% of acquisition price |
| Earthquake PML | 7.8% | 8-story RC building, total floor area 6,714.68㎡ |
The purchase price is ¥1.1 billion below the appraised value, and the yield rises by that margin: an asset valued at a 4.0% cap rate is being acquired at a 4.7% NOI yield (4.4% on NCF) on the purchase price. Land accounts for 77.1% of the cost approach value (¥8.38 billion), and the income value (¥13.1 billion) is about 1.6 times the cost approach value, which suggests that most of the valuation rests on location and business income rather than on the building itself.
Major hotel REITs already own properties in Urayasu. Invincible Investment Corporation owns MyStays Shin-Urayasu Conference Center (175 rooms) and Hotel MyStays Maihama (90 rooms), and Japan Hotel REIT Investment Corporation owns Oriental Hotel Tokyo Bay (511 rooms) and Hilton Tokyo Bay (828 rooms). (Invincible also holds preferred equity backed by Sheraton Grande Tokyo Bay Hotel.) Because they were acquired at different times, the figures are not directly comparable, but the price per room ranges from about ¥28 million to the mid-¥50 millions. At ¥55.56 million per room for an 8-year-old, 216-room limited-service hotel, this deal is priced above these existing holdings.
| Property | Owner / planned acquirer | Rooms | Acquisition price (¥ million) | Per room (¥ million) |
|---|---|---|---|---|
| ibis Styles Tokyo Bay | KDX Realty Investment Corporation (acquisition planned Oct 2026) | 216 | 12,000 | 55.6 |
| Hotel MyStays Maihama | Invincible Investment Corporation (acquired 2014) | 90 | 4,870 | 54.1 |
| Oriental Hotel Tokyo Bay | Japan Hotel REIT Investment Corporation | 511 | 19,900 | 38.9 |
| Hilton Tokyo Bay | Japan Hotel REIT Investment Corporation | 828 | 26,050 | 31.5 |
| MyStays Shin-Urayasu Conference Center | Invincible Investment Corporation (acquired 2014) | 175 | 4,930 | 28.2 |
Location — A Lodging Cluster South of Shin-Urayasu Station, with 5 Properties and 1,674 Rooms Within 1 km
The property is located at 2-1-1 Hinode, Urayasu, Chiba Prefecture, on a 3,300.46㎡ site in a Category 2 Residential Zone (building coverage ratio 60%, or 70% with the corner-lot allowance; floor area ratio 200%). It is an 8-story reinforced concrete building with a total floor area of 6,714.68㎡, completed in January 2018. Shin-Urayasu Station on the JR Keiyo Line gives easy access to central Tokyo, Makuhari Messe and Tokyo Big Sight, and KDX’s disclosure describes it as “a location where business demand and event-related demand can also be expected.”
The way lodging is clustered around the hotel reveals the character of the location. Counting the hotel-type properties tracked by MetroEngines Research by distance from the property, there are 5 properties with 1,674 rooms (including this one) within a 1 km radius, and 12 properties with 5,155 rooms within 1.6 km. The hotels south of the station sit next to the large hotels lined up along Tokyo Bay in the Hinode and Akemi districts; extending the radius to 4 km to include the Maihama area (about 3–4 km away) brings the total to 34 properties and 8,643 rooms.
| Zoning | Category 2 Residential Zone |
| FAR / coverage | 200% / 60% (corner lot 70%) |
| Site area | 3,300.46㎡ |
| Total floor area | 6,714.68㎡ |
Land prices continue to rise as well. The official published land price for commercial land in front of Shin-Urayasu Station (Mihama 1-chome, Urayasu; commercial zone) went from ¥870,000/㎡ in 2022 to ¥1.06 million/㎡ in 2024 (+17.8% YoY) and ¥1.22 million/㎡ in 2026 (+3.4%). Residential land in Hinode 2-chome near the property (prefectural land price survey) also rose to ¥417,000/㎡ in 2026 from ¥415,000/㎡ in 2025. The pace of increase peaked in 2024 and has since slowed, but prices are still going up.
The Urayasu Market — ADR Peaks in Autumn and Dips in Summer; Summer 2026 Was Below Last Year
According to MetroEngines Research, Urayasu’s estimated settled ADR (median across all hotel types, N=29–30 properties) averaged about ¥23,900 over the 12 months from September 2025 to August 2026, up 2.2% from the previous 12 months (September 2024 to August 2025, about ¥23,300). The monthly high was about ¥30,900 in November 2025 and the low about ¥18,200 in July 2026, a 1.7x swing over the year. Urayasu’s seasonal pattern is high from autumn through year-end and low from the rainy season through summer.
Year on year, the autumn peak season grew strongly, at +13.2% in October 2025 and +11.2% in November, while summer came in below the prior year at -4.8% in June 2026, -14.4% in July and -11.5% in August. The business hotel segment (N=12 properties) showed the same trend, at -6.2% in July and -12.0% in August. The backdrop is rising supply: two properties with 1,113 rooms opened in June 2024, a 750-room large hotel opened in February 2026, and a 140-room property was added in July. These four properties alone have added about 2,000 rooms to the city’s inventory in just over two years, and whether the Maihama–Urayasu bay area could absorb the 750-room opening was a key question for hotel investors ahead of its launch.
| Property | Opened | Rooms |
|---|---|---|
| Tokyo DisneySea Fantasy Springs Hotel (東京ディズニーシー・ファンタジースプリングスホテル) | June 2024 | 475 |
| 1955 Tokyo Bay by Hoshino Resorts (1955 東京ベイ by 星野リゾート) | June 2024 | 638 |
| The Royal Park Hotel Maihama Resort Tokyo Bay (ザ ロイヤルパークホテル 舞浜リゾート 東京ベイ) | February 13, 2026 | 750 |
| GRAND MONday Resort Tokyo Bay Maihama (GRAND MONday Resort 東京ベイ舞浜) | July 2026 | 140 |
| Total (4 properties) | — | 2,003 |
Even so, inventory sold well in summer 2026 despite the added rooms. Urayasu’s estimated OCC based on OTA-listed inventory (15 properties / 3,057 rooms, based on listings on major booking sites) was 88.8% in July 2026, 90.6% in August and 89.8% in September (1st–28th). The business hotel segment (10 properties, 1,214 rooms) was 86.9% in July and 87.6% in August, above Chiba Prefecture as a whole over the same period (84.3% in August; 305 properties, 23,124 rooms). The year-on-year decline in summer ADR can be read as a pricing adjustment to absorb new supply while holding occupancy. For a variable-rent asset, it also means that if ADR recovers, rent rises directly with it.
The booking curve shows bookings continuing to build right up to arrival. For August 2026 check-ins (31-day average; 15 properties / 3,035 rooms, based on listings on major booking sites), estimated OCC was 67.8% at LT45, 81.4% at LT14 and 90.6% at LT1. September check-ins (17 properties / 3,830 rooms) also rose from 73.3% at LT45 to 89.8% at LT1. A structure in which another 6–9 points are added in the two weeks from LT14 to LT1 indicates room to lift revenue through last-minute rate adjustments.
*ADR and OCC in this article use only periods finalized or observed as of the September 28, 2026 survey date (ADR through August 2026; OCC through September 28 check-ins) and do not include estimates based on listed prices for future dates.
Estimating the Rent Burden — About 40% of Room Revenue Flows to the Owner
How heavy is the appraisal’s assumed rent relative to the hotel’s revenue? Dividing appraisal NOI by 216 rooms gives about ¥2.63 million per room per year, or about ¥7,200 per room-night. At an assumed occupancy of 88%, about ¥8,200 per room-night sold remains as property NOI. If Urayasu’s ADR is about ¥23,900, NOI corresponds to about 34% of the room rate.
• Rooms: 216; annual available room-nights = 216 rooms × 365 days = 78,840
• ADR: (1) Urayasu all-type estimated settled ADR, 12-month average ¥23,865 (Sep 2025–Aug 2026, N=29–30 properties); (2) Urayasu business hotel segment, same basis, ¥21,336 (N=12 properties); (3) this property’s own estimated settled ADR, same basis, ¥20,377
• OCC: three full-year levels of 80%, 85% and 90% (Urayasu’s estimated OCC based on OTA-listed inventory ran at a monthly average of about 89–91% from June to September 2026)
• Room revenue = 78,840 room-nights × OCC × ADR. F&B and other revenue are excluded
• Rent = appraisal operating revenue of ¥628,388 thousand (the appraisal’s assumed variable rent); NOI = ¥568,684 thousand
• ADR is an estimate on a tax-exclusive-equivalent basis and differs from actual settled rates and accounting figures. This is a simplified estimate; actual investment decisions require detailed review
| ADR assumption | OCC (assumed) 80% | OCC (assumed) 85% | OCC (assumed) 90% |
|---|---|---|---|
| (1) Urayasu, all types ¥23,865 | 1,505.2 Rent 41.7% / NOI 37.8% | 1,599.3 Rent 39.3% / NOI 35.6% | 1,693.4 Rent 37.1% / NOI 33.6% |
| (2) Urayasu, business ¥21,336 | 1,345.7 Rent 46.7% / NOI 42.3% | 1,429.8 Rent 43.9% / NOI 39.8% | 1,513.9 Rent 41.5% / NOI 37.6% |
| (3) This property ¥20,377 | 1,285.2 Rent 48.9% / NOI 44.2% | 1,365.5 Rent 46.0% / NOI 41.6% | 1,445.9 Rent 43.5% / NOI 39.3% |
In the central case (Urayasu all-type ADR, assumed 85% OCC), room revenue is about ¥1.60 billion and the rent burden is 39.3%. Even in a conservative case with ADR at this property’s own level and OCC lowered to 80%, it is 48.9%, still under half of room revenue. Pass-through rent is what remains after the management fee and reserves are deducted from GOP. Because F&B revenue such as breakfast is added on top, the burden relative to total revenue is lower than shown in this table.
The nature of variable rent becomes clear when the same table is read in reverse. If ADR rises by the gap between cases (1) and (3) (about ¥3,500), room revenue increases by about ¥230 million at an assumed 85% OCC, and much of that is reflected in rent via GOP. Under fixed rent this upside would stay with the operator; under the pass-through structure, the REIT’s unitholders receive it. That is why KDX explicitly states that it is “currently focusing our investment” on such assets.
Investment Considerations — Capturing Upside vs. Seasonal Swings
Upside
In the autumn peak season (October–November), ADR ran +11–13% year on year. With pass-through rent settled every three months, this upside flows straight into distributions.
Depth of Demand
There are three demand sources—leisure, events and business—and estimated OCC stayed at about 89–91% in summer 2026. The family-oriented room mix captures group stays.
Points to Watch
ADR swings 1.7x across the year, so quarterly rent will also fluctuate. About 2,000 rooms of new supply have opened since 2024, making the recovery of summer rate levels the key thing to watch.
| Issue | Details | Metric to monitor |
|---|---|---|
| Rent volatility | Rent = tenant’s pre-tax profit; fluctuates quarterly and is ¥0 if negative | Quarterly rent trend (KDX earnings disclosures) |
| Supply absorption | About 2,000 rooms of new openings since 2024 (four major properties) | Recovery in summer ADR year on year |
| Price level | 4.0% cap rate and ¥55.56 million per room are above existing REIT-owned properties in the city | Realization of the 4.7% NOI yield on acquisition price |
| Lease | Master lease runs to end of December 2030, then renews annually | Terms at renewal |
| Natural disaster | Earthquake PML 7.8% | Liquefaction countermeasures and insurance for reclaimed land |
Conclusion
KDX Realty Investment Corporation’s acquisition of ibis Styles Tokyo Bay is a deal to own a Greater Tokyo limited-service hotel valued at a 4.0% cap rate at a 4.7% NOI yield on the purchase price, through a pass-through variable-rent structure. Working back from Urayasu’s estimated settled ADR (12-month average of about ¥23,900), the rent burden in the central case is about 39% of room revenue.
Summer 2026 was a period of absorbing new supply, and ADR fell year on year. Even so, estimated OCC held at about 90%, and the autumn peak season has a track record of double-digit growth. In Shin-Urayasu, with its three demand sources—Tokyo Disney Resort, Makuhari Messe and Tokyo Big Sight, and business travel to central Tokyo—any recovery in ADR will show up quarterly as REIT rent. As diversified REITs add hotels, this deal illustrates in concrete numbers why they choose variable rent.
References and Sources
■ Data Sources
Estimated settled ADR, estimated OCC, booking curves and the distribution of surrounding lodging based on OTA public prices and inventory (MetroEngines Research & Consulting); KDX Realty Investment Corporation timely disclosure (including the summary of the appraisal report); MLIT Real Estate Information Library (official land prices and prefectural land price survey); published materials from major hotel REITs, Oriental Land and Mitsubishi Estate Hotels & Resorts.
■ Estimation Assumptions
Room revenue = 216 rooms × 365 days × OCC × ADR (tax-exclusive equivalent). ADR is Urayasu all types ¥23,865, business hotel segment ¥21,336 and this property ¥20,377 (all 12-month averages of estimated settled ADR from September 2025 to August 2026); OCC is 80–90% (full-year assumptions). Rent uses appraisal operating revenue of ¥628,388 thousand and NOI uses appraisal NOI of ¥568,684 thousand; F&B and other revenue are excluded.
■ Limitations
Estimated settled ADR is an estimate based on OTA public prices and differs from actual settled rates and accounting figures. Estimated OCC is derived from the absorption of OTA-listed inventory and covers properties listed on major booking sites. Appraisal operating revenue is the assumed variable rent; actual quarterly rent varies with the tenant’s pre-tax profit (¥0 if negative). The per-room price comparables differ in acquisition timing, building age and hotel type.
■ Market Data
- MetroEngines Research & Consulting — Estimated settled ADR for Urayasu and Chiba Prefecture (N=29–30 properties), estimated OCC based on OTA-listed inventory, booking curves, distribution of surrounding lodging
■ REIT Timely Disclosures
- KDX Realty Investment Corporation, “Notice Concerning Acquisition of Domestic Real Estate Trust Beneficiary Interests (One Office Building, Four Residential Properties and Two Hotels) and Disposition (One Healthcare Facility)” (September 24, 2026; Japanese)
- KDX Realty Investment Corporation official website
- Japan Hotel REIT Investment Corporation portfolio list
- Invincible Investment Corporation portfolio (hotels)
■ Government Statistics and Public Data
■ Industry Materials and News
- Oriental Land, “FY2026/3 Financial Results Briefing” (April 28, 2026; Japanese)
- Kanko Keizai Shimbun, “Mitsubishi Estate Group opens 750-room large resort hotel in Maihama” (Japanese)
- Mitsubishi Estate Hotels & Resorts, announcement of the hotel name “The Royal Park Hotel Maihama Resort Tokyo Bay” (Japanese)
- Relo Hotel Solutions, “What Is Hotel GOP?” (Japanese)