

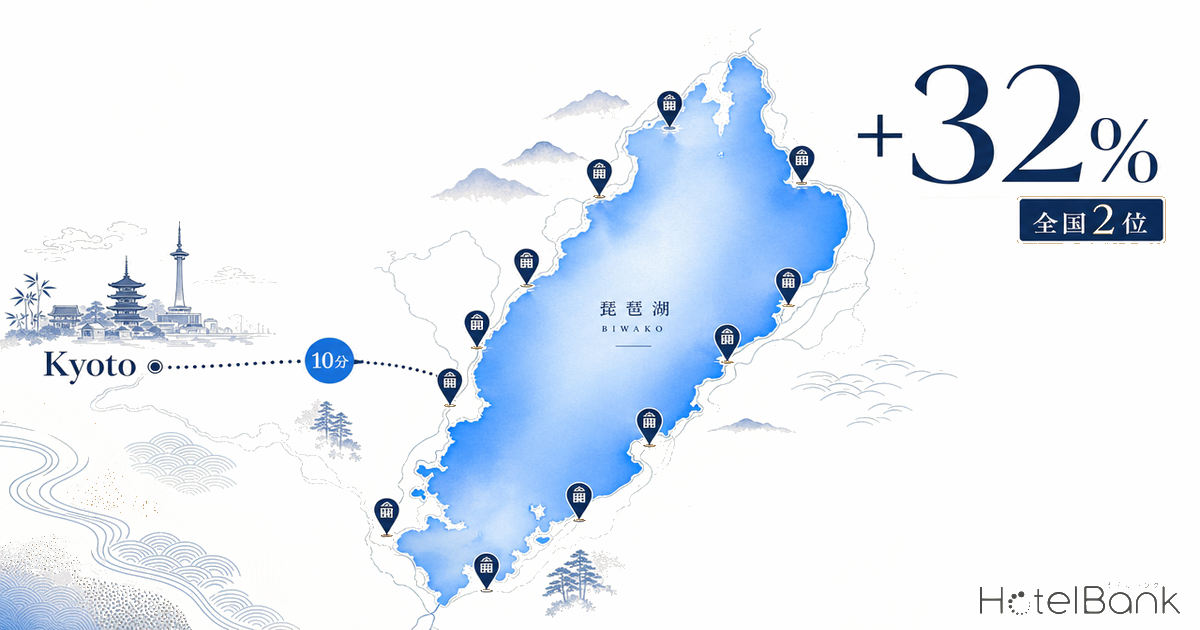
In the summer travel trend survey released by a major OTA on May 22, 2026, one prefecture posted the second-highest growth in search volume nationwide. Behind first-place Tokyo (+48% YoY), Shiga Prefecture came in second at +32%. Regional hotel market analysis has historically concentrated on Tokyo, Osaka, Kyoto, Okinawa, and Hokkaido, with Shiga — home to Lake Biwa — rarely discussed head-on as anything more than a “stealth area.” Yet as overtourism pushes Kyoto’s room rates ever higher, a clear supply-demand opportunity is emerging along Shiga’s lakeshore as a Kyoto “spillover” market. In this report, we compare monthly ADRs for the lakeside hubs of Otsu, Hikone, and Nagahama against central Kyoto, quantify the “10-minute adjacency discount,” and read the differentiation lent by lake-view assets unique to Shiga and the new supply now in motion.
Metric Definitions Used in This Article
- ADR (Average Daily Rate): Average of the public sale prices displayed on OTAs. This differs from realized transaction prices (cross-checking with REIT disclosure data shows a tendency of +25-30% above realized ADR — unsold high-price plans persist on OTAs, structurally inflating the public-price average above the realized price). Per-room rate (tax included) for double occupancy, averaged across all plans (from room-only to packages with meals).
- Central Kyoto ADR: Weighted average (by observation count) of sales data across Kyoto City’s 11 wards (Shimogyo, Nakagyo, Higashiyama, Minami, and others).
- 10-Minute Adjacency Discount: The discount of Otsu City ADR vs. central Kyoto ADR = (Central Kyoto ADR − Otsu City ADR) ÷ Central Kyoto ADR.
- Data Source: MetroEngines Research
- — Shiga Prefecture ranked second nationwide in search volume growth (+32%) in a major OTA’s summer 2026 trend survey. It emerged as a stealth area behind only Tokyo (+48%).
- — Otsu City’s public ADR sits about 27% below central Kyoto on average, with the discount widening to a maximum of 43% during cherry-blossom season. The “10-minute adjacency discount” — JR’s Special Rapid train reaches Kyoto in roughly 10 minutes — has become structural.
- — Shiga’s prefecture-wide public ADR rose +27.3% YoY (from about ¥29,500 to about ¥37,600), with search heat feeding through to realized prices.
- — Lodging supply is concentrated in the southern lake (Otsu), leaving the northern and eastern lakeshores comparatively empty. Lake-view and open-air bath properties at Omi’s iconic inns serve as differentiation assets.
- — Roadside-format new supply is launching in Nagahama and Hino. The region is at an inflection point — from a “Kyoto spillover” market to a “lakeside of choice.”
#2 in Search Nationwide — Why “Japan’s Largest Lake” Suddenly Surfaced
In the major OTA’s summer 2026 trend survey, search growth leaders ran Tokyo (+48%), Shiga (+32%), Fukuoka and Gunma (both +22%), and Nara (+21%). Shiga was singled out for “the natural setting and historic townscapes anchored by Japan’s largest lake — Lake Biwa.” Its appeal — proximity to powerhouse destinations Kyoto and Osaka, paired with a large-scale natural asset in the lake — is drawing travelers seeking to avoid crowds.
This search heat is showing up in actual sale prices. Per MetroEngines Research, Shiga’s prefecture-wide public ADR rose from about ¥29,500 in June 2025 to about ¥37,600 in June 2026 — a +27.3% YoY increase. Search growth (+32%) and ADR growth (+27%) are tracking closely, suggesting heightened interest is materializing as lodging demand. Why did Shiga surface at this particular moment? The answer lies in the price structure of its neighbor, Kyoto. The spillover of Kansai-area human mobility beyond the immediate region was also documented in our Osaka-Kansai Expo Visitor Mobility Analysis.
Source: Major OTA “Summer 2026 Travel Trends” (May 22, 2026), compiled by HotelBank Editorial Team
The “10-Minute Adjacency Discount” — Pricing Edge as a Kyoto Spillover Market
From Otsu Station, JR’s Tokaido Main Line Special Rapid reaches Kyoto Station in about 9-10 minutes. Despite the prefectural boundary, Otsu is effectively inside Kyoto’s commuter and tourist catchment. Even so, room rates in the two areas have diverged sharply. As of June 2026, central Kyoto’s weighted public ADR (across 11 wards) sits at about ¥49,700, while Otsu City stands at about ¥34,400 — a gap of roughly ¥15,300, or 31% discount.
This “10-minute adjacency discount” tends to widen precisely when Kyoto’s rates spike. During cherry-blossom season in April 2026, central Kyoto climbed to about ¥63,800 while Otsu held at about ¥36,400 — pushing the discount to a maximum of 43%. The trailing-12-month average discount is about 27%, with the average gap around ¥13,400. In other words, travelers planning to stay in Kyoto can save over ¥10,000 per night simply by redirecting to Otsu — a structural saving that is now near-permanent.
Source: MetroEngines Research, compiled by HotelBank Editorial Team (Central Kyoto N≈430 properties / Otsu City N≈13 properties)
Worth flagging: Otsu’s ADR is not “stuck low and ignored.” Otsu’s ADR climbed from about ¥27,300 in June 2025 to about ¥40,600 in May 2026, ratcheting up steadily in tandem with Kyoto during peak seasons. The 30%-or-so gap with Kyoto persists only because Kyoto’s pace of price increases continues to outrun Otsu’s. As long as Kyoto’s rates keep testing the ceiling, the lakeside area should retain meaningful room as a price-driven spillover market. The reasons behind Kyoto’s rate trajectory are explored in our Kyoto New Lodging Tax: One-Month ADR Impact piece.
Three Faces of the Lakeshore — Price Levels in Otsu, Hikone, and Nagahama
“Lakeshore Biwa” is hardly monolithic — each subregion has its own price band and character. Otsu (the southern lake gateway) trades around ¥34,000, backed by Kyoto commuter convenience and a deep mix from onsen ryokan (Ogoto Onsen) to business and city hotels. Hikone (the eastern lake) anchors on Hikone Castle tourism, ramping from autumn 2025 to ¥45,000-¥61,000 — the area’s top-tier price band. Nagahama (the northern lake) sits stably at ¥37,000-¥43,000 against the backdrop of historic townscape sightseeing such as Kurokabe Square. Taga Town is a reference point only (single-property sample), running ¥23,000-¥27,000 at the budget end.
Source: MetroEngines Research, compiled by HotelBank Editorial Team
The table below summarizes June 2025 vs. June 2026 ADR by area. Hikone’s growth stands out, driven largely by high-rate resort properties in the observation set and the tourist pull of Hikone Castle and Genkyu-en gardens. Every area outperformed the prior year, confirming that demand is lifting across the entire lakeshore.
| Area | 2025/06 ADR | 2026/06 ADR | YoY | N (properties) |
|---|---|---|---|---|
| Otsu City (Southern Lake) | ¥27,300 | ¥34,400 | +25.9% | 13 |
| Hikone City (Eastern Lake) | ¥25,800 | ¥56,400 | +118.9% | 11 |
| Nagahama City (Northern Lake) | ¥35,400 | ¥37,700 | +6.5% | 12 |
| Taga Town (Reference, N=1) | ¥16,800 | ¥27,200 | +61.7% | 1 |
| Shiga Prefecture (Total) | ¥29,500 | ¥37,600 | +27.3% | ~180 |
*Hikone’s growth runs hot because high-priced resort properties are in the observation set. Taga is a reference point (single-property sample).
Lake Views and Open-Air Baths — Differentiation Assets at Omi’s Iconic Inns
Price advantage as a Kyoto spillover alone won’t sustain long-term traction. What strengthens Shiga’s experiential pull are the lake-view guest rooms and lakeside open-air baths unique to the region. The HotelBank Editorial Team aggregated guest reviews and extracted properties most frequently associated with “open-air baths” — the leaders cluster along the lake.
The top property by review mention count is Biwako Ryokusuitei (大津市 Otsu City, 69 rooms, 122 mentions) at Ogoto Onsen. Eastern Omi’s Happu-no-Yu (99 mentions, 45.6% mention rate) and Otsu’s Biwako Hotel (175 rooms, 61 mentions) follow. By scenic-view mentions, Hikone Castle Resort & Spa (Hikone) and Hotel Piazza Biwako (lakeside) rank high, showing how Shiga’s signature landscape — lake plus castle town — sustains property reputation. On overall scores, small-format Ogoto Onsen ryokan such as Biwako Hanakaido (4.55) and Dantokan Kikunoya (4.67) earn top marks.
Source: Guest review data (HotelBank Editorial Team, 24-month window, 206 Shiga properties)
What these properties share: they are chosen for experience, not price. Lakeside sunsets and the expansive feel of an open-air bath are simply not accessible at a typical city hotel in central Kyoto. These assets preserve a defendable ADR floor while driving repeat business. Even in a spillover market, properties anchored on lake-view differentiation can capture demand well beyond the role of a “cheap Kyoto substitute.”
Lakeshore Property Distribution — Southern Concentration, Northern and Eastern Gaps
The map below plots major ryokan and hotels along Lake Biwa. Circle size reflects room count. At a glance: large hotels and onsen ryokan cluster in Otsu (southern lake), while Hikone (east) and Nagahama (north) are comparatively thin on both property count and scale. Proximity to Kyoto has driven concentration in Otsu — but flip it around, and Hikone and Nagahama — both anchored by tourism cores — still hold supply headroom.
Source: MetroEngines Research / compiled by HotelBank Editorial Team
New Supply Now Underway — Roadside Hotels Land in Nagahama and Hino
Supply is responding to the demand pickup. Within MetroEngines Research’s coverage, new OTA-listed Shiga properties in 2025-2026 cluster in Nagahama City and Hino Town, with roadside hotel openings standing out. HOTEL R9 The Yard Nagahama Inter (44 rooms, opened April 2026) and HOTEL R9 The Yard Gamo Hino (47 rooms, opened January 2026) are both container-format budget hotels near expressway interchanges, designed to capture road-trip tourism and business demand. July 2025 saw the opening of Super Hotel Shiga Nagahama Natural Hot Spring (144 rooms), adding mid-scale onsen-equipped supply to the northern hub of Nagahama.
In Hikone, Trail Inn Hikone (30 rooms, August 2024) and the small-format machiya-style “HATAGO HIKONE” properties have arrived in succession, deepening the castle-town lodging experience. In Nagahama, even smaller premium formats are emerging — single-party-per-day kominka (traditional house) inns, an example of which we covered in our Tsunaguyado Kihe opening report (note: this property is documented in original Japanese coverage only). Together these moves trace a two-pole supply expansion: roadside / budget-class formats absorbing “priced out of Kyoto” demand, plus machiya and onsen formats selling Shiga’s own experiential edge.
| Property | Location | Rooms | OTA Listing Confirmed |
|---|---|---|---|
| HOTEL R9 The Yard Nagahama Inter | Nagahama City | 44 | April 2026 |
| HOTEL R9 The Yard Gamo Hino | Hino Town | 47 | January 2026 |
| Super Hotel Shiga Nagahama Natural Hot Spring | Nagahama City | 144 | July 2025 |
| Trail Inn Hikone | Hikone City | 30 | August 2024 |
| HATAGO HIKONE (Main / Annex) | Hikone City | 15 / 7 | July 2025 |
Source: MetroEngines Research & Consulting (OTA listing-confirmed basis). Listings typically appear several months ahead of opening; recent counts may rise with subsequent listings.
Conclusion — From “Kyoto Spillover” to “Lakeside of Choice”
The supply-demand opportunity for Shiga and Lake Biwa rests on three pillars. First, the demand inflection — search volume #2 nationwide (+32%) paired with +27% YoY ADR — interest and price moving together. Second, the structural “10-minute adjacency discount” — running 20-40% below central Kyoto on a near-permanent basis. Third, differentiation assets — lake views and lakeside open-air baths — that drive choice on something other than price.
The implication for regional hotel investors and Kansai-area OTA managers is clear. As long as Kyoto’s rates keep testing the ceiling, the convenience of the southern lake (Otsu), the tourism cores and supply headroom of the east (Hikone) and north (Nagahama) all stand to function as spillover catchments for Kyoto demand. Whether an area ends up merely as a cheap alternative — or earns its place as a “lakeside of choice” through experiential value — comes down to each property’s playbook. Tactically combining existing strengths (lake views, onsen) with phased peak-season pricing leaves substantial room to convert Kyoto-linked rate increases into compounding revenue opportunity. Shiga is no longer an “untouched stealth area” — it is increasingly an area that belongs formally on Kansai’s lodging map.
⚠ Note on Future-Date ADRs: The ADRs in this report are averages of OTA-published sale prices at the time of survey, and shift as the check-in date approaches. Rates currently set high may decline due to last-minute discounting — please note.
Related Reading
- Kyoto’s New Lodging Tax: One-Month ADR Impact — Kyoto ADR +18.6% YoY, Price Mix Shifts to High-End
- Osaka-Kansai Expo Visitor Mobility Analysis — Confirming Wide-Area Spillover Beyond the Kinki Region
- Field Report: Tsunaguyado Kihe — Single-Party-Per-Day Kominka Inn Opens in Nagahama, Shiga
References & Sources
■ Data Sources
Public ADRs are from MetroEngines Research’s OTA-published price data (monthly, by municipality, for Shiga and Kyoto Prefectures, June 2025-June 2026). Search trends come from the major OTA’s “Summer 2026 Travel Trends” (released May 22, 2026). Review evaluations aggregate 24-month-window data across 206 Shiga properties.
■ Calculation Assumptions
Central Kyoto ADR is the weighted average across 11 wards. Discount = (Central Kyoto ADR − Otsu ADR) ÷ Central Kyoto ADR. Gaps and discounts are derived from each month’s public ADR realized values; peak figures use April 2026 and averages use the trailing 12-month simple mean.
■ Limitations
ADRs are based on OTA-published rates and may differ from realized transaction prices (realized ADR). New-supply coverage is OTA-listing confirmed and may have completeness gaps. Search growth is based on a single OTA’s survey. Occupancy (OCC) is outside this analysis’s scope.
■ Market Data
- MetroEngines Research — OTA-published price data (monthly municipal-level ADR for Shiga and Kyoto), new-opening data (OTA listing-confirmed basis)
- HotelBank Editorial Team — Guest review data (206 Shiga properties, 24-month window)
■ News & Press Releases