

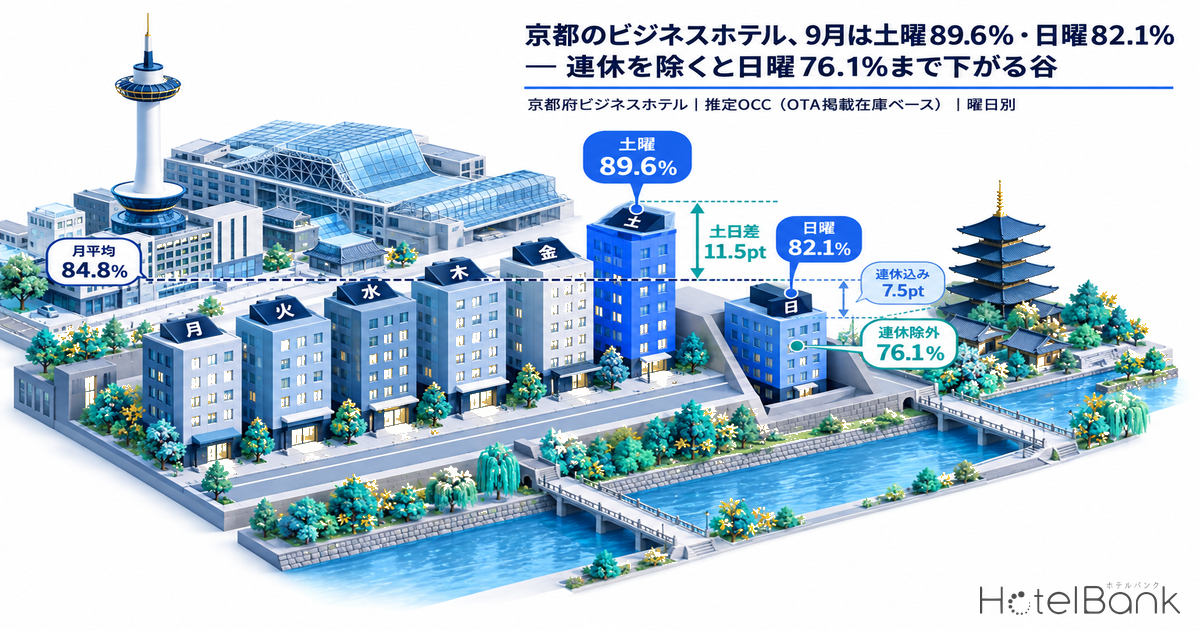
Aggregating the September 2026 estimated OCC (based on OTA-listed inventory) of business hotels in Kyoto Prefecture (N=189–201 properties, about 19,600–20,000 rooms, as listed on major booking sites) by day of week from daily actuals gives a monthly average of 84.8%, with Saturday at 89.6% and Sunday at 82.1% — a Saturday–Sunday gap of 7.5pt. But the month included a five-day holiday run from Saturday, September 19 to Wednesday, September 23 (Autumnal Equinox Day), and within it Sunday (9/20) reached 100.0% and Monday (9/21, Respect for the Aged Day) 99.9%. Strip out those five days to recover the “underlying day-of-week shape” and Sunday falls to 76.1%, widening the gap to Saturday’s 87.6% to 11.5pt. This article isolates, in numbers, the Sunday trough that the holiday-inclusive average hides, and — together with current booking progress (observations from 45 days before the stay date onward) — sets out how to bundle Saturday and Sunday inventory heading into November’s autumn-foliage season.
Scope: business hotels in Kyoto Prefecture, N=189–201 properties (a fixed cohort per stay date, about 19,600–20,000 rooms). City hotels, shown for reference, are N=34–37 properties, about 5,000 rooms. Occupancy in this article is an estimate based on OTA-listed inventory; the estimated transacted ADR used as a price indicator (the transacted price level estimated from OTA and other sales data, tax-exclusive equivalent) is covered monthly only — day-of-week and daily prices are not covered. Definitions are at the end of the article. Data as of October 12, 2026.
- — Saturday 89.6%, Sunday 82.1%: the September 2026 day-of-week averages for Kyoto Prefecture business hotels (N=189–201 properties), estimated from OTA-listed inventory. The monthly average was 84.8%, and the Saturday–Sunday gap 7.5pt.
- — Excluding the holiday: Sunday 76.1%, gap 11.5pt: recomputed over the 25 days that exclude the September 19–23 five-day holiday, Monday drops 4.4pt and Sunday 6.0pt. Thursday and Friday are unchanged.
- — Sunday tracks the same week’s Saturday: the three non-holiday Sundays came in at 69.7%, 75.6% and 83.1%, 7–15pt below the Saturdays of the same weeks (81.8%, 90.7%, 90.4%).
- — In November, Saturdays fill first: Saturday, November 7 went from 77.5% at 45 days out to 85.2% at 30 days out; Sunday, November 8 from 73.3% to 80.2%. The Saturday–Sunday gap at 30 days out is 5.0pt.
- — The last day of a holiday is not the same as the Sunday trough: September 23 came in at 79.2%, and November 23 stands at 77.9% as of 43 days out. Because these are travel-home days, treat them separately from Sundays.
Daily Estimated OCC in September — Three Days of the Five-Day Holiday Shaped the Month
Start with the daily trend for all 30 days of September. Tuesday, September 1 opened the month at 71.0%, and Sunday the 6th was the monthly low at 69.7%; the first ten days ran mainly in the 70s. In the second week, weekends moved into the 90s — Friday the 11th at 87.7%, Saturday the 12th at 90.7% — before dropping 15 points to 75.6% on Sunday the 13th, showing the “fill on Saturday, empty on Sunday” shape. That shape broke in the third week: Saturday the 19th at 95.5%, Sunday the 20th at 100.0%, Monday the 21st (Respect for the Aged Day) at 99.9% and Tuesday the 22nd at 92.3% — four straight days above 90%. The last day of the holiday, Wednesday the 23rd (Autumnal Equinox Day), fell to 79.2%, clearly showing its character as a travel-home day.
Levels stayed high after the holiday as well: from Thursday the 24th (89.2%) through Wednesday the 30th (92.2%), no day fell below 85% except Sunday the 27th (83.1%). Tuesday the 29th, at 93.4%, was the month’s highest weekday, and Monday the 28th (91.7%) and Wednesday the 30th (92.2%) also topped 90% — late-September weekday demand lifted the monthly average of 84.8%. In short, September’s monthly average is a composite of four layers — “the 70s in the first ten days”, “weekdays in the mid-80s from the second week”, “the high 90s during the holiday” and “weekdays around 90% late in the month” — and simply averaging by day of week does not reveal this layered structure.
Source: Compiled by the HotelBank Editorial Team from MetroEngines Research (Kyoto Prefecture business hotels, N=189–201 properties; estimated OCC = based on OTA-listed inventory; September 2026)
Day-of-Week Averages — Excluding the Holiday, the Sunday Trough Is 76.1% and the Saturday–Sunday Gap Widens to 11.5pt
Next, average by day of week. Using all 30 days, the day-of-week averages are Mon 86.7, Tue 83.7, Wed 82.9, Thu 83.8, Fri 85.4, Sat 89.6 and Sun 82.1%: Monday is the highest weekday and Sunday the lowest. But Monday’s 86.7% is an average of four days that includes September 21 (99.9%) during the holiday, and Sunday’s 82.1% likewise includes September 20 (100.0%). Those two holiday days push their weekdays’ averages up by 4–6pt. Kyoto’s day-of-week shape for May–July, a period without such a holiday, is covered in Kyoto Day-of-Week OCC: Thursday 90.4% Edges Friday, May–Jul 2026, which serves as the baseline for comparison with September.
Excluding the five days from Saturday, September 19 to Wednesday, September 23 and recomputing gives Mon 82.3, Tue 81.5, Wed 83.9, Thu 83.8, Fri 85.4, Sat 87.6 and Sun 76.1%. Monday falls 4.4pt and Sunday 6.0pt, and the Saturday–Sunday gap widens from 7.5pt to 11.5pt. The three non-holiday Sundays came in at 69.7% (9/6), 75.6% (9/13) and 83.1% (9/27); they fill up more toward month-end, but each sits 7–15pt below the Saturday of the same week (81.8%, 90.7%, 90.4%). Meanwhile the Thursday and Friday averages are unchanged before and after the exclusion (83.8%, 85.4%), Tuesday falls 2.2pt, and Wednesday rises 1.0pt as the last day of the holiday (79.2%) drops out. The holiday had its biggest effect on three days: Saturday, Sunday and Monday. A separate HotelBank analysis applying the same procedure to business hotels in Osaka Prefecture found a Sunday trough of 15.8pt even after excluding the holiday, so Kyoto’s 11.5pt is easier to place when read alongside the neighbouring market.
For reference, applying the same procedure to city hotels (N=34–37 properties, about 5,000 rooms) gives a monthly average of 85.3%; including the holiday, Saturday is 89.7% and Sunday 85.0% (gap 4.7pt), and excluding it, Saturday 88.1% and Sunday 80.1% (gap 8.0pt). The Sunday drop is smaller than for business hotels, likely because city hotels carry more multi-night and leisure stays — but in both categories Sunday falls below 80% once the holiday is excluded.
Source: Compiled by the HotelBank Editorial Team from MetroEngines Research (Kyoto Prefecture business hotels; September 2026; estimated OCC = based on OTA-listed inventory)
| Day | Business, all 30 days | Business, excl. holiday | City, all 30 days | City, excl. holiday |
|---|---|---|---|---|
| Mon | 86.7% | 82.3% | 87.4% | 83.3% |
| Tue | 83.7% | 81.5% | 84.9% | 82.7% |
| Wed | 82.9% | 83.9% | 83.4% | 83.8% |
| Thu | 83.8% | 83.8% | 82.5% | 82.5% |
| Fri | 85.4% | 85.4% | 85.2% | 85.2% |
| Sat | 89.6% | 87.6% | 89.7% | 88.1% |
| Sun | 82.1% | 76.1% | 85.0% | 80.1% |
| Sat–Sun gap | 7.5pt | 11.5pt | 4.7pt | 8.0pt |
| Monthly average | 84.8% | 83.1% | 85.3% | 83.6% |
Source: Compiled by the HotelBank Editorial Team from MetroEngines Research (excl. holiday = day-of-week averages over the 25 days excluding the five days of September 19–23. Business N=189–201 properties; city N=34–37 properties)
On the price side, the estimated transacted ADR (final) for Kyoto Prefecture business hotels in September 2026 was ¥11,700 (N=327 properties), −2.4% against ¥12,000 a year earlier (N=319 properties, final). September ran at occupancy in the mid-80s while rates came in slightly below last year, so it is worth keeping in mind that conceding too much on rate to fill the Sunday trough would thin the month’s ADR further.
Late-October to November Weekend Progress — Saturdays Fill First; Sundays Add 7–8pt from 45 Days Out
Now turn to current booking progress for upcoming stay dates. The scope is Kyoto Prefecture business hotels (N=192–196 properties, about 19,000–19,300 rooms), using only observations from 45 days before the stay date up to the latest (observed October 11). The nearest weekend, Saturday, October 24, started at 84.2% at 45 days out, reached 90.4% at 30 days out and 95.4% at 13 days out — 11.2pt added over 45 days. Sunday the 25th of the same week went from 78.2% at 45 days out to 82.0% at 30 days out and 86.6% at 14 days out, an 8.4pt gain; at the latest observation the Saturday–Sunday gap is 8.8pt. Saturday, October 31 went from 82.8% at 45 days out to 90.7% at 20 days out, and the following Sunday, November 1, from 73.5% to 81.4% at 21 days out — again Sunday is tracking roughly 9pt below Saturday.
Saturday, November 7, at the start of the autumn-foliage season, rose 9.3pt: 77.5% at 45 days out, 85.2% at 30 days out and 86.8% at 27 days out. Sunday the 8th went 73.3% at 45 days out, 80.2% at 30 days out and 80.8% at 28 days out, a 7.5pt gain. Saturday, November 14 has moved from 82.6% at 45 days out to 88.0% at 34 days out, and Sunday the 15th from 79.3% to 83.5% at 35 days out. Saturday, November 21 was already at 93.2% at 45 days out and has reached 94.5% at 41 days out; Sunday the 22nd went from 88.2% to 89.6%; and Monday the 23rd (Labor Thanksgiving Day), the last day of the three-day weekend, from 76.8% to 77.9% at 43 days out — the same pattern as September’s five-day holiday (79.2% on the 23rd), in which the middle days fill first and the last day lags.
Lining up the weekend pace, Saturday is 3–9pt ahead of Sunday at 45 days out (6.0pt for 10/24–25, 4.2pt for 11/7–8), and then fills faster than Sunday, so by 30 days out the gap has widened from its 45-day level: 8.4pt for 10/24–25 and 5.0pt for 11/7–8 (10/31–11/1 is roughly flat, 9.3pt → 9.1pt). Sundays also gain 7–8pt over 45 days, which should not be overlooked, but the picture of Saturday approaching 90% while Sunday stays around 80% points the same way as September’s “11.5pt Saturday–Sunday gap excluding the holiday”. A separate HotelBank analysis of Kyoto’s autumn Saturdays found that they add double-digit points between 45 days out and the stay date, so the decision on bundling Sunday should be made with that further Saturday pickup factored in.
Source: Compiled by the HotelBank Editorial Team from MetroEngines Research (Kyoto Prefecture business hotels, N=193–195 properties; estimated OCC = based on OTA-listed inventory; observations from 45 days before the stay date up to October 11, 2026)
| Stay date | 45 days out | 30 days out | Latest observation (days out) | Gain since 45 days out |
|---|---|---|---|---|
| Sat 10/24 | 84.2% | 90.4% | 95.4% (13 days out) | +11.2pt |
| Sun 10/25 | 78.2% | 82.0% | 86.6% (14 days out) | +8.4pt |
| Sat 10/31 | 82.8% | 87.2% | 90.7% (20 days out) | +7.9pt |
| Sun 11/1 | 73.5% | 78.1% | 81.4% (21 days out) | +7.9pt |
| Sat 11/7 | 77.5% | 85.2% | 86.8% (27 days out) | +9.3pt |
| Sun 11/8 | 73.3% | 80.2% | 80.8% (28 days out) | +7.5pt |
| Sat 11/14 | 82.6% | — | 88.0% (34 days out) | +5.4pt |
| Sun 11/15 | 79.3% | — | 83.5% (35 days out) | +4.2pt |
| Sat 11/21 | 93.2% | — | 94.5% (41 days out) | +1.3pt |
| Sun 11/22 | 88.2% | — | 89.6% (42 days out) | +1.4pt |
| Mon 11/23 (holiday) | 76.8% | — | 77.9% (43 days out) | +1.1pt |
Source: Compiled by the HotelBank Editorial Team from MetroEngines Research (Kyoto Prefecture business hotels, N=192–196 properties; estimated OCC = based on OTA-listed inventory. “—” marks stay dates whose observations have not yet reached 30 days out. As observed October 11, 2026)
As a price reference, the estimated transacted ADR for Kyoto Prefecture business hotels in November is ¥24,100 (N=319 properties), an estimate based on current sales; because the basis differs from last November’s final figure of ¥21,600 (N=314 properties), a straight comparison has to wait for the month to be finalized. Still, it is clearly a month selling at roughly twice September’s ¥11,700 (final), so measures to fill the Sunday trough will have a larger effect on rate than in September.
For Revenue Managers Running Business Hotels in Kyoto Prefecture — Implications and Action Plan
1. Set your day-of-week baseline on “the month excluding the holiday”. If you benchmark against September’s holiday-inclusive day-of-week average (Sunday 82.1%), your own Sunday drop will look in line with the market. Using Sunday 76.1% and the 11.5pt Saturday–Sunday gap excluding the holiday as the baseline lets you tell whether your Sunday is deeper or shallower than the market, and so whether Sunday-specific measures are needed. The 1.7pt difference between the market’s monthly average of 84.8% and the holiday-excluded 83.1% can be used as a correction when reading your own September results — it is the lift that the five holiday days gave the whole month.
2. Sunday nights fill differently from “stay-overs from Saturday” and from “pre-stays before a Monday start”. In September, the Monday after Sunday returned to weekday levels at 82.3% excluding the holiday, so Monday business demand does not automatically generate Sunday stays. Meanwhile, among the three non-holiday Sundays (69.7%, 75.6%, 83.1%), the week in which Saturday reached only 81.8% (Saturdays: 81.8%, 90.7%, 90.4%) also had the lowest Sunday at 69.7% — Saturday demand appears to drive Sunday’s level. Designing Sunday inventory in two parts — one tied to Saturday demand through multi-night conditions, the other sold on its own as a pre-stay for Monday business trips — makes it easier to see which kind of demand is reaching your hotel.
3. Saturdays fill first in November, so decide on bundling Sunday by 30 days out. At 30 days out, Saturday, November 7 stood at 85.2% and Sunday the 8th at 80.2% — a 5.0pt gap already. If you try to sell Sunday with a multi-night condition only after Saturday nears 90%, there is no Saturday inventory left to attach it to, so the conditions for selling Saturday inventory as a set with Sunday need to be fixed before your Saturday progress reaches the market’s 30-day level (around 85%).
4. Do not treat the last day of a holiday the same as a weekday trough. September 23 (Wednesday, Autumnal Equinox Day) at 79.2% and November 23 (Monday, Labor Thanksgiving Day) at 77.9% as of 43 days out show the pattern in which the middle days of a holiday reach the 90s while the last day lags. This is a travel-home-day problem, not a day-of-week problem, and the measures used for the Sunday trough will not fill it. There is room to sell the last day of a holiday the way you sell weekdays — to short stays from nearby areas and as pre-stays for the next day’s weekday business trips.
Action Plan by Time Horizon — This Week, Within Two Weeks, Next Month
| Horizon | Action | Decision trigger (figures from this article) | Aim |
|---|---|---|---|
| Today to this week | Re-aggregate your September results into a day-of-week shape excluding the holiday | If your Saturday–Sunday gap excluding the holiday is larger than the market’s 11.5pt | Separate whether the Sunday trough is market-driven or specific to your hotel |
| Today to this week | Check your progress for October 24–25 and October 31–November 1 against the market | If your Sunday 10/25 is below the market’s 86.6% at 14 days out, or Sunday 11/1 below 81.4% at 21 days out | Switch the sales approach for near-term Sunday inventory toward Monday pre-stays |
| Within two weeks (by 30 days before 11/7–8) | Fix the conditions for the share of November Saturday inventory to be sold bundled with Sunday | If your Saturday 11/7 is ahead of the market’s 85.2% at 30 days out while Sunday 11/8 has not reached 80.2% | Secure a window for steering guests into Sunday stay-overs before Saturday sells out |
| Within two weeks | Decide how to sell November 14–15 and 21–23 weekends versus the last day of the holiday | If Saturday 11/21 fills early, as with the market’s 94.5% at 41 days out, while Monday 11/23 (holiday) is lagging around 77.9% | Bring forward preparations to fill the last day of the holiday with weekday-type demand |
| Toward next month | Decide in advance how much Sunday price discount to tolerate relative to November’s rate level | If your November rates are far from the market’s current estimate of ¥24,100 (a value that can change) | Estimate the effect on monthly ADR of going after Sunday occupancy |
| Toward next month | Rebuild day-of-week shapes for December onward on a holiday-excluded basis | Using the lift September’s holiday gave (Monday +4.4pt, Sunday +6.0pt) as a guide, apply the same correction to months that include the year-end and New Year holidays | Make month-by-month day-of-week shapes comparable on the same yardstick |
Source: Compiled by the HotelBank Editorial Team (figures in the decision triggers refer to the aggregates in the body)
Summary — Three Yardsticks for Reading Day-of-Week Shape
First, because the monthly day-of-week shape changes with the presence of holidays, use “day-of-week averages excluding the holiday” as the baseline. For Kyoto Prefecture business hotels in September 2026, the Saturday–Sunday gap of 7.5pt including the holiday became 11.5pt excluding it, and Sunday fell to 76.1%. Second, look at the Sunday trough in two parts: the share filled by stay-overs from Saturday and the share filled by Monday pre-stays. Excluding the holiday, September’s Mondays were at weekday levels (82.3%), and Monday demand alone did not fill Sundays. Third, Saturdays fill first in November’s foliage season, so decide the conditions for bundling Sunday with Saturday by 30 days out. Saturday, November 7 was at 85.2% and Sunday the 8th at 80.2% at 30 days out; the gains since 45 days out were 9.3pt for Saturday and 7.5pt for Sunday — both are rising, but Saturday faster. With these three yardsticks, you can compare your hotel’s day-of-week shape on the same basis even as the months change.
Frequently Asked Questions
Q. Which day of the week had the lowest occupancy at Kyoto business hotels in September 2026?
A. Sunday. Estimated (based on OTA-listed inventory) day-of-week averages put Sunday at 82.1% over all 30 days and 76.1% excluding the five-day holiday of September 19–23. Excluding the holiday, Saturday was 87.6%, for a Saturday–Sunday gap of 11.5pt.
Q. How does the day-of-week shape change between averages that include and exclude the holiday?
A. Over all 30 days, the Saturday–Sunday gap is 7.5pt; excluding the five-day holiday it widens to 11.5pt. Because the holiday Sunday (September 20, 100.0%) and Monday (September 21, 99.9%) drop out, Sunday falls 6.0pt and Monday 4.4pt. Thursday and Friday are unchanged.
Q. Do city hotels show the same tendency?
A. Yes. Kyoto Prefecture city hotels (N=34–37 properties) were at Saturday 89.7% and Sunday 85.0% over all 30 days, and Saturday 88.1% and Sunday 80.1% excluding the holiday, so the Saturday–Sunday gap widened from 4.7pt to 8.0pt. The size of the drop is smaller than for business hotels.
Q. When do November Saturdays and Sundays start to diverge?
A. The gap is already there at 45 days before the stay date. Saturday, November 7 was at 77.5% at 45 days out and 85.2% at 30 days out, and Sunday the 8th at 73.3% and 80.2%, so the Saturday–Sunday gap was 4.2pt at 45 days out and 5.0pt at 30 days out (estimates as observed October 11, 2026).
Q. Can the last day of a holiday be treated the same way as a Sunday?
A. It is better to treat them separately. In September’s five-day holiday, the middle day (the 20th) reached 100.0% while the last day (the 23rd) was 79.2%, and November 23 (Monday, holiday) is also only at 77.9% as of 43 days out. This reflects its character as a travel-home day, a different driver from the weekend day-of-week shape.
About the Data in This Article
・Estimated OCC (based on OTA-listed inventory): OTA-listed-inventory occupancy = 100 − 100 × OTA-listed remaining rooms ÷ total rooms. The scope is a fixed cohort of properties that list at least 30% of their total rooms on OTAs (the same set of properties for each stay date; the N= in the body is that number of properties). It is an estimate based on how OTA-sold inventory is absorbed and is defined differently from actual room occupancy (it reads higher, because rooms not listed are counted on the sold side). Months covered: September 2026 (elapsed month, daily actuals) and stay dates from October 24 to November 23, 2026 (booking progress).
・Booking curve: based on observations from 45 days before the stay date up to the latest (observed October 11, 2026). Fixed points are 45 days out, 30 days out and the latest observation.
・Estimated transacted ADR: the transacted price level (tax-exclusive equivalent) estimated from OTA and other sales data (lowest-plan level × category-specific factor, ensembled across multiple channels). Past months are final values; current and future months are estimates based on current sales. Checked against published operating results, the median error is 6.6%. This article covers it monthly only and does not cover day-of-week or daily prices.
・Scope: Kyoto Prefecture business hotels (September daily actuals N=189–201 properties, 19,544–20,010 rooms, a fixed cohort per stay date; booking progress N=192–196 properties, 19,038–19,265 rooms; estimated transacted ADR N=314–327 properties). City hotels, shown for reference, are N=34–37 properties, 4,987–5,084 rooms. Day-of-week averages are simple averages of each weekday’s daily values; the holiday exclusion is computed over the 25 days excluding the five days from Saturday, September 19 to Wednesday, September 23. Individual properties and chain names are not covered.
・Data as of: October 12, 2026. Sales status and inventory change daily, so the figures in this article are a snapshot at the time of retrieval.
・Source: Compiled by the HotelBank Editorial Team from MetroEngines Research.
References and Sources
■ Data sources
Sales inventory and price data from major booking sites collected by MetroEngines Research, aggregated by the HotelBank Editorial Team. Estimated OCC covers Kyoto Prefecture business hotels (September 2026 daily actuals N=189–201 properties, 19,544–20,010 rooms; booking progress for October 24–November 23 N=192–196 properties) and Kyoto Prefecture city hotels (September 2026, N=34–37 properties); estimated transacted ADR covers Kyoto Prefecture business hotels, N=314–327 properties (varies by month). Data as of October 12, 2026 (booking progress observed October 11).
■ Calculation assumptions
Day-of-week averages are simple averages of daily estimated OCC by stay date (4–5 days per weekday over all 30 days; 3–4 days excluding the holiday). The holiday exclusion is computed over the 25 days excluding September 19–23, 2026. Booking progress uses only observations from 45 days before the stay date onward, with fixed points at 45 days out, 30 days out and the latest observation. Year-over-year changes are calculated between finalized months of estimated transacted ADR.
■ Limitations and caveats
Estimated OCC is an estimate based on how OTA-listed inventory is absorbed and is defined differently from actual room occupancy (it reads higher, because rooms not listed are counted on the sold side). The non-holiday Saturday, Sunday and Monday averages are each based on three days and are sensitive to individual events and weather. Estimated OCC and estimated transacted ADR cover different sets of properties, and progress for stay dates not yet reached and November’s estimated transacted ADR may change. The figures do not represent the results of any individual property.