

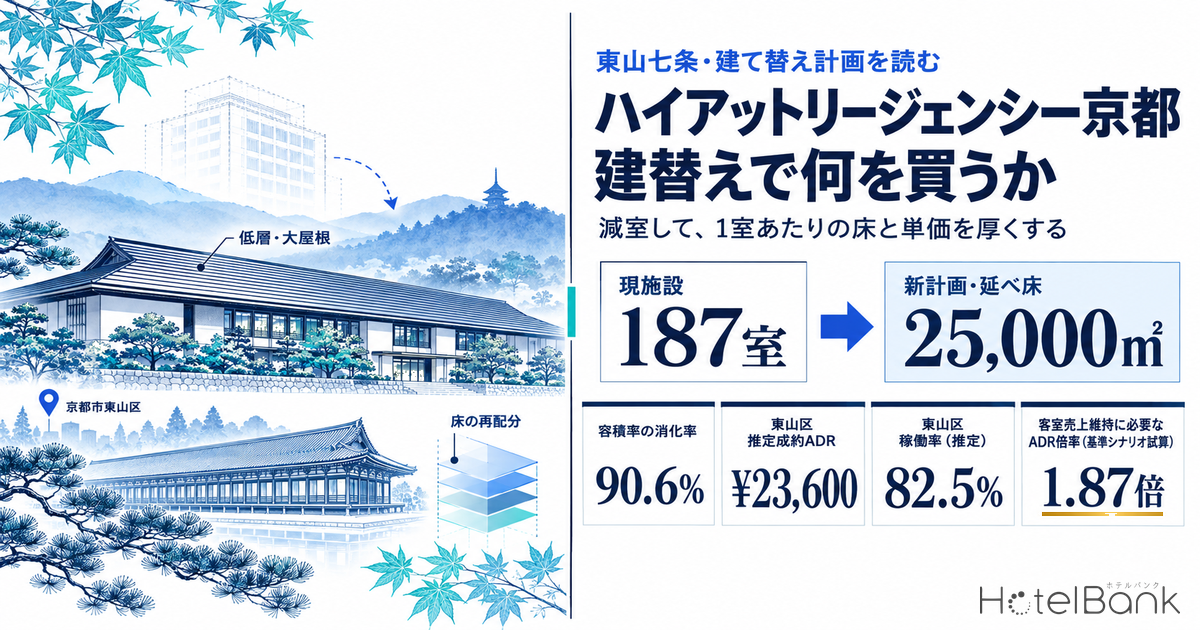
Hyatt Regency Kyoto (ハイアット リージェンシー 京都, 187 rooms), operated by ORIX Real Estate (オリックス不動産) in Kyoto’s Higashiyama Ward, will close on Sunday, May 9, 2027, and will be demolished and rebuilt as the “Higashiyama Shichijo Hotel (tentative name).” The plan presented as a pre-consultation item to the Landscape Subcommittee of the Kyoto City Aesthetic and Scenic Council on Wednesday, June 17, 2026 is a low-rise, large-roof scheme: two basement floors, four floors above ground and a one-level penthouse on a 13,790 m² site, with a gross floor area (GFA) of 25,000 m², clad in a horizontally seamed metal roof and plaster exterior inspired by the Shishinden hall of the Kyoto Imperial Palace. Switching a 46-year-old urban hotel from renovation to a full rebuild, and holding it to four floors rather than going taller, amounts to a choice to reduce the room count while thickening both the floor area and the rate per room. This article re-divides the known figures for the existing hotel (27,359 m² GFA, 187 rooms) and the 25,000 m² of the new plan on a per-room basis, and overlays Higashiyama Ward’s estimated settled ADR (trailing 12-month average of about ¥23,600, N=43–51 properties) and occupancy, the price-tier distribution of 133 properties within a 1.5 km radius, and the site’s zoning as a Category 2 Residential Zone (FAR 200%) to quantify what the owner is buying by cutting rooms.
Metric Definitions Used in This Article
- ADR (average daily rate): An estimated settled rate (tax-exclusive equivalent) calculated by applying a segment-specific adjustment factor to the lowest-plan level each property publishes on OTAs and similar channels (per room, two guests per room, tax inclusive). When checked against property-level results disclosed by listed hotel REITs (91 properties, most recent three months), the median error is about 7%. It is an estimate and differs from each property’s actual settled rates and accounting figures. Area-level ADR is the median of the properties covered (the level of a typical property in the area). Because estimated settled ADR is calculated only for the validated categories of business, city, resort, ryokan and capsule hotels, individual luxury and deluxe properties are shown as “listed rate (all-plan average, tax inclusive)” and are not referred to as ADR.
- OCC (occupancy): The share of rooms sold out of total rooms in an area (an estimate based on OTA sales inventory). It is an estimate based on how inventory sold on OTAs is being consumed and differs from a property’s actual whole-hotel occupancy. In this article it is written as “occupancy (OTA-listed inventory basis, estimated)” with the number of properties and rooms covered.
- Listed rate: The per-room rate for two guests in one room (tax inclusive), averaged across all plans from room-only to plans with meals.
- Data source: MetroEngines Research & Consulting (analysis universe of about 27,000 properties and about 1.26 million rooms in Japan whose operation can be confirmed on OTAs).
- — GFA down 8.6%, floors from five to four: the existing 187-room, 27,359 m² hotel will be rebuilt as a low-rise scheme with a 13,790 m² site and 25,000 m² of GFA. Room count and brand are undisclosed.
- — Higashiyama Ward’s estimated settled ADR is ¥23,600 (Sep 2025–Aug 2026 average, N=43–51 properties), about 1.5 times Shimogyo Ward’s, but −0.5% YoY, with three straight months below the prior year in summer.
- — The plan uses 90.6% of the 200% FAR while staying within the scenic district’s 12–15 m height limit and 40% building coverage ratio, so design freedom concentrates on “floor area per room.”
- — At 100 rooms: 250 m² per room and a required ADR multiple of 1.87x. Under a tax-exclusive ADR of ¥130,000, GOP is estimated at ¥1.81 billion a year, or 6.3–7.3% of construction cost of ¥25.0–28.9 billion (excluding land).
- — Only three properties within 1.5 km combine “100+ rooms” with “a listed rate of ¥100,000 or more.” The two white spaces are large-scale luxury and mid-scale ultra-luxury.
The Facts of the Plan — GFA Down 8.6%, Low-Rise, Room Count Still Undisclosed
We start with the facts that can be confirmed in primary sources. According to the Nikkei (April 2026), ORIX Real Estate also considered renovating and refurbishing the 46-year-old building because of its age, but concluded that a full rebuild was the more rational choice over the long term because large-scale work including seismic reinforcement would be required. Operations end on May 9, 2027, demolition proceeds from fiscal 2027 onward, and the new hotel’s brand, room count and opening date are undecided at this point. Materials from the Kyoto City Aesthetic and Scenic Council reported by the Kensetsu Tsushin Shimbun (June 26, 2026) show the location as 644-2 Sanjusangendo-mawari, Higashiyama Ward, plus the adjoining lot to the west at 644-7; a 13,790 m² site; a reinforced concrete and partly steel structure with two basement floors, four floors above ground and a one-level penthouse; 25,000 m² of GFA; and Nikken Sekkei (日建設計) as designer. The adjoining western lot is the former site of the Japanese Red Cross Society’s Kyoto Chapter, land the company had acquired earlier.
What deserves attention is that gross floor area does not increase but shrinks slightly. The existing building, completed in 1980 with two basement floors and five floors above ground, has a GFA of 27,358.96 m² (per a building database) and holds 187 rooms. The new plan enlarges the site yet has 25,000 m² of GFA, about 8.6% smaller than the existing hotel. In other words, the site expands, the building goes from five floors to four, and GFA stays roughly the same: this reads as a rebuild that changes not the total quantity of floor area but how the floor area is used.
| Item | Existing hotel | New plan (Higashiyama Shichijo Hotel, tentative) | Source |
|---|---|---|---|
| Location | 644-2 Sanjusangendo-mawari, Higashiyama Ward | 644-2 + adjoining western lot 644-7 | Kensetsu Tsushin Shimbun |
| Site area | — (644-2 only) | 13,790 m² | Kensetsu Tsushin Shimbun |
| Floors | B2 + 5 above ground | B2 + 4 above ground + 1-level penthouse | Wikipedia / Kensetsu Tsushin Shimbun |
| Gross floor area | 27,358.96 m² | 25,000 m² (about −8.6%) | bb-building.net / Kensetsu Tsushin Shimbun |
| Rooms | 187 | Undisclosed | Hyatt Japan press materials, April 2026 / Nikkei |
| GFA per room | 146 m² | Depends on room count (see scenarios below) | MetroEngines calculation |
| Completion / opening | Completed 1980; opened as a Hyatt in March 2006 | Demolition from FY2027; opening date undecided | Hyatt Japan press materials / Nikkei |
| Designer | — | Nikken Sekkei | Kensetsu Tsushin Shimbun |
| Exterior | — | Horizontally seamed metal roof inspired by the Shishinden; plaster exterior | Kensetsu Tsushin Shimbun |
The existing hotel has been a well-supported flagship in Higashiyama for the 20 years since it opened as a Hyatt in 2006. Across a cumulative 12,260 guest reviews compiled by the HotelBank Editorial Team, it holds high scores of 4.5 out of 5.0 overall, 4.73 for cleanliness and 4.56 for service, and 28.5% of reviews are written in foreign languages (113 of the most recent 397), reflecting an international customer base. The rebuild is a decision driven by the age of the building, not by how the hotel is rated operationally, and that customer base, together with a location next to Sanjusangendo and the Kyoto National Museum, is the largest asset the next plan inherits.
Market Trends — Higashiyama’s Estimated Settled ADR Is ¥24,000, 40–50% Above Shimogyo and Nakagyo, but Below Last Year in Summer
Next we check the price level of Higashiyama Ward, where the new hotel will stand. On MetroEngines Research & Consulting’s estimated settled ADR (median of validated categories), Higashiyama Ward averaged ¥23,600 over the 12 months from September 2025 to August 2026 (N=43–51 properties), about 1.5 times Shimogyo Ward, which contains Kyoto Station (¥15,600, N=157–168), and about 1.4 times Nakagyo Ward (¥16,900, N=102–112). It is also more than 40% above the ¥16,500 for Kyoto Prefecture as a whole, making Higashiyama one of the highest-rate wards in the city.
The direction of travel calls for caution, however. The 12-month average is flat for Higashiyama Ward at −0.5% YoY; growth has stalled while Shimogyo Ward (+5.5%) and Kyoto Prefecture as a whole (+3.3%) rose. Month by month, October 2025 (+12.3%) and December (+10.4%) exceeded the prior year, but June 2026 (−12.8%), July (−9.9%) and August (−8.9%) made three consecutive summer months below the prior year. City hotels across Kyoto Prefecture are also at −2.0% on a 12-month average, pointing to a structure in which higher-rate tiers find it harder to absorb thin summer demand. The autumn-foliage season is a different story: the estimated settled ADR for November 2026, an estimate based on rates listed at the time of the survey, is ¥37,200, meaning rooms are on sale 18% above the November 2025 actual (¥31,500).
| Area | Estimated settled ADR (Sep 2025–Aug 2026 average) | Prior-year period (Sep 2024–Aug 2025) | YoY | Properties covered (monthly N) |
|---|---|---|---|---|
| Higashiyama Ward | ¥23,637 | ¥23,750 | -0.5% | 43–51 |
| Shimogyo Ward | ¥15,606 | ¥14,790 | +5.5% | 157–168 |
| Nakagyo Ward | ¥16,943 | ¥16,642 | +1.8% | 102–112 |
| Kyoto Prefecture (all) | ¥16,469 | ¥15,938 | +3.3% | 576–607 |
| Kyoto Prefecture (city hotels) | ¥23,722 | ¥24,194 | -2.0% | 56–59 |
We also look at occupancy (OTA-listed inventory basis, estimated). For the 86–88 properties and roughly 2,750 rooms covered in Higashiyama Ward (as listed on major booking sites), occupancy was 75.1% in August 2026 and 82.5% in September. Compared with 80.7% in August and 84.0% in September for Kyoto Prefecture as a whole (575 properties, 31,489 rooms), Higashiyama Ward is several points lower; in the same August, the deluxe tier (18 properties and 1,549 rooms in Kyoto Prefecture) was at 75.8% and the luxury tier with listed rates of ¥100,000 or more (22 properties, 665 rooms) at 83.2%. The existence of a group of properties that sustain 80% occupancy even in the high-rate tier is demand-side support for a strategy of cutting rooms and raising rates.
| Month | Properties covered | Rooms covered | Higashiyama Ward occupancy (OTA-listed inventory basis, estimated) | Kyoto Prefecture overall (same basis) |
|---|---|---|---|---|
| June 2026 | 79 | 2,636 | 80.6% | — |
| July 2026 | 82 | 2,691 | 77.3% | — |
| August 2026 | 88 | 2,777 | 75.1% | 80.7% (575 properties, 31,489 rooms) |
| September 2026 | 86 | 2,749 | 82.5% | 84.0% (566 properties, 31,989 rooms) |
A regulatory factor also shapes the pricing environment. From March 1, 2026, Kyoto City moved its accommodation tax to five tiers and charges ¥10,000 on stays of ¥100,000 or more per person per night. Because the absolute amount of tax grows with the rate, the gap between the displayed price and the hotel’s net take widens in the luxury tier. This is a given to be built into rate design, and the scenarios below are standardized on tax-exclusive ADR.
Site Assessment — Category 2 Residential, FAR 200%: Scenic-District Low-Rise Rules Set the “Four Floors”
Next we look at why the building is four floors, from the regulatory side. Querying the Sanjusangendo-mawari site in the zoning data of the Ministry of Land, Infrastructure, Transport and Tourism’s (MLIT) Real Estate Information Library returns Category 2 Residential Zone, FAR 200%, building coverage ratio 60%. Applying the 200% FAR to the 13,790 m² site gives a cap of 27,580 m², and the planned 25,000 m² of GFA uses 90.6% of it. Meanwhile, Kyoto City’s scenic district ordinance sets a height limit of 12 m for Type 4 areas and 15 m for Type 5 areas of the Higashiyama Scenic District, both with a building coverage ratio of four-tenths and a green-area ratio of two-tenths. With 40% building coverage, the building footprint is capped at about 5,500 m²; stacking close to that footprint on four above-ground floors and fitting the remainder into two basement floors reaches 25,000 m² of GFA. In short, the solution is to use up nearly all of the FAR, keep the height inside the scenic-district envelope, and spend the remaining freedom on a “large-roofed low-rise.” In scenic districts, the building coverage and green-area ratios also push up the land cost per room. According to press reports, the application for scenic-district permission is planned within 2026 and referral to the Aesthetic and Scenic Council for February 2027.
| Zoning | Category 2 Residential Zone |
| FAR / building coverage (city planning) | 200% / 60% |
| FAR cap and planned GFA | 27,580 m² → 25,000 m² (90.6%) |
| Scenic district ordinance (Higashiyama, Type 4 / Type 5) | Height 12 m / 15 m · coverage 40% · green area 20% |
| Landscape procedures | Scenic permit application within 2026; council referral planned for Feb 2027 |
On land prices, Higashiyama Ward’s 2026 official land prices averaged ¥1.72 million/m² for commercial land (+9.4% YoY) and ¥343,000/m² for residential land (+8.3%), with every survey point rising. The highest point, at Gion-Shijo, reached ¥17.52 million per tsubo (+16.5%). The area around Sanjusangendo is zoned residential and does not carry commercial-land price levels, but securing a 13,790 m² site in the central city would be difficult for a newcomer; because this plan rebuilds on land the company already owns and involves no land acquisition cost, its starting point differs from that of a new entrant looking for a site with land cost included.
Competitive Landscape — 133 Properties and 15,000 Rooms Within 1.5 km, Only Three at “100+ Rooms × ¥100,000+”
So how is the surrounding supply structured? Counting properties with 20 or more rooms and price observations in the most recent 12 months within a 1.5 km radius of the site’s center gives 133 properties and 15,379 rooms (within the scope tracked by MetroEngines Research & Consulting). Because this radius reaches as far as the cluster of business hotels at Kyoto Station’s Hachijo exit, 42% of rooms fall in the economy tier (listed rates of ¥15,000–25,000) and 42% in the midscale tier (¥25,000–50,000), while the luxury tier with listed rates of ¥100,000 or more is limited to 7 properties and 742 rooms (a 4.8% share of rooms).
| Price tier (listed rate, all-plan average, tax inclusive, 12-month average) | Properties | Rooms | Share of rooms |
|---|---|---|---|
| Luxury (¥100,000 or more) | 7 | 742 | 4.8% |
| Upper-midscale (¥50,000–100,000) | 12 | 1,320 | 8.6% |
| Midscale (¥25,000–50,000) | 53 | 6,407 | 41.7% |
| Economy (¥15,000–25,000) | 50 | 6,430 | 41.8% |
| Budget (under ¥15,000) | 11 | 480 | 3.1% |
| Total | 133 | 15,379 | 100% |
Isolating the Higashiyama Ward side alone gives 25 properties and 1,802 rooms, with a median listed rate of about ¥37,200, far above the radius as a whole (about ¥27,300). At the top are low-rise, small-scale properties achieving high rates. Four Seasons Hotel Kyoto (フォーシーズンズホテル京都, 123 rooms), Six Senses Kyoto (シックスセンシズ京都, 81 rooms) and The Hotel Seiryu Kyoto Kiyomizu (ザ ホテル青龍 京都清水, 48 rooms) all sit in the ¥200,000–300,000 range on listed rate (all-plan average, tax inclusive), and Seikoro (晴鴨楼, 22 rooms), a ryokan known for its cuisine and founded in the Edo period, is also above ¥100,000. Higashiyama’s high-rate tier is a market opened up not by “large-scale” properties but by properties that “limit scale and raise the density of experience per room.”
| Property (Higashiyama Ward, within 1.5 km) | Rooms | Listed rate (all-plan average, tax inclusive, 12-month average) | Year opened |
|---|---|---|---|
| Four Seasons Hotel Kyoto (フォーシーズンズホテル京都) | 123 | ¥313,300 | 2016 |
| Six Senses Kyoto (シックスセンシズ京都) | 81 | ¥274,593 | 2024 |
| The Hotel Seiryu Kyoto Kiyomizu (ザ ホテル青龍 京都清水) | 48 | ¥216,485 | 2020 |
| Seikoro (晴鴨楼) | 22 | ¥114,478 | 1831 |
| Hyatt Regency Kyoto (ハイアット リージェンシー 京都) | 187 | ¥102,954 | 2006 |
| Hotel The Celestine Kyoto Gion (ホテル ザ セレスティン京都祇園) | 157 | ¥91,350 | 2017 |
| Saka Hotel Kyoto (清水小路 坂のホテル京都) | 38 | ¥73,750 | 2017 |
| Sakura Cross Hotel Kyoto Kiyomizu (サクラクロスホテル京都清水寺) | 41 | ¥54,544 | 2022 |
| Nohga Hotel Kiyomizu Kyoto (ノーガホテル 清水 京都) | 207 | ¥53,396 | 2022 |
The positioning map reveals two white spaces. First, the zone that “combines scale and rate,” with more than 100 rooms and a listed rate of ¥100,000 or more, contains only three properties: Four Seasons Hotel Kyoto, The Thousand Kyoto (ザ・サウザンド京都) and the existing Hyatt Regency Kyoto. Second, “mid-scale ultra-luxury,” with 50–100 rooms at ¥150,000 or more, has just one property, Six Senses Kyoto (81 rooms). A new plan that holds 25,000 m² of GFA while staying low-rise can aim at either of these two white spaces. Choosing the former means 100 or more rooms and the latter fewer than 100, and depending on which is taken, floor area per room swings from 1.7 times to more than 3 times the existing hotel’s.
Crowded The filled zone
¥15,000–¥50,000 × 100–500 rooms
46 properties and 9,856 rooms, centered on business and city hotels around Kyoto Station (103 properties and 12,837 rooms across the whole price band). New entry presupposes differentiation.
WS1 Large-scale luxury
¥100,000 or more × 100+ rooms
Three properties. A zone that can be targeted with a full-service model, with banquet, restaurant and spa facilities, making use of the 25,000 m² of GFA.
WS2 Mid-scale ultra-luxury
¥150,000 or more × 50–100 rooms
One property. A zone differentiated by using 250–350 m² of floor area per room and offering a low-rise, garden and large-roof experience.
The Economics of Fewer Rooms — From 146 m² per Room to 208–357 m², Needing 1.6–2.7x ADR to Hold Room Revenue
This is the heart of the matter. A rebuild that “reduces the room count and keeps the gross floor area” is buying floor area per room. The existing hotel’s GFA per room is 27,359 m² ÷ 187 rooms = 146 m², a whole-building figure that includes banquet halls, restaurants and back-of-house space. Compared with luxury hotel plans under way in Kyoto, the Rosewood hotel plan that Mitsubishi Estate is advancing at Shokokuji Monzen-cho in Kamigyo Ward has 20,553 m² of GFA and 135 rooms, or 152 m² per room, and Imperial Hotel, Kyoto (帝国ホテル 京都; Gion, Yasaka Kaikan), which opened on Thursday, March 5, 2026, has 10,804 m² of GFA and 55 rooms, or 196 m² per room (both figures as notified in building plans). Dividing Higashiyama Shichijo’s 25,000 m² by 120 rooms gives 208 m² per room, by 100 rooms 250 m², and by 70 rooms 357 m², so depending on the room count, 1.4 to 2.4 times the existing hotel’s floor area can be allotted to each room.
The price of thicker floor area is fewer rooms, and keeping room revenue at the current level requires making up the difference through rate. Assuming the same occupancy, the required ADR multiple is simply 187 ÷ the new room count: 1.56x at 120 rooms, 1.87x at 100 rooms and 2.67x at 70 rooms. Given that Higashiyama Ward’s low-rise luxury properties show listed rates (all-plan average, tax inclusive) in the ¥200,000–300,000 range, an assumption of a tax-exclusive ADR of ¥130,000 at around 100 rooms sits inside the market’s prevailing range. The supply-side environment is also a tailwind: Kyoto Prefecture’s floor area of building starts for accommodation use peaked at 352,000 m² in 2018 and shrank to 34,000 m² in 2024 (89 buildings), less than one-tenth of the peak. Rising construction costs are restraining new supply, giving the existing high-rate tier upside from eased competition.
Below, we model three scenarios combining room count and rate. For construction cost, we took the 2025 reinforced-concrete unit cost of ¥2.026 million per tsubo based on MLIT’s Building Starts Statistics as a lower-bound reference, adopted ¥3.3 million, the midpoint of the guideline range for luxury hotels (¥3.1–3.5 million per tsubo), and multiplied it by 25,000 m² of GFA (about 7,562 tsubo) to arrive at about ¥25.0 billion. We also show a second stage that builds in inflation over the construction period: with demolition in fiscal 2027 and the midpoint of construction around 2029, we add roughly three years at 5% a year (×1.158). For the GOP margin, we referred to the actual 38.9% for the 91 MHM-operated properties disclosed by Invincible Investment Corporation (インヴィンシブル投資法人; fiscal period ended December 2024) and, considering that full-service hotels tend to have lower margins than limited-service hotels because they carry food-and-beverage and banquet departments, set it at 26–30%. Because the land is already owned, yield is shown as the ratio of GOP to construction investment excluding land.
| Item | A. 120 rooms (mid-luxury) | B. 100 rooms (luxury) Base | C. 70 rooms (ultra-luxury) |
|---|---|---|---|
| Rooms | 120 | 100 | 70 |
| GFA per room (25,000 m² ÷ rooms) | 208 m² | 250 m² | 357 m² |
| Versus the existing hotel (187 rooms, 146 m²/room) | 1.4x | 1.7x | 2.4x |
| ADR multiple needed to hold room revenue (vs. 187 rooms) | 1.56x | 1.87x | 2.67x |
| Assumed ADR (tax exclusive; model assumption) | ¥90,000 | ¥130,000 | ¥180,000 |
| Assumed occupancy (model assumption) | 75% | 75% | 70% |
| Assumed GOP margin (model assumption) | 26% | 28% | 30% |
| Room revenue (annual) | ¥2.96B | ¥3.56B | ¥3.22B |
| Total revenue (converted at a 55% rooms share) | ¥5.38B | ¥6.47B | ¥5.85B |
| GOP (annual) | ¥1.40B | ¥1.81B | ¥1.76B |
| Construction cost (1): 2025 actual basis (¥3.3M per tsubo × 7,562 tsubo) | ¥25.0B | ¥25.0B | ¥25.0B |
| GOP ÷ construction cost (1) (excluding land) | 5.6% | 7.3% | 7.0% |
| Construction cost (2): with inflation (5% a year for about three years to the midpoint) | ¥28.9B | ¥28.9B | ¥28.9B |
| GOP ÷ construction cost (2) (excluding land) | 4.8% | 6.3% | 6.1% |
The result is that Scenario B (100 rooms, tax-exclusive ADR of ¥130,000, 75% occupancy) yields GOP of ¥1.81 billion a year, 7.3% of construction cost (1) and 6.3% of inflation-adjusted construction cost (2). Scenario C, which takes a rate of ¥180,000 at 70 rooms, has the highest density of experience at 357 m² per room, but with fewer rooms total revenue is harder to grow, at ¥5.85 billion, and its yield falls slightly short of B. Scenario A (120 rooms, ¥90,000) makes occupancy easier to capture, but at 208 m² per room there is relatively less room for differentiation and the yield stays in the 5% range. The answer to “what does cutting rooms buy?” is that thickening floor area to around 250 m² per room, and using that experience to capture a rate inside Higashiyama Ward’s prevailing range, is the combination that balances floor area, rate and yield.
We check sensitivity. In Scenario B, even if ADR comes in 10% lower or occupancy 5 points lower, the yield on construction cost (2) stays in the upper 5% range, and it is 5.3% even if both happen at once. Demand in the luxury tier is sensitive to season and exchange rates, but the fact that Kyoto Prefecture’s luxury tier (listed rates of ¥100,000 or more; 22 properties, 665 rooms) sustained estimated occupancy of 83.2% in August 2026 indicates that this assumption is not excessive.
| Scenario B (100 rooms) | Base case | ADR −10% | Occupancy −5 pt | Both |
|---|---|---|---|---|
| Total revenue | ¥6.47B | ¥5.82B | ¥6.04B | ¥5.44B |
| GOP | ¥1.81B | ¥1.63B | ¥1.69B | ¥1.52B |
| GOP ÷ construction cost (1) (¥24.96B) | 7.3% | 6.5% | 6.8% | 6.1% |
| GOP ÷ construction cost (2) (¥28.90B) | 6.3% | 5.6% | 5.9% | 5.3% |
Implications for Owners and Asset Managers — When “Rebuild” Becomes an Option for Urban Hotels Over 40 Years Old
Generalizing from this case, the conditions under which a rebuild beats a renovation can be organized into three. First, the remaining FAR and the direction of regulation line up. Higashiyama Shichijo uses 90% of its 200% FAR while keeping its height within the scenic-district envelope, and so did not have to give up GFA even as a low-rise. In Kyoto, where height limits are strict, the idea of widening the site and building outward works precisely because building upward is not possible. Second, the location’s rate potential is not being fully captured by the current room configuration. Higashiyama Ward’s estimated settled ADR of ¥24,000 is among the highest in the city, yet low-rise, small-scale properties achieve listed rates in the ¥200,000–300,000 range. When a price tier that the existing room format cannot reach exists in the same ward, investment in thicker floor area converts readily into rate. Third, structural issues that are hard to solve by renovation (seismic reinforcement, building-systems renewal, specified ceilings and so on) pile up, and the long closure required for renovation work comes close to the opportunity cost of a rebuild. According to the Nikkei’s reporting, this is also the background to the company’s judgment that a full rebuild is more advantageous over the long term. Where the dividing line between renovation and rebuilding lies for the pre-1981 seismic-code stock as a whole is explored in Japan’s Pre-1981 Hotel Stock: 236k Rooms, 19.1% — Retrofit or Rebuild.
| Dimension | Large-scale renovation | Rebuild (this type of case) |
|---|---|---|
| Rooms | Fine-tuning within the constraints of the existing structure | Free redesign (fewer, larger rooms are possible) |
| Floor area per room | Limited to partition changes (does not move far from the existing 146 m²/room) | Can be set up to 208–357 m²/room |
| Structure and building systems | Seismic reinforcement and systems renewal carried out within the existing structure | Integrated design to current standards |
| Construction period and closure | Phased work with partial closure is possible | Full closure for multiple years from demolition to opening |
| Regulatory compliance | May be able to continue as an existing non-conforming building | New compliance with scenic, landscape and height-control districts (council procedures) |
| Reachable rate tier | Current tier plus a little | Repositioning into the market’s upper tier |
| Investment scale (guide) | Hundreds of thousands of yen per m² of GFA | ¥25–29 billion in this estimate (excluding land) |
The implication for investors considering Kyoto’s high-rate tier is that new entry on the supply side is structurally constrained. Kyoto Prefecture’s floor area of building starts for accommodation use was 34,000 m² in 2024, less than one-tenth of the peak, and because scenic and height-control district regulations do not permit high-rise development, sites that can secure GFA are scarce in themselves. With Imperial Hotel, Kyoto (55 rooms), the Rosewood (135 rooms, planned) and Higashiyama Shichijo (room count undisclosed), Kyoto’s high-rate projects opening or planned from 2026 onward are mostly plans with limited room counts, and the market has entered a phase of growing through “thick floor area and high rates” rather than “a large number of rooms.”
Conclusion — A 25,000 m² Rebuild Is a “Reallocation of Floor Area,” and the Rate Multiple Decides Whether It Pays
The rebuild of Hyatt Regency Kyoto is a plan that leaves GFA almost unchanged (27,359 m² → 25,000 m²), holds the building to four floors instead of five, and widens the site to 13,790 m². Having used 90.6% of the 200% FAR while fitting within the scenic district’s height and building coverage limits, the remaining design freedom concentrates on “floor area per room.” As long as the room count is undisclosed, the figures in this article remain scenarios, but at around 100 rooms the plan can secure 250 m² per room, 1.7 times the existing hotel’s floor area; the ADR multiple needed to hold room revenue is 1.87x; and the required tax-exclusive ADR falls inside the listed-rate level of Higashiyama Ward’s luxury tier. The GOP yield on construction cost of ¥25–29 billion is in the 6–7% range and stays in the 5% range under sensitivity testing.
For readers who are owners and asset managers, the checklist is clear: (1) measure the GFA obtainable under the site’s FAR, height and building coverage limits; (2) measure the gap between the listed rates achieved by the upper tier in the same area and your own property’s estimated settled ADR; (3) work backward to the floor area per room and the room count needed to close that gap; and (4) verify whether the ADR multiple needed to hold room revenue (current rooms ÷ new rooms) fits within the market range. Higashiyama Shichijo is a case in which all four steps line up, and once the room count and brand are announced, it will be worth checking which of this article’s scenarios it most closely resembles.
⚠ Note on ADR for future dates: The estimated settled ADR shown in this article for months from September 2026 onward is an estimate based on selling prices published on OTAs and similar channels at the time of the survey (a forward estimate), and it changes as check-in dates approach, through the addition of new plans and price adjustments. Please note that prices currently set high may fall close to the date. In addition, the development scenarios in this article are simplified estimates based on published materials and MetroEngines estimates; actual investment decisions require a detailed feasibility study.
Frequently Asked Questions
Q. Until when will Hyatt Regency Kyoto operate?
A. The operator, ORIX Real Estate, has announced that operations will end on Sunday, May 9, 2027. Demolition work is then expected to proceed from fiscal 2027 onward (Nikkei, April 2026; Kensetsu Tsushin Shimbun, June 26, 2026).
Q. Have the new hotel’s room count and brand been decided?
A. As of October 2026, the room count, brand and opening date are all undisclosed. What has been made public is an outline of the building plan: a 13,790 m² site, two basement floors, four floors above ground and a one-level penthouse, 25,000 m² of GFA, and Nikken Sekkei as designer. The room counts in this article are scenarios for estimation purposes, not the developer’s planned figures.
Q. How high are hotel rates in Higashiyama Ward?
A. On MetroEngines Research & Consulting’s estimated settled ADR (median of validated categories, tax-exclusive equivalent), the 12-month average for September 2025 to August 2026 is about ¥23,600. That exceeds about ¥15,600 for Shimogyo Ward and about ¥16,500 for Kyoto Prefecture as a whole. Low-rise, small-scale luxury properties sit in the ¥200,000–300,000 range on listed rate (all-plan average, tax inclusive).
References and Sources
■ Data sources
MetroEngines Research & Consulting’s estimated settled ADR (Higashiyama Ward, Shimogyo Ward, Nakagyo Ward and Kyoto Prefecture; monthly, September 2024–August 2026), occupancy (OTA-listed inventory basis, estimated; June–September 2026), and listed-rate tabulation for 133 properties within a 1.5 km radius (Sep 2025–Aug 2026 average). The plan outline is from published materials of the Kensetsu Tsushin Shimbun and the Kyoto City Aesthetic and Scenic Council, zoning from the MLIT Real Estate Information Library, and building starts for accommodation use from e-Stat’s “Building Starts Statistics.”
■ Model assumptions
Because the developer has not disclosed the room count, we set three scenarios of 120, 100 and 70 rooms, with tax-exclusive ADR of ¥90,000, ¥130,000 and ¥180,000, assumed occupancy of 75%, 75% and 70%, a 55% rooms share of revenue, and a GOP margin of 26–30%. Construction cost is shown in two stages: ¥3.3 million per tsubo × about 7,562 tsubo (about ¥25.0 billion), and about ¥28.9 billion after building in inflation of 5% a year for about three years to the midpoint of construction. Because the land is already owned, it is excluded from the denominator of the yield.
■ Limitations and caveats
The room count, brand and opening date are undisclosed, and the figures in this article are MetroEngines’ simplified estimates, not the developer’s planned figures. Estimated settled ADR and occupancy are estimates and differ from each property’s actual results; individual luxury and deluxe properties are shown at listed rate (all-plan average, tax inclusive). ADR from September 2026 onward is an estimate based on rates listed at the time of the survey. Demolition cost, pre-opening expenses, FF&E, interest and taxes are not included in the estimates.
■ Market data
- MetroEngines Research & Consulting — Estimated settled ADR (Higashiyama Ward N=43–51 properties, Shimogyo Ward N=157–168, Nakagyo Ward N=102–112, Kyoto Prefecture N=576–607); occupancy (OTA-listed inventory basis, estimated; Higashiyama Ward 79–88 properties, Kyoto Prefecture 566–575 properties); tabulation of properties and listed rates within a 1.5 km radius (N=133 properties); guest review tabulation (Hyatt Regency Kyoto, cumulative 12,260 reviews)
■ Government statistics and public data
- MLIT Real Estate Information Library — Zoning (Category 2 Residential Zone, FAR 200%, building coverage ratio 60%)
- e-Stat, “Building Starts Statistics” (statistics ID: 0003114490; Kyoto Prefecture, accommodation use, 2014–2024)
- MLIT, “Survey on Building Dynamics” (figures notified in building plans: Higashiyama Shichijo Hotel, GFA 25,000 m², 4 floors; Shokokuji Monzen-cho plan, 135 rooms, GFA 20,553.6 m²; Gion-machi Minamigawa plan, 55 rooms, GFA 10,804.2 m²)
- Kyoto City, “Results of the 3rd FY2026 Meeting of the Landscape Subcommittee of the Kyoto City Aesthetic and Scenic Council” (held June 17, 2026; agenda item (3), pre-consultation on the “Kyoto Higashiyama Shichijo Hotel (tentative) Rebuilding Plan”)
- Kyoto City, City Planning Bureau, “Guide to Permit Applications for Alterations within Scenic Districts” (Higashiyama Scenic District: Type 4, 12 m / Type 5, 15 m; building coverage ratio four-tenths; green-area ratio two-tenths)
- 2026 Official Land Prices, Higashiyama Ward, Kyoto (commercial land average ¥1.72 million/m², +9.4% YoY; residential land average ¥343,000/m², +8.3%)
- Kyoto City, “Kyoto City Will Revise Its Accommodation Tax in March 2026” (¥10,000 for stays of ¥100,000 or more per person per night)
■ Company materials and industry reports
- Hyatt Japan K.K., “Press Materials, April 2026” (Hyatt Regency Kyoto: opened March 2006, 187 rooms)
- Hilton, “Company Overview” (updated August 25, 2026) (DoubleTree by Hilton Kyoto Higashiyama: 158 rooms, opened after rebranding in 2023)
- Invincible Investment Corporation — GOP results for MHM-operated hotels (91 properties, 38.9%, fiscal period ended December 2024)
- archi-book 2025 edition — Construction cost per tsubo by structure (reinforced concrete ¥2.026 million, steel ¥2.405 million)
- Relo Hotel Solutions — Guideline GOP margins by hotel type
- JLL, “Japan Hotel Investment Market 2025”
■ News and press releases
- Kensetsu Tsushin Shimbun, “[ORIX Real Estate] Higashiyama Shichijo Hotel Inspired by the Shishinden” (June 26, 2026)
- Nikkei, “Hyatt Regency Kyoto to End Operations in May 2027 Due to Aging” (April 2026)
- Kensetsu News, “Hyatt Regency Kyoto to End Operations in May 2027 / ORIX Real Estate”
- “[Follow-up] Kyoto Higashiyama Shichijo Hotel Rebuilding Plan Takes Shape” (planned timing of the scenic permit application and council referral)
- “ORIX Real Estate to Turn the Japanese Red Cross Society Kyoto Chapter Site at Higashiyama Shichijo into a Hotel” (background on the adjoining western lot)
- Wikipedia, “Hyatt Regency Kyoto” (Japanese edition; B2 + 5 floors above ground, rebuilt in 1980) / bb-building.net (gross floor area 27,358.96 m²)
- HOTERES, “Imperial Hotel Opens ‘Imperial Hotel, Kyoto’ on March 5, Its Fourth Property and First New Opening in 30 Years” (55 rooms)
- Kyoto Shimbun, “Luxury Hotel Development Planned on Land Next to Shokokuji Temple, Kyoto” (Mitsubishi Estate, Rosewood, 135 rooms)
Source: Hyatt Japan K.K., “Press Materials, April 2026”
Source: Hilton, “Company Overview” (updated August 25, 2026)