

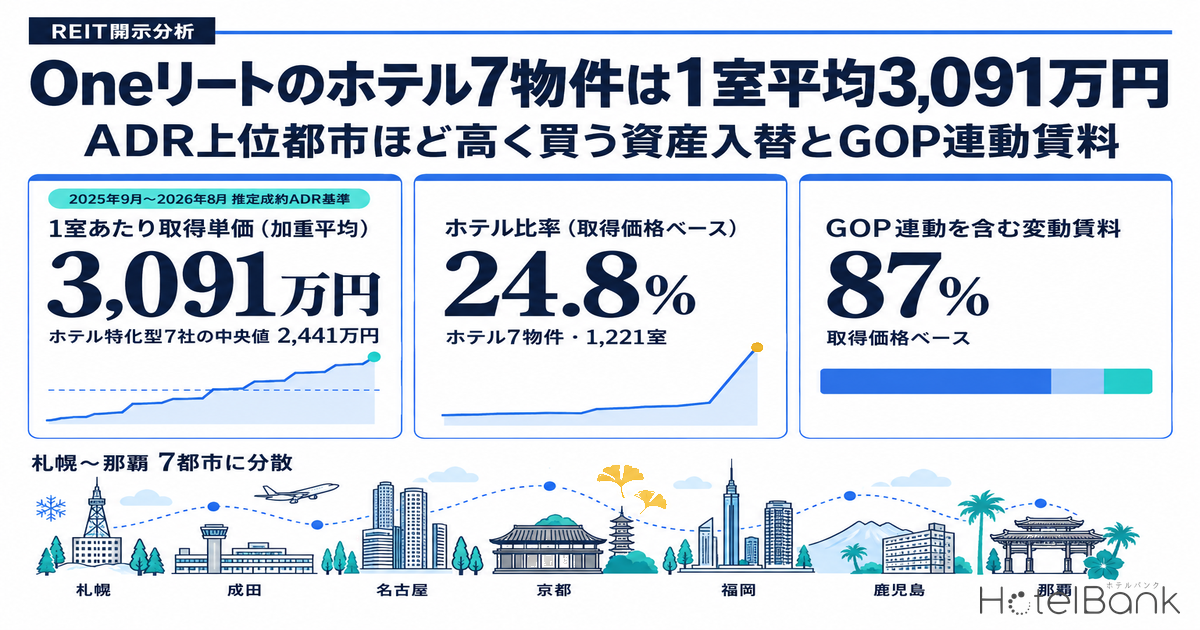
One REIT, Inc. (Oneリート投資法人, TSE: 3290) made its first hotel investment in March 2025, when it acquired Comfort Inn Nagoya Sakae Ekimae (コンフォートイン名古屋栄駅前). It added Candeo Hotels Kyoto Karasuma Rokkaku (カンデオホテルズ京都烏丸六角) in December 2025 and five more hotels, including DoubleTree by Hilton Naha Shuri Castle (ダブルツリーbyヒルトン那覇首里城), in March 2026. In a little over a year, a portfolio built around small and mid-sized office buildings came to hold seven hotels with 1,221 rooms. This article organizes the officially disclosed acquisition prices, room counts and rent structures property by property, and compares the acquisition price per room with the 300 properties held by seven hotel-focused investment corporations. It also sets those per-room prices against the estimated settled ADR of each host municipality to read what price was paid, and which demand the asset reshuffle was aiming for.
Metric Definitions Used in This Article
- ADR (average daily rate): An estimated settled rate (tax-exclusive equivalent) calculated by applying a segment-specific adjustment factor to the lowest plan level each property publishes on OTAs (two guests per room, price per room, tax-inclusive). Checked against property-level results disclosed by listed hotel REITs (91 properties, most recent three months), the median error is about 7%. This is an estimate and differs from each property’s actual settled prices and accounting figures. Area-level ADR is the median across the covered properties (the level of a typical property in the area); in this article it is the simple average of the monthly values for the 12 months from September 2025 to August 2026.
- Acquisition price per room: The acquisition price disclosed by the investment corporation (¥ million) divided by the number of rooms. Because a price that includes all land, buildings and ancillary facilities (banquet halls, restaurants and so on) is divided by the room count, the figure tends to come out higher for full-service hotels.
- Appraisal NOI yield: Net operating income under the direct capitalization method stated in the real estate appraisal report at acquisition, divided by the acquisition price (disclosed by One REIT).
- Data source: MetroEngines Research & Consulting / official disclosures of One REIT, Inc.
- — About ¥30.91 million per room: the weighted average of the seven hotels (acquisition price ¥37,736 million, 1,221 rooms). That is about 27% above the median of the 300 domestic properties held by seven hotel-focused investment corporations (about ¥24.41 million).
- — A 2.9x spread in per-room prices: from about ¥52.30 million at Fukuoka Hakata to about ¥17.98 million at Kagoshima Tenmonkan. The correlation coefficient with the estimated settled ADR of the host municipality (average of September 2025 to August 2026) is 0.91 (a reference value from seven data points).
- — ADR multiples of 6.4x to 10.0x: the per-room price divided by annual room revenue at the area ADR (100% year-round occupancy) falls in a narrow range, which reads as acquisitions priced in line with local rate levels.
- — About 87% of the acquisition price is on variable rent that includes a GOP-linked component: only one property, Candeo Hotels Kyoto Karasuma Rokkaku (12.7%), is on fixed rent.
- — Hotel share reached 24.8% in one year: five hotels were acquired together on March 19, 2026. Naha Shuri Castle will receive about ¥1.2 billion of investment and is scheduled to reopen in May 2027, rebranded as a Hewitt Resort.
Conclusion — Higher Prices in Deeper Markets, Six Properties on Variable Rent
The main points first. The seven One REIT hotels have a combined acquisition price of ¥37,736 million and 1,221 rooms on a disclosed basis. The acquisition price per room is about ¥30.91 million on a weighted-average basis, and the median across the properties is about ¥32.25 million. Compared with the median of the 300 domestic properties held by the seven listed hotel-focused investment corporations (about ¥24.41 million), that is about 27% higher on a weighted-average basis and about 32% higher on a median basis.
The spread, however, is wide. The highest, Quintessa Hotel Fukuoka Hakata Relax & Sleep (クインテッサホテル福岡博多 Relax&Sleep), is about ¥52.30 million per room, and the lowest, Quintessa Hotel Kagoshima Tenmonkan Relax & Sleep (クインテッサホテル鹿児島天文館 Relax&Sleep), is about ¥17.98 million, a 2.9x gap. The difference tracks local hotel rate levels closely: the higher the estimated settled ADR (12-month average) of the host municipality, the higher the acquisition price per room. Although it is only a reference value from seven data points, the correlation coefficient between the two reaches 0.91.
The other defining feature is the rent structure. Of the seven properties, five are on variable rent linked to GOP (gross operating profit), The Edistar Hotel Narita (ザ エディスターホテル成田) combines GOP-linked and fixed rent, and only Candeo Hotels Kyoto Karasuma Rokkaku is on fixed rent. On an acquisition-price basis, about 87% is under contracts in which the hotel’s operating performance feeds into rent. Rising room rates flow straight into the funds available for distributions, while rental income becomes more exposed to swings in the lodging market. Paired with the stable rent of office buildings, the two asset types offset each other’s characteristics.
How the Asset Reshuffle Unfolded — Hotel Share From 0% to 24.8% in One Year
One REIT’s hotel investment proceeded in stages. In its March 7, 2025 release on the acquisition of Comfort Inn Nagoya Sakae Ekimae, it positioned hotels as assets with “cash flow growth potential” and “inflation resilience,” and set out a policy of raising portfolio quality by replacing aging office buildings. The property is a limited-service hotel with 240 rooms, completed in 2014, a one-minute walk from Sakae Station on the Nagoya Municipal Subway, and is operated by Greens.
In December 2025, it sold an office building in Kyoto that was about 40 years old (ONEST Kyoto Karasuma Square) in four installments for a total of ¥5.0 billion, while acquiring Candeo Hotels Kyoto Karasuma Rokkaku, completed in March 2021, for ¥4.8 billion. This property is on fixed rent under a fixed-term building lease and provides the stable portion of earnings within a hotel group that is mostly on variable rent.
The turning point came in March 2026. One REIT carried out its first public offering in about four and a half years and acquired five hotels and one office building (Kagurazaka Plaza Building, now ONEST Iidabashi Square) for a combined acquisition price of ¥29.9 billion. According to its financial results presentation, the average appraisal NOI yield of the six properties is 6.16%. As a result, the hotel share on an acquisition-price basis rose from 6.3% at the end of the fiscal period ended August 2025 and 10.2% at the end of the fiscal period ended February 2026 to 24.8% after the March 19, 2026 acquisition. Asset size reached ¥152.1 billion, of which hotels account for ¥37.7 billion.
| Acquisition date | Property | Acquisition price (¥ million) | Rooms | Rent structure | Notes |
|---|---|---|---|---|---|
| March 21, 2025 | Comfort Inn Nagoya Sakae Ekimae (H-1) | 7,740 | 240 | GOP-linked | First hotel acquisition. Appraisal value ¥8,310 million |
| December 18, 2025 | Candeo Hotels Kyoto Karasuma Rokkaku (H-2) | 4,800 | 106 | Fixed | Swapped with the four-installment sale of ONEST Kyoto Karasuma Square (¥5.0 billion in total) |
| March 19, 2026 | DoubleTree by Hilton Naha Shuri Castle (H-7) | 10,460 | 333 | GOP-linked | Acquired through a sponsor bridge |
| March 19, 2026 | The Edistar Hotel Narita (H-6) | 4,770 | 261 | GOP-linked + fixed | Scheduled to be rebranded as a Quintessa Hotel in February 2027 |
| March 19, 2026 | Quintessa Hotel Fukuoka Hakata Relax & Sleep (H-5) | 4,184 | 80 | GOP-linked | Completed August 2019 |
| March 19, 2026 | Quintessa Hotel Sapporo Susukino 63 Relax & Spa (クインテッサホテル札幌すすきの63 Relax&Spa) (H-3) | 4,020 | 103 | GOP-linked | Located in the Susukino area |
| March 19, 2026 | Quintessa Hotel Kagoshima Tenmonkan Relax & Sleep (H-4) | 1,762 | 98 | GOP-linked | Located in the Tenmonkan area |
| Total | 7 hotels | 37,736 | 1,221 | — | Acquisition prices per the portfolio list (as of July 30, 2026) |
The chart below shows the cumulative hotel acquisition price and the hotel share of the overall portfolio. The bulk acquisition in March 2026 lifted the share about 2.4-fold. The financial results presentation for the fiscal period ended February 2026 sets out an allocation policy by use of “50% or more in office buildings” and “50% or less in hotels, residential, retail and other uses.”
Rent Structure — 87% of the Acquisition Price Is on Variable Rent Including GOP-Linked Rent
Weighting the rent structures of the seven hotels by acquisition price, GOP-linked only accounts for ¥28,166 million (74.6%), GOP-linked plus fixed for ¥4,770 million (12.6%), and fixed for ¥4,800 million (12.7%). GOP-linked rent sets rent by applying a given rate to gross operating profit, that is, hotel revenue less operating expenses; the rates are undisclosed in every case. It is an upside-type contract in which rent rises when room rates and occupancy improve, and it is a structure that hotel-focused REITs have been adopting more widely in recent years.
The effect is already visible in disclosed figures. According to the financial results presentation for the fiscal period ended February 2026, RevPAR at Comfort Inn Nagoya Sakae Ekimae for that period exceeded the initial forecast by 32.1% (ADR +20.5%, OCC +7.7pt), and variable rent income landed 20.1% above the initial forecast. A location right next to Sakae Station and the ability to capture broad demand from business, leisure and events translated into upside in variable rent.
| Property | Rent structure | Operator / lessee | Appraisal NOI yield | Completed |
|---|---|---|---|---|
| DoubleTree by Hilton Naha Shuri Castle | GOP-linked | Hilton Worldwide Manage Limited | 8.3% | August 1973 |
| Comfort Inn Nagoya Sakae Ekimae | GOP-linked | Greens | 4.7% | March 2014 |
| Candeo Hotels Kyoto Karasuma Rokkaku | Fixed (fixed-term lease) | Candeo Hospitality Management | 3.9% | March 2021 |
| The Edistar Hotel Narita | GOP-linked + fixed | Core Global Management | 6.1% | February 1992 |
| Quintessa Hotel Sapporo Susukino 63 Relax & Spa | GOP-linked | Core Global Management | 5.1% | September 1991 |
| Quintessa Hotel Fukuoka Hakata Relax & Sleep | GOP-linked | Core Global Management | 4.6% | August 2019 |
| Quintessa Hotel Kagoshima Tenmonkan Relax & Sleep | GOP-linked | Core Global Management | 6.1% | February 2008 |
Appraisal NOI yields range from 3.9% to 8.3%. Newer properties in locations right by a station carry lower yields (that is, higher prices), while older properties and those acquired on the premise of value-add work carry higher yields. Kyoto Karasuma Rokkaku (completed 2021) at 3.9% and Naha Shuri Castle (completed 1973, renovation planned) at 8.3% sit at the two ends. For the latter, the yield including the ¥1.2 billion of additional post-acquisition investment is disclosed as 7.4%.
Acquisition Price per Room — Five of Seven Exceed the Hotel-Focused REIT Median
Next, we compare each property’s acquisition price per room (acquisition price divided by room count) with the distribution of the 300 domestic properties held by the seven listed hotel-focused investment corporations. Across the 300 properties, the median is about ¥24.41 million, the first quartile about ¥12.17 million and the third quartile about ¥41.02 million. Among One REIT’s seven properties, Fukuoka Hakata (about ¥52.30 million) and Kyoto Karasuma Rokkaku (about ¥45.28 million) are above the third quartile, while Sapporo Susukino (about ¥39.03 million), Nagoya Sakae (about ¥32.25 million) and Naha Shuri Castle (about ¥31.41 million) fall between the median and the third quartile. Narita (about ¥18.28 million) and Kagoshima Tenmonkan (about ¥17.98 million) are below the median but above the first quartile.
Naha Shuri Castle is a full-service hotel with 333 rooms, 10 banquet rooms, four food and beverage outlets and an outdoor pool, and its ancillary facilities take up a large area (total floor area of 27,934.89 sqm). Its acquisition price per room therefore includes the value of the banquet and food and beverage operations, and cannot be compared directly with the three limited-service Quintessa hotels. With that in mind, on the basis of disclosed leasable area, Naha Shuri Castle comes to about ¥370,000 per sqm, the lowest of the seven properties, which reads as an acquisition that secured a large amount of floor space at a price reflecting the building’s age.
As a point of reference, the table shows the median acquisition price per room of the domestic properties held by each of the seven hotel-focused investment corporations. Levels differ considerably depending on the mix of hotel types in each portfolio (limited-service versus full-service and resort) and on when the properties were acquired.
| Investment corporation | Domestic properties | Acquisition price per room (median) |
|---|---|---|
| Ichigo Hotel REIT Investment Corporation (いちごホテルリート投資法人, 3463) | 29 | Approx. ¥13.80 million |
| Invincible Investment Corporation (インヴィンシブル投資法人, 8963) | 110 | Approx. ¥23.30 million |
| Nippon Hotel & Residential Investment Corporation (日本ホテル&レジデンシャル投資法人, 3472) | 16 | Approx. ¥26.50 million |
| Japan Hotel REIT Investment Corporation (ジャパン・ホテル・リート投資法人, 8985) | 53 | Approx. ¥25.80 million |
| Hoshino Resorts REIT (星野リゾート・リート投資法人, 3287) | 71 | Approx. ¥19.30 million |
| Mori Trust REIT (森トラストリート投資法人, 8961) | 6 | Approx. ¥52.20 million |
| Kasumigaseki Hotel REIT Investment Corporation (霞ヶ関ホテルリート投資法人, 401A) | 15 | Approx. ¥45.30 million |
| 7 investment corporations, total | 300 | Approx. ¥24.41 million |
| One REIT, Inc. (3290), 7 hotels | 7 | Approx. ¥32.25 million |
Per-Room Price vs. Local ADR — Higher-Rate Cities Command Higher Prices
What explains the differences in per-room price? For the municipality where each property is located, we calculated the estimated settled ADR for September 2025 to August 2026 (12-month average) and plotted it against the acquisition price per room in the scatter chart below. The three areas of Nakagyo Ward, Kyoto (about ¥16,900), Chuo Ward, Sapporo (about ¥14,400) and Hakata Ward, Fukuoka (about ¥14,300) have high ADR, and per-room prices there are also high at about ¥39 million to ¥52.30 million. Conversely, Kagoshima (about ¥6,700) and Narita (about ¥7,900) have low ADR, and per-room prices stay at about ¥18 million. Naka Ward, Nagoya (about ¥9,600) and Naha (about ¥10,200) sit in between.
Dividing the per-room price by “annual room revenue per room assuming 100% year-round occupancy at the area’s typical ADR” gives a rough measure of how many years of revenue were paid for one room (the ADR multiple). For the seven properties it falls within 6.4x to 10.0x, a much narrower spread than the differences in ADR levels. In other words, One REIT bought cheaply in cities with low ADR and paid more in cities with high ADR, which can be interpreted as acquiring at prices in line with local rate levels. Fukuoka Hakata, with the highest multiple (10.0x), is a recent build completed in 2019, and all of its rooms have layouts that accommodate two or more guests. At Nagoya Sakae (9.2x), the scarcity of a location one minute on foot from the station appears to be reflected in the price.
| Property (municipality) | Acquisition price per room | Area estimated settled ADR (12-month average) | YoY | ADR multiple (our estimate) |
|---|---|---|---|---|
| Fukuoka Hakata (Hakata Ward, Fukuoka) | ¥52.30 million | ¥14,314 | +11.2% | 10.0x |
| Kyoto Karasuma Rokkaku (Nakagyo Ward, Kyoto) | ¥45.28 million | ¥16,943 | +1.8% | 7.3x |
| Sapporo Susukino 63 (Chuo Ward, Sapporo) | ¥39.03 million | ¥14,424 | +11.1% | 7.4x |
| Nagoya Sakae (Naka Ward, Nagoya) | ¥32.25 million | ¥9,587 | +6.5% | 9.2x |
| Naha Shuri Castle (Naha) | ¥31.41 million | ¥10,198 | +16.9% | 8.4x |
| Narita (Narita) | ¥18.28 million | ¥7,876 | −3.7% | 6.4x |
| Kagoshima Tenmonkan (Kagoshima) | ¥17.98 million | ¥6,715 | −1.5% | 7.3x |
Note that the ADR multiple is a rough measure that assumes 100% year-round occupancy; the multiple against actual room revenue will be larger. The table below shows the sensitivity when year-round occupancy is replaced with 85% and 70% in the same formula. At 70% year-round occupancy the multiples for the seven properties widen to 9.1x to 14.3x: about 14.3x for Fukuoka Hakata, about 13.2x for Nagoya Sakae and about 9.1x even for Narita, the lowest. Because the occupancy assumption does not change the ranking among properties, the 100%-basis multiple is sufficient for comparing properties with one another, but when assessing the absolute level of acquisition prices it is worth checking the occupancy-adjusted multiples as well.
| Property (municipality) | 100% year-round occupancy | 85% year-round occupancy | 70% year-round occupancy |
|---|---|---|---|
| Fukuoka Hakata (Hakata Ward, Fukuoka) | 10.0x | 11.8x | 14.3x |
| Kyoto Karasuma Rokkaku (Nakagyo Ward, Kyoto) | 7.3x | 8.6x | 10.5x |
| Sapporo Susukino 63 (Chuo Ward, Sapporo) | 7.4x | 8.7x | 10.6x |
| Nagoya Sakae (Naka Ward, Nagoya) | 9.2x | 10.8x | 13.2x |
| Naha Shuri Castle (Naha) | 8.4x | 9.9x | 12.1x |
| Narita (Narita) | 6.4x | 7.5x | 9.1x |
| Kagoshima Tenmonkan (Kagoshima) | 7.3x | 8.6x | 10.5x |
The year-on-year change in area ADR also varies. Naha is up 16.9%, Chuo Ward, Sapporo and Hakata Ward, Fukuoka are up in the 11% range, and Naka Ward, Nagoya is also firm at +6.5%. By contrast, Nakagyo Ward, Kyoto is broadly flat at a high level (+1.8%), and Narita and Kagoshima slipped slightly below the previous year. The fact that area rates are rising in Naha, Sapporo and Fukuoka, where the GOP-linked properties are concentrated, is data pointing to room for upside in variable rent. Because Narita has only 27–29 properties in the sample, its rate of change should be read with some latitude.
Location — All Seven Sit in Each City’s Commercial Core
The map shows where the seven properties are located. The five properties in Sapporo, Nagoya, Kyoto, Fukuoka and Kagoshima are within walking distance of each city’s central entertainment district or a major station, while Narita offers airport access and Naha Shuri Castle is a tourist location right by Shuri Castle. With properties spread from Hokkaido to Okinawa, the portfolio combines demand with different seasonal patterns. The financial results presentation shows that the 2025 revenue mix of the six variable-rent hotels was 47% in March–August and 53% in September–February, and it stresses that earnings are only mildly skewed between half-year periods.
Looking at the nearest commercial-use official land price point for each property (as of January 1, 2026), the largest increase is +20.0% at Sapporo Chuo 5-2, followed by +10.4% at Fukuoka Hakata 5-11 and +10.0% at Kyoto Nakagyo 5-5. Rising land prices show that the commercial value of an area is increasing, but they also mean a higher cost of acquiring hotel sites in the same area in the future. For owners of existing hotels, a higher hurdle for new supply works as a relative tailwind.
| Property | Nearest commercial-use official land price point | Distance from property | Zoning | Land price (¥/sqm) | YoY |
|---|---|---|---|---|---|
| Naha Shuri Castle | Naha 5-6 (Shuri Ikehata-cho) | Approx. 570 m | Neighborhood commercial district | 251,000 | +6.8% |
| Nagoya Sakae | Nagoya Naka 5-17 (Sakae 3-chome) | Approx. 260 m | Commercial district | 12,100,000 | +3.4% |
| Kyoto Karasuma Rokkaku | Kyoto Nakagyo 5-5 (Karasuma-dori Rokkaku-sagaru, Shichikannon-cho) | Approx. 120 m | Commercial district | 5,520,000 | +10.0% |
| Narita | Narita 5-1 (Hanazaki-cho) | Approx. 710 m | Commercial district | 187,000 | +2.7% |
| Sapporo Susukino 63 | Sapporo Chuo 5-2 (Minami 6-jo Nishi 4-chome) | Approx. 110 m | Commercial district | 2,160,000 | +20.0% |
| Fukuoka Hakata | Fukuoka Hakata 5-11 (Hakataeki-higashi 3-chome) | Approx. 180 m | Commercial district | 1,910,000 | +10.4% |
| Kagoshima Tenmonkan | Kagoshima 5-7 (Naka-machi) | Approx. 120 m | Commercial district | 631,000 | +1.0% |
Naha Shuri Castle — Rebranding From DoubleTree by Hilton and Additional Investment
Naha Shuri Castle, the largest by acquisition price, is also the property with the biggest change in operating structure among the seven hotels. According to Hilton’s “Company Overview” (updated August 25, 2026), DoubleTree by Hilton Naha Shuri Castle is one of eight DoubleTree by Hilton hotels in Japan, with 333 rooms, 10 banquet rooms and four food and beverage outlets, and it opened through a rebranding in 2016. In Okinawa, DoubleTree by Hilton Naha opened in 2012 as the brand’s first hotel in Japan, and Naha Shuri Castle followed as the prefecture’s second DoubleTree.
According to One REIT’s financial results presentation for the fiscal period ended February 2026, the hotel’s current operating contract ends in December 2026, and after a renovation period of about four months it is scheduled to reopen in May 2027 under the “Hewitt Resort” brand, operated by Core Global Management. About ¥1.2 billion of capital expenditure is planned for renovating the entrance, front desk, lobby, restaurants, pool and other areas, with stabilized operation assumed from January 2029. The strengths cited are its location as the hotel closest to Shuri Castle, and its banquet halls with capacity for large groups and one of the largest outdoor pools in Naha, which allow it to serve lodging demand from professional sports teams and student groups.
The same operator also runs the three Quintessa hotels in Sapporo, Fukuoka and Kagoshima and the Narita property, so after the Naha Shuri Castle rebranding it will operate five of the seven hotels. According to the presentation, Narita is to be rebranded as a Quintessa Hotel in February 2027 and the three Quintessa hotels are assumed to reach stabilized operation in 2028, with plans to refine revenue management and capture lodging demand from Japan and abroad. The 16.9% year-on-year rise in Naha’s area ADR is supportive data for pricing after the rebranding.
How to read the per-room price: Naha Shuri Castle’s acquisition price per room (about ¥31.41 million) becomes about ¥35.01 million once the roughly ¥1.2 billion renovation cost is added. The appraisal NOI yield after the additional investment is disclosed as 7.4%, and if the rebranding delivers higher ADR, the structure passes it directly through to the investment corporation’s earnings via variable rent.
Frequently Asked Questions
Q. What kind of REIT is One REIT, Inc.?
A. It is a listed REIT (securities code 3290) managed by Mizuho REIT Management, which has invested mainly in small and mid-sized office buildings. It has been acquiring hotels since 2025 and, as of July 30, 2026, holds 34 properties (27 office buildings and 7 hotels) with a total acquisition price of ¥151.2 billion.
Q. What are the rent structures of the seven hotels?
A. Five properties are on GOP-linked variable rent, The Edistar Hotel Narita combines GOP-linked and fixed rent, and Candeo Hotels Kyoto Karasuma Rokkaku is on fixed rent. On an acquisition-price basis, about 87% includes a GOP-linked component.
Q. Is the acquisition price per room high compared with hotel-focused REITs?
A. The weighted average of the seven properties is about ¥30.91 million, above the median of the 300 domestic properties held by seven hotel-focused investment corporations (about ¥24.41 million). However, it ranges from ¥17.98 million to ¥52.30 million by property, and the higher the local ADR level, the higher the per-room price.
Summary
One REIT’s hotel investment expanded quickly, from one property in March 2025 to seven properties and 1,221 rooms in March 2026, and the hotel share on an acquisition-price basis reached about 25%. At a weighted average of about ¥30.91 million, the acquisition price per room exceeds the median of the seven hotel-focused investment corporations, but the level corresponds closely to local ADR. ADR multiples fall within 6.4x to 10.0x, and the portfolio can be characterized as one acquired at prices in line with each city’s rate level.
On the rent side, about 87% of the acquisition price is on variable rent that includes a GOP-linked component, with a weighting toward cities such as Naha, Sapporo and Fukuoka where area ADR is growing at double-digit rates year on year. How the value-add plans over the next two to three years, including the rebranding and renovation of Naha Shuri Castle and the conversion of Narita to a Quintessa Hotel, feed through to earnings will be the basis for evaluating the hotel strategy of a diversified REIT that had centered on offices. As disclosure of each property’s operating results progresses, the relationship between area ADR trends and rental income should become verifiable in more concrete terms.
References and Sources
■ Data sources
Acquisition prices, room counts, rent structures and appraisal NOI yields were compiled from the official disclosures of One REIT, Inc. (portfolio list as of July 30, 2026, individual acquisition releases, and the financial results presentations for the 24th and 25th periods). Area ADR is the estimated settled ADR of MetroEngines Research & Consulting (seven municipalities, 27–150 properties covered per month), and the comparison universe is the 300 domestic properties held by seven hotel-focused investment corporations (disclosed acquisition prices and room counts as of September 21, 2026). Land prices are the official land prices of the Ministry of Land, Infrastructure, Transport and Tourism (as of January 1, 2026).
■ Assumptions
Acquisition price per room = acquisition price ÷ disclosed room count (261 rooms as disclosed for Narita). The weighted average is total acquisition price ÷ total rooms. ADR multiple = acquisition price per room ÷ (area estimated settled ADR × 365 days), a rough measure assuming 100% year-round occupancy. The sensitivity table replaces year-round occupancy with 85% and 70% in the same formula. Area ADR is the simple average of monthly values for September 2025 to August 2026, and YoY compares with September 2024 to August 2025.
■ Limitations and caveats
Area ADR is the level of a typical property in the host municipality, not the actual ADR of each property. The acquisition price per room includes the value of banquet halls, food and beverage outlets and the like, so the full-service Naha Shuri Castle cannot be compared directly with limited-service hotels. The correlation coefficient is a reference value based on only seven properties. Because GOP-linked rent rates are undisclosed, the sensitivity of rental income has not been estimated. Narita has only 27–29 properties in the sample, so its year-on-year change should be read with some latitude.
■ Market data
- MetroEngines Research & Consulting — estimated settled ADR (seven municipalities, September 2024 to August 2026); acquisition prices and room counts of domestic properties held by seven hotel-focused investment corporations (N=300, as of September 21, 2026)
■ REIT and operator disclosures
- One REIT, Inc. “Portfolio List” (as of July 30, 2026)
- One REIT, Inc. “Notice Concerning Acquisition and Leasing of Domestic Real Estate Trust Beneficiary Interest (Comfort Inn Nagoya Sakae Ekimae)” (March 7, 2025)
- One REIT, Inc. “Notice Concerning Acquisition of Domestic Real Estate Trust Beneficiary Interest (Candeo Hotels Kyoto Karasuma Rokkaku) and Transfer of Domestic Real Estate Trust Beneficiary Interest (ONEST Kyoto Karasuma Square)” (December 15, 2025)
- One REIT, Inc. “Financial Results Presentation for the Fiscal Period Ended February 2026 (25th Period)”
- One REIT, Inc. “Financial Results Presentation for the Fiscal Period Ended August 2025 (24th Period)”
- Hilton “Company Overview” (updated August 25, 2026)
■ Government statistics and public data
■ News
- One REIT acquires six properties including five hotels for about ¥30 billion to diversify its portfolio (estie, March 2026)
- One REIT acquires a hotel in Kyoto’s Karasuma area and sells an office building (estie, December 2025)
- One REIT acquires Comfort Inn Nagoya Sakae Ekimae and revises its earnings forecast (JAPAN-REIT.COM, March 2025)
Source: Hilton “Company Overview” (updated August 25, 2026)