

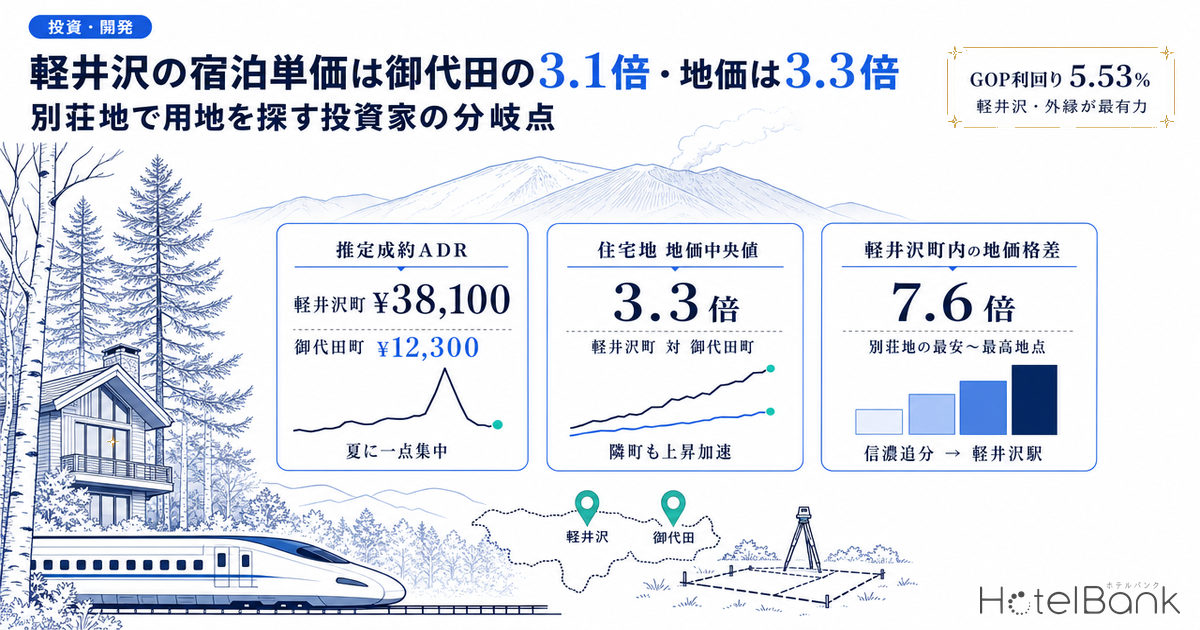
About 70 minutes from Tokyo on the Hokuriku Shinkansen, two neighbouring towns on the same southern foothills of Mt. Asama are separated by a threefold step in room rates. According to MetroEngines Research & Consulting, the estimated settled ADR for August 2026 was ¥38,100 in Karuizawa, Nagano (52 properties in the estimate), versus ¥12,300 in Miyota, the town immediately to the west (5 properties). The two are 10 km apart in a straight line — about 20 minutes by car.
The first wall a resort developer hits is that land in Karuizawa simply does not come to market. So should you cross into the next town? This article first breaks down what the price gap is actually made of, then layers on the 2026 (Reiwa 8) prefectural land price survey, the land-use regulation documents published by Karuizawa Town itself, the property-type mix of new openings, and an investment model for a single-unit vacation rental — to pin down, in numbers, the conditions under which “moving outside the town” makes sense.
Scope relative to earlier coverage: HotelBank’s Summer Resort 3-Region Comparison 2026 (Niseko, Okinawa, Karuizawa) covered demand, seasonality and FX sensitivity, but did not go into land or supply structure. This article looks not at area demand but at the municipality-level price gap and whether that gap can be justified by the difference in land cost — an investment question. It does not comment on the operation of any individual property, and every projection below is a simplified model built on public data.
Metric Definitions Used in This Article
- ADR (average daily rate) = an estimated settled rate (tax-excluded equivalent), calculated by applying property-type correction factors to each property’s lowest publicly listed plan on OTAs and similar channels (per room, 2 guests, tax included). Checked against property-level results disclosed by listed hotel REITs (91 properties, most recent 3 months), the median error is about 7%. These are estimates and differ from each property’s actual transaction prices and accounting figures. Area-level ADR is the median of the properties covered (the level of a typical property in the area).
- Listed price = the average publicly listed price across all plans (from room-only to meal-inclusive), per room for 2 guests (tax included). Because its basis differs from estimated settled ADR, the text always labels it explicitly as “listed price”.
- OCC (occupancy) = rooms sold as a share of total rooms in the area (an estimate based on OTA sales inventory).
- Data sources: MetroEngines Research / MLIT Real Estate Information Library / MLIT National Land Numerical Information / MIC & METI Economic Census / Karuizawa Town publications
- — 3.1x — Estimated settled ADR in August 2026 was ¥38,100 in Karuizawa (N=52 properties) versus ¥12,300 in Miyota (N=5). On a 12-month average, however, the gap narrows to 2.5x.
- — 3.3x — The median residential land price is ¥83,000/㎡ in Karuizawa and ¥25,250/㎡ in Miyota — almost exactly the same size as the rate gap.
- — 1.21x — Because construction costs are identical in both towns, the gap in total investment for a single-unit rental model opens no wider than this. Cheaper land does not close the rate gap.
- — 7.6x — The land price spread among holiday-home districts within Karuizawa itself. Moving west inside the town buys a bigger step than the 3.3x gained by crossing the town line.
- — 82.8% — The rate threshold at which Miyota becomes the better bet (vs. outer Karuizawa). Conventional lodging, observed at 40%, falls well short; vacation-rental-class stock comes within range.
Summary — Rates 3.1x, Land 3.3x, but Construction Costs Are the Same
The conclusions first. One: the 3.1x rate gap between Karuizawa and Miyota (August 2026) is almost the same size as the 3.3x land price gap. But land typically accounts for only 30–40% of a lodging project’s investment, and construction costs are exactly the same in both towns. So the land cost gap does not widen to 3.3x at the level of total investment. In this article’s single-unit rental model, the total investment gap is just 1.21x — far smaller than the rate gap.
Two: in the numbers, “moving to the edge of the town” comes before “moving out of the town”. In the 2026 prefectural land price survey, benchmark sites in Karuizawa’s holiday-home districts range from ¥27,500/㎡ in the Shinano-Oiwake station area to ¥210,000/㎡ in the Karuizawa station area — a 7.6x spread that is wider than the one across the town line.
Three: supply has become entirely small-scale. Of the 67 new openings identified in Nagano Prefecture in 2026, 29 (43.3%) were vacation rentals, averaging 1.2 rooms. Only one 100-room-class project is registered in the prefecture’s pipeline on a building-permit basis. In a town where land is hard to get, investment has shifted fully from “building a hotel” to “setting up a single rental unit”.
The Real Price Gap — 3.1x in August, Narrowing to 2.5x on an Annual Average
Start with the seasonality of Karuizawa’s estimated settled ADR. As a summer retreat, its rates concentrate sharply in August: ¥38,100 in August 2026 versus ¥18,700 in off-peak March — less than half. Compared with August 2025 (¥37,000), August 2026 was up 3.1% YoY, so the peak level exceeded the prior year.
Next, set it alongside the surrounding municipalities. Adding Saku (home to Sakudaira Station on the Hokuriku Shinkansen), Komoro on the Shinano Railway line, and Ueda, the August 2026 results for the five municipalities are shown below.
| Municipality | Est. settled ADR Aug 2026 | Properties in estimate | Listed price (all-plan avg, tax incl.) | Properties listed | Listed ÷ est. settled |
|---|---|---|---|---|---|
| Karuizawa | ¥38,124 | 52 | ¥66,383 | 175 | 1.74x |
| Miyota | ¥12,339 | 5 | ¥63,100 | 32 | 5.11x |
| Komoro | ¥14,933 | 13 | ¥29,825 | 27 | 2.00x |
| Saku | ¥8,472 | 14 | ¥18,715 | 22 | 2.21x |
| Ueda | ¥10,698 | 41 | ¥24,762 | 67 | 2.31x |
One point investors can easily misread deserves attention up front. The ratio of listed price to estimated settled ADR stands out at 5.11x in Miyota alone. Karuizawa is 1.74x and Saku 2.21x, so Miyota’s figure is clearly of a different nature.
The reason is the population of properties. Estimated settled ADR is calculated only for properties whose type can be confirmed (business, city, resort, ryokan, capsule), so in Miyota just 5 of the 32 listed properties qualify. The listed price, by contrast, averages the public prices of all 32, so it reflects the high rates of the vacation rentals and cottages at the centre of the town’s listed inventory. In other words, “Miyota ¥12,300” is the level of the town’s conventional lodging, not of its vacation-rental-class stock. Indeed, on listed price Miyota is ¥63,100 against Karuizawa’s ¥66,400 — a difference of just 5%.
This asymmetry becomes decisive in the investment model later on. Whether you build a conventional lodging property or set up vacation-rental-class inventory can flip the verdict on moving to the next town.
Check the full-year level as well. On a 12-month average from September 2025 to August 2026, Karuizawa is ¥23,500 against Miyota’s ¥9,400 — a ratio of 2.5x, smaller than the 3.1x for August alone. Karuizawa’s rate advantage is concentrated in the peak season and shrinks when averaged over the year.
| Municipality | Est. settled ADR 12-mo avg | Listed price 12-mo avg | Listed ÷ est. settled | Index (Karuizawa = 1.00) |
|---|---|---|---|---|
| Karuizawa | ¥23,471 | ¥50,186 | 2.14x | 1.00 |
| Miyota | ¥9,401 | ¥47,609 | 5.06x | 0.40 |
| Komoro | ¥10,159 | ¥27,106 | 2.67x | 0.43 |
| Saku | ¥7,069 | ¥16,010 | 2.26x | 0.30 |
| Ueda | ¥9,171 | ¥23,441 | 2.56x | 0.39 |
Land — 3.3x Across the Town Line, but the 7.6x Spread Within Karuizawa Is Larger
From the MLIT Real Estate Information Library, we extracted residential benchmark land prices from the 2026 (Reiwa 8) prefectural land price survey (reference date July 1, 2026). The median is ¥83,000/㎡ in Karuizawa (6 sites) and ¥25,250/㎡ in Miyota (2 sites) — a ratio of 3.29x, almost the same size as the 3.09x ratio of estimated settled ADR in August 2026.
| Municipality | Residential median (¥/㎡) | Range | Benchmark sites | YoY (simple avg) | Median change 2022→2026 |
|---|---|---|---|---|---|
| Karuizawa | ¥83,000 | ¥27,500–210,000 | 6 | +14.28% | +40.1% |
| Miyota | ¥25,250 | ¥24,000–26,500 | 2 | +14.00% | +25.9% |
| Komoro | ¥21,700 | ¥15,500–22,100 | 3 | +0.93% | +6.4% |
| Saku | ¥25,000 | ¥16,900–52,600 | 9 | +1.38% | +3.5% |
The rate of change is what stands out. Karuizawa’s residential land rose from ¥59,250 in 2022 to ¥83,000 in 2026 — up 40.1% in four years — and the latest YoY rise of +14.28% shows acceleration. Yet Miyota was also up 14.0% YoY in 2026, jumping from +5.8% in 2025. Within the same Saku region, Komoro rose only 0.93% and Saku 1.38%, so what is rising is “Karuizawa and the land directly next to it”. The premise that “the next town is still cheap” is rapidly approaching its expiry date.
Even more important is the dispersion within the town. Ranking by price the four benchmark sites in the 2026 survey that sit in Karuizawa’s Category 1 Low-Rise Exclusive Residential Zone (holiday-home districts): ¥27,500/㎡ in the Shinano-Oiwake station area, ¥31,800/㎡ in the Naka-Karuizawa station area, ¥130,000/㎡ in the Karuizawa station area, and ¥210,000/㎡ for a large holiday-home district, also in the Karuizawa station area. The cheapest and priciest are 7.6x apart. Moving west within the town yields a 4.7x step (¥27,500 vs. ¥130,000) — larger than the 3.3x gained by crossing the town line. How far land price gaps track room rate gaps is a question the same framework can be applied to in other markets, such as Kitakyushu–Kokura versus Hakata.
| Benchmark site (Karuizawa, Category 1 Low-Rise Exclusive Residential) | Price (¥/㎡) | YoY | Site area | Building coverage / FAR |
|---|---|---|---|---|
| Shinano-Oiwake station area · holiday-home district | ¥27,500 | +17.0% | 1,355㎡ | 30% / 50% |
| Naka-Karuizawa station area · holiday-home district | ¥31,800 | +15.2% | 991㎡ | 30% / 50% |
| Karuizawa station area · holiday-home district | ¥130,000 | +15.0% | 1,295㎡ | 30% / 50% |
| Karuizawa station area · large holiday-home district | ¥210,000 | +14.8% | 3,656㎡ | 30% / 50% |
Regulation — 20% FAR, a 10 m Height Cap, and Location Restrictions Due Within FY2026
Land price is not the only reason sites don’t come to market in Karuizawa. According to the town’s December 2025 document “On Land Use in Karuizawa” (軽井沢町の土地利用について), its city planning area covers 8,301 ha — 53.2% of the 15,603 ha administrative area — of which 6,288 ha is zoned. Only three zone types are designated: Category 1 Low-Rise Exclusive Residential, Category 1 Residential, and Neighbourhood Commercial — just 3 of the 13 zone types defined nationally.
On top of this, the town’s “Nature Conservation Guidelines” (自然保護対策要綱), established in 1972 (Showa 47), impose their own standards by district. The standards that bite most directly on lodging development are those for the Recreation District, which corresponds to the unzoned area.
| General standard (Nature Conservation Guidelines) | Recreation District | Commercial District | Residential District | Buffer District |
|---|---|---|---|---|
| Minimum lot size | 1,000㎡ or more | Exempt | 300㎡ or more | 500㎡ or more |
| Building coverage ratio | 20% or less | 80% or less | 60% or less | 30% or less |
| Floor area ratio | 20% or less | 200% or less | 200% or less | 50% or less |
| Number of storeys | 2 or fewer | 3 or fewer | — | 2 or fewer |
| Building height | 10 m or less | 13 m or less | — | 10 m or less |
| Setback from road | 5 m | — | 2 m | 5 m |
| Setback from adjacent land | 3 m + 1/2 of height | — | 1 m | 3 m + 1/2 of height |
The Recreation District caps the floor area ratio at 20%, so even a 1,000㎡ lot allows only 200㎡ of floor area. In addition, construction is in principle suspended in summer (July 25 – August 31), and healthy trees over 10 m tall in the road setback are in principle to be preserved — constraints that affect both the build schedule and design freedom. The “Other” section of the same guidelines states explicitly that minpaku (private lodging) facilities, capsule hotels and the like are not permitted anywhere in the town (as worded in the guidelines; simple lodging and vacation rentals licensed under the Hotel Business Act are handled under a separate framework). For anyone setting up a single-unit rental, this means a Hotel Business Act licence is a prerequisite in Karuizawa — an entry condition for the business scheme.
Moreover, regulation is currently being tightened. On March 18, 2025, the town issued its “Declaration to Protect Karuizawa’s Natural Environment and Landscape”, and it is reviewing regulations under a roadmap spanning FY2025–FY2027 (Reiwa 7–9). Two items bear directly on lodging:
Special Use District (Kyu-Karuizawa area)
In the Category 1 Residential Zone, lodging facilities of up to 3,000㎡ of floor area can currently be built. Under the new rules, both hotels and ryokan will become subject to location restrictions. In the Category 1 Low-Rise Exclusive Residential Zone, apartment buildings will be restricted. The town aims to enact the ordinance within FY2026 (Reiwa 8).
Specified Use Restriction Area (outside zoned areas)
Even in unzoned “white” areas, the town is considering designating areas that restrict construction of condominiums, hotels and similar buildings. After briefings and public comment, the revision is expected in FY2027 (Reiwa 9).
Revisions to guidelines and ordinance
Alongside revising the Nature Conservation Guidelines, changes under consideration for the ordinance on land-use procedures include dual-liability provisions that extend public disclosure to designers, contractors and construction supervisors, and the introduction of penalties of imprisonment or fines.
The one point to read as an investment matter is that the window for building new hotels and ryokan in the Kyu-Karuizawa area now has a visible end date. The district is to be “the minimum necessary area, in consideration of the impact on landowners’ property rights”, covering areas that encompass building agreement and landscape resident agreement zones, so the whole town will not close at once. Even so, the direction is for new supply in the area that commands the highest rates to be institutionally restricted — which raises the scarcity value of existing properties while pushing new entrants out toward the town’s periphery.
On the map, properties are densely distributed along Route 18 from Karuizawa Station through Naka-Karuizawa to Shinano-Oiwake and across the holiday-home districts, while on the Miyota side they are only scattered around Miyota Station and the holiday-home areas at the foot of Mt. Asama. In Saku, properties with larger room counts cluster around Sakudaira Station — a clearly different character.
Supply — 43% of New Openings Are Vacation Rentals; Only One 100-Room-Class Project in the Prefecture’s Pipeline
We identified 67 new openings in Nagano Prefecture in 2026. By property type, vacation rentals were the largest category at 29 (43.3%), with an average of 1.2 rooms. Cottages followed with 9 (average 9.2 rooms) and resort hotels with 7 (average 48.6 rooms). The national picture is the same: of 1,576 new openings nationwide in 2026, 765 (48.5%) were vacation rentals. Nationally, vacation rentals are the largest category by number of properties but only a small share once measured by room count.
Matching against property-master addresses for Karuizawa and Miyota only, new openings in Karuizawa declined by count from 17 in 2023 (81 rooms in total) to 10 in 2024 (106 rooms) and 5 in 2025 (69 rooms). Miyota went from 5 in 2023 to 3 in 2024 and 3 in 2025. Note that the 2026 figure (2 in Karuizawa) is based on confirmed listings and is still being captured, so it will increase as further listings appear.
| Year | Karuizawa openings | Karuizawa total rooms | Miyota openings | Miyota total rooms | Main types (Karuizawa) |
|---|---|---|---|---|---|
| 2023 | 17 | 81 rooms | 5 | 5 rooms | 11 vacation rentals, 2 ryokan, others |
| 2024 | 10 | 106 rooms | 3 | 7 rooms | 7 vacation rentals, 2 resort hotels, others |
| 2025 | 5 | 69 rooms | 3 | 17 rooms | 4 vacation rentals, 1 resort hotel |
| 2026 (still being captured) | 2 | 15 rooms | 0 | — | 1 resort hotel, 1 vacation rental |
The future pipeline is thinner still. Querying planning data derived from MLIT’s Building Construction Dynamics Survey for Nagano Prefecture, only one project is registered — 159 rooms in Otari Village (scheduled for completion in December 2026) — and there is no large project on a building-permit basis in the Saku region. Note, however, that this is on a building-permit basis as of the survey date; counts and rooms are expected to rise as further applications are filed, so it should be treated as the lower bound of the confirmed pipeline at present.
The distribution of property size also confirms that investment in this area has become small-ticket. Among the 304 Karuizawa properties with a confirmed room count in the property master, the median is 9 rooms; only 20 (6.6%) have 51 or more rooms, and 56 (18.4%) have a single room. Among Miyota’s 42 properties, the median is 5 rooms and 13 (31.0%) have a single room.
Crowded segment
40–200 rooms × ¥45,000–¥60,000
Karuizawa’s mid-to-large resorts cluster here. Entering the same arena as a newcomer means clearing both the regulatory and the land hurdles.
Relatively thin segment
10–40 rooms × ¥30,000–¥50,000
Mid-size and mid-priced. Few properties were observed here this time; the space between small single-unit rentals and large resorts is open.
Where Miyota sits
Only one Miyota property could be observed: 67 rooms × ¥12,300. It sits in the low-rate band for conventional lodging; the level of vacation-rental-class stock can only be captured through listed prices.
Depth of Year-Round Demand — Karuizawa Is a Tourism Employment Hub With More Workers Than Residents
The other question in deciding whether to move to the next town is the underlying strength of year-round occupancy. Using MLIT National Land Numerical Information’s 250 m-mesh future population estimates and the MIC/METI Economic Census, we compared 2 km radii around three stations.
| 2 km radius | Residents 2025 | 2040 estimate (vs. 2020) | Aged 65+ share 2025 | Establishments | Employees | Employees / residents |
|---|---|---|---|---|---|---|
| Karuizawa Station | 3,089 | 2,939 (-3.9%) | 37.4% | 822 | 5,913 | 1.91 |
| Miyota Station | 12,059 | 12,000 (+3.4%) | 28.2% | 473 | 5,418 | 0.45 |
| Sakudaira Station | 21,468 | 21,263 (-1.4%) | 23.5% | 1,353 | 13,324 | 0.62 |
The numbers run against intuition. The resident population within 2 km of Karuizawa Station is 3,089 — a quarter of Miyota Station’s — yet it has 5,913 employees, more than Miyota Station’s 5,418. Employees per resident are 1.91 for Karuizawa, 0.45 for Miyota and 0.62 for Sakudaira. Karuizawa is a tourism employment hub with more people working there than living there, while Miyota is predominantly residential.
This matters directly for investment decisions. The hypothesis that “the next town can pick up year-round business demand” is hard to sustain for Miyota. If you select on depth of employment, the candidate is the Sakudaira Station area, the deepest in the region with 1,353 establishments and 13,324 employees. But Saku’s estimated settled ADR was ¥8,500 in August 2026 (N=14 properties) — the lowest — because the product skews toward limited-service hotels and rates don’t hold up. In this region, rates and the depth of business demand are a clear trade-off.
In terms of population direction, only Miyota is on the growth side. The 2040 estimate for the Miyota Station area is +3.4% vs. 2020, in contrast to -3.9% for Karuizawa Station and -1.4% for Sakudaira Station. The aged 65+ share also differs widely: 28.2% in Miyota against 37.4% in Karuizawa. Miyota has the edge in long-term settlement demand, but that is a housing story rather than a lodging one.
On the mesh map, Karuizawa Station’s resident population is concentrated in a narrow band of town area south of the station, while the holiday-home districts to the north and west are almost blank. Holiday homes are not counted as year-round residents, so the map mirrors Karuizawa’s structure exactly: a thin permanent population coexisting with deep lodging demand. Note that trying to substantiate year-round occupancy from resident population will always underestimate Karuizawa.
As for how tight supply and demand are, occupancy for Nagano Prefecture as a whole in August 2026 (estimated, based on OTA-listed inventory) was 92.5% (557 properties, 19,508 rooms), building up to near sell-out in the peak month. This is an estimate based on the take-up of inventory sold on OTAs and differs from the properties’ overall actual occupancy.
Projection — Can the Land Cost Difference Offset a 3x Rate Gap?
We now load the figures so far into a single-unit rental model. The premise is 120㎡ of floor area (36.3 tsubo), a two-storey timber building, and one building = one unit — the format now at the centre of new openings in Nagano Prefecture.
Construction cost is shown in two stages. Stage 1 is the 2025 actual timber cost of ¥1.382M per tsubo, based on MLIT’s Building Construction Starts Statistics. Hotel construction costs rose 41% in two years, from an all-structure average of ¥1.38M per tsubo in 2022 to ¥1.95M in 2024, and remained elevated in 2025 at an all-structure average of ¥1.952M. For Stage 2, allowing for about +5% per year over the two years to groundbreaking in light of that pace, the cost per tsubo becomes ¥1.528M and the construction cost rises from ¥50.2M to ¥55.5M.
| Item | A. Karuizawa · outer holiday-home district | B. Karuizawa · near-station holiday-home district | C. Miyota · residential |
|---|---|---|---|
| Site area | 1,000㎡ | 1,000㎡ | 500㎡ |
| Land unit price (land price survey basis) | ¥29,650/㎡ | ¥130,000/㎡ | ¥25,250/㎡ |
| Land cost | ¥29.7M | ¥130.0M | ¥12.6M |
| Construction cost (2025 actual unit cost) | ¥50.2M | ¥50.2M | ¥50.2M |
| Construction cost (with +5%/yr × 2 yrs) | ¥55.5M | ¥55.5M | ¥55.5M |
| Ancillary & soft costs (25% of construction) | ¥13.9M | ¥13.9M | ¥13.9M |
| Total investment | ¥99.1M | ¥199.4M | ¥82.0M |
| Market rate index | 100 | 100 | 40 |
| Assumed ADR (per building per night, tax-excl. equiv.) | ¥75,000 | ¥75,000 | ¥30,000 |
| Assumed occupancy (full-year) / GOP margin | 50% / 40% | 50% / 40% | 50% / 40% |
| Annual revenue | ¥13.7M | ¥13.7M | ¥5.5M |
| GOP | ¥5.47M | ¥5.47M | ¥2.19M |
| GOP yield | 5.53% Top pick | 2.75% | 2.67% |
| Simple payback | 18.1 years | 36.4 years | 37.4 years |
The result is clear. Total investment differs by only 1.21x between A and C, while the market rate differs by 2.5x. Land in Miyota is ¥17M cheaper, but the building and ancillary costs of ¥69.4M are the same in both towns, so cheaper land lowers total investment by only 17%. Meanwhile, achievable rates fall by 60%. This asymmetry pushes the Miyota scenario’s yield below half that of outer Karuizawa.
Working backwards, the decision rule comes down to a single number. If Miyota can achieve 82.8% or more of the outer-Karuizawa rate, Miyota comes out ahead (total investment ratio 82.0 ÷ 99.1). Conventional lodging is observed at 40%, far below that bar. However, as shown earlier, on listed price Miyota is at 95% (¥63,100 vs. Karuizawa’s ¥66,400). In other words, if the project can be set up as vacation-rental-class inventory, Miyota may clear the threshold. This is the article’s fork in the road.
“If you are building conventional lodging, go to the edge of Karuizawa; if you are setting up vacation-rental-class stock, Miyota can also work” — the order of the site search comes down to that one sentence. The latter, however, depends on the premise that Miyota’s vacation rentals achieve rates comparable to Karuizawa’s. Listed prices are averages of public prices, not transaction prices, and with only 5 Miyota properties in the settled-rate estimate, this premise remains a hypothesis to be verified against actual on-the-ground performance.
IRR tells a different story. On the conservative assumption of flat land prices, A (outer Karuizawa) is 2.04%, B (near-station Karuizawa) 0.66% and C (Miyota) -2.34%. But assume land appreciates 5% a year, and B overtakes A at 4.19%. A near-station holiday-home site in Karuizawa is not an investment that pays off through operating yield but one that pays off through land appreciation — because land makes up 65% of the total investment. Karuizawa residential land in the 2026 survey rose 14.28% YoY, so recent performance is well above 5% a year. Still, extrapolating past appreciation into the future is also the most fragile part of any projection as a basis for investment decisions.
| Sensitivity (GOP yield) | Occupancy 40% (full-year) | Occupancy 50% (full-year) | Occupancy 60% (full-year) |
|---|---|---|---|
| A. Outer Karuizawa / ADR -10% | 3.98% | 4.98% | 5.97% |
| A. Outer Karuizawa / ADR base | 4.42% | 5.53% | 6.64% |
| A. Outer Karuizawa / ADR +10% | 4.87% | 6.08% | 7.30% |
| B. Near-station Karuizawa / ADR base | 2.20% | 2.75% | 3.30% |
| C. Miyota / ADR base | 2.14% | 2.67% | 3.21% |
| C. Miyota / ADR +10% | 2.35% | 2.94% | 3.53% |
Varying the sensitivities does not change the ranking. A still secures 3.98% even in the pessimistic case of 40% occupancy (full-year) and ADR -10%, while B and C only reach around 3.3% in the optimistic case of 60% occupancy (full-year) and ADR +10%. The rate gap translates directly into a hierarchy of yields.
Investment Verdict and Risks
Recommended: Outer Karuizawa (Shinano-Oiwake to Naka-Karuizawa)
Land costs less than a quarter of near-station sites, yet rates are achievable at the town’s level. A GOP yield of 5.53% is the highest of the three scenarios, and even under the most pessimistic assumption of 40% occupancy (full-year) and ADR -10% it still secures 3.98%. The strongest argument is that inside the town, the Karuizawa brand’s rates are available.
Conditional: Miyota
The condition for success is achieving at least 82.8% of the Karuizawa rate as vacation-rental-class stock. On listed prices it is at 95%, so it is possible, but verification on a transaction basis is essential. Land has started rising at +14% a year, so the time available to get in is shrinking.
Cautious: Near-station Karuizawa
It does not pay off on operating yield and works only on an assumption of land appreciation. In addition, in the Kyu-Karuizawa area, an ordinance due within FY2026 is set to make hotels and ryokan in the Category 1 Residential Zone subject to location restrictions, making new construction within the district institutionally difficult.
| Risk factor | Details | Impact |
|---|---|---|
| Regulation | The Special Use District for the Kyu-Karuizawa area targets enactment of an ordinance within FY2026. A revision for the Specified Use Restriction Area outside zoned areas is also expected in FY2027; until the target districts are fixed, the premises for land acquisition remain unsettled | High |
| Water infrastructure | The town explicitly lists as a land-use issue the concern that “if construction of large buildings such as hotels continues, water supply demand will increase further and stable supply for the town as a whole may become difficult” | High |
| Construction cost | Up 41% from 2022 to 2024. The longer the lead time to groundbreaking, the more upside cost risk accumulates. At the same time, it also works to restrain new supply, raising the scarcity of existing inventory | Medium |
| Land price | Karuizawa residential land is up 14.28% YoY and Miyota up 14.0%, and the rise is accelerating. Delays in acquisition timing cut directly into yield | Medium |
| Seasonal concentration | Karuizawa’s estimated settled ADR is ¥38,100 in August versus ¥18,700 in March. The annual average is ¥23,500; building a payback plan on peak rates will badly miss | Medium |
| Permits and licensing | Under the guidelines, minpaku facilities, capsule hotels and the like are not permitted anywhere in the town. Single-unit rentals require a Hotel Business Act licence | Medium |
| Construction schedule | Construction is in principle suspended in summer (July 25 – August 31). Tree felling or land alteration over 300㎡ requires prior consultation, so schedules tend to run longer than standard | Low |
Finally, three things to check as next steps. First, ask the town’s Environment Division and Construction Division directly whether the site under consideration falls within the Special Use District or the Specified Use Restriction Area. Under the roadmap, the districts will move to public inspection within FY2026. Second, verify the transaction performance of vacation-rental-class stock on the ground. The Miyota scenario in this article rests on the observed gap between listed price and estimated settled ADR, and whether that gap is filled in practice could reverse the conclusion. Third, estimate water and sewer connection feasibility and site preparation costs individually for each site. Under a 20% FAR, 5 m setbacks and tree preservation, the building you can put up and the cost of site preparation vary widely even for plots of the same size.
⚠ Note on data timing: The estimated settled ADR and listed prices in this article are based on observations as of September 13, 2026. Figures for recent and future months are estimates derived from selling prices publicly available on OTAs and other channels at the time of the survey, and will change as check-in dates approach due to new plans and price adjustments. Land prices are as of July 1, 2026, the reference date of the 2026 land price survey; regulatory items are proposals under consideration based on material published by Karuizawa Town in December 2025, and the final ordinances may change through the remaining procedures.
Related Reading
- Summer Resort 3-Region Comparison 2026: Niseko, Okinawa, Karuizawa ADR & FX Sensitivity
- Matsumoto ADR ¥13,400 vs ¥18,300 Ceiling: Absorbing 222 New Rooms
References and Sources
■ Data sources
Municipality-level estimated settled ADR and listed prices were compiled by MetroEngines Research & Consulting (September 2025 – August 2026, compiled September 13, 2026). New-opening data is based on confirmed listings; the property master comprises 399 properties with address coordinates. Land prices are from the prefectural land price survey (2022–2026) in the MLIT Real Estate Information Library; population and employment from MLIT National Land Numerical Information’s 250 m-mesh future population estimates (R6 National Land Policy Bureau projection) and the MIC/METI Economic Census for Business Activity (2021); construction costs from MLIT’s Building Construction Starts Statistics; and regulation from Karuizawa Town’s “On Land Use in Karuizawa” (December 2025).
■ Model assumptions
The single-unit rental model assumes 120㎡ of floor area (36.3 tsubo), a two-storey timber building and one unit per building. Construction cost uses ¥1.528M per tsubo — the 2025 actual timber cost of ¥1.382M per tsubo plus +5% a year over the two years to groundbreaking — with ancillary and soft costs at 25% of construction. Occupancy of 50% and a GOP margin of 40% are both full-year assumptions; annual revenue = assumed ADR × 365 days × occupancy. IRR assumes a 10-year hold, constant GOP, straight-line building depreciation over 20 years (50% residual) and 5% selling costs. Land unit prices use benchmark prices from the 2026 land price survey (as of July 1, 2026): A is the median of two holiday-home sites in the Shinano-Oiwake and Naka-Karuizawa areas, B the Karuizawa station-area holiday-home benchmark site, and C the median for Miyota residential land.
■ Limitations
Estimated settled ADR is derived from public prices and differs from each property’s actual transaction prices and accounting figures. Only 5 Miyota properties are in the estimate, and the level of the town’s vacation-rental-class stock can only be captured through listed prices (which are averages of public prices, not transaction prices). The assumed ADR, occupancy and GOP margin in the model are illustrative, not the results of actual properties, and land prices rest on a small sample of benchmark point data (6 sites in Karuizawa, 2 in Miyota). Regulatory items are under consideration, and the final target districts and content of the ordinances may change through the remaining procedures. This is a simplified model; actual investment decisions require an individual feasibility study.
■ Market data
- MetroEngines Research & Consulting — municipality-level estimated settled ADR and listed prices (September 2024 – August 2026), new-opening data (based on confirmed OTA listings), property master, occupancy (estimated, based on OTA-listed inventory)
■ Government statistics and public data
- MLIT Real Estate Information Library — prefectural land price survey and official land price publication (2022–2026; Karuizawa, Miyota, Komoro, Saku), zoning
- MLIT National Land Numerical Information — 250 m-mesh future population estimates (R6 National Land Policy Bureau projection)
- MIC & METI Economic Census for Business Activity (2021) / boundaries = 2020 Census small areas
- MLIT Building Construction Starts Statistics — construction cost per tsubo by structure, lodging buildings
- MLIT Building Construction Dynamics Survey — pipeline of planned and under-construction hotels
■ Municipal primary sources
- Karuizawa Town, “On Land Use in Karuizawa” (軽井沢町の土地利用について, December 2025) — city planning and zoning designations, summary of the Nature Conservation Guidelines, regulatory review roadmap, Special Use District rules
- Karuizawa Town, “Ordinance on Procedures for Land-Use Activities for Nature Conservation in Karuizawa” — thresholds for prior consultation
- Karuizawa Town official website