

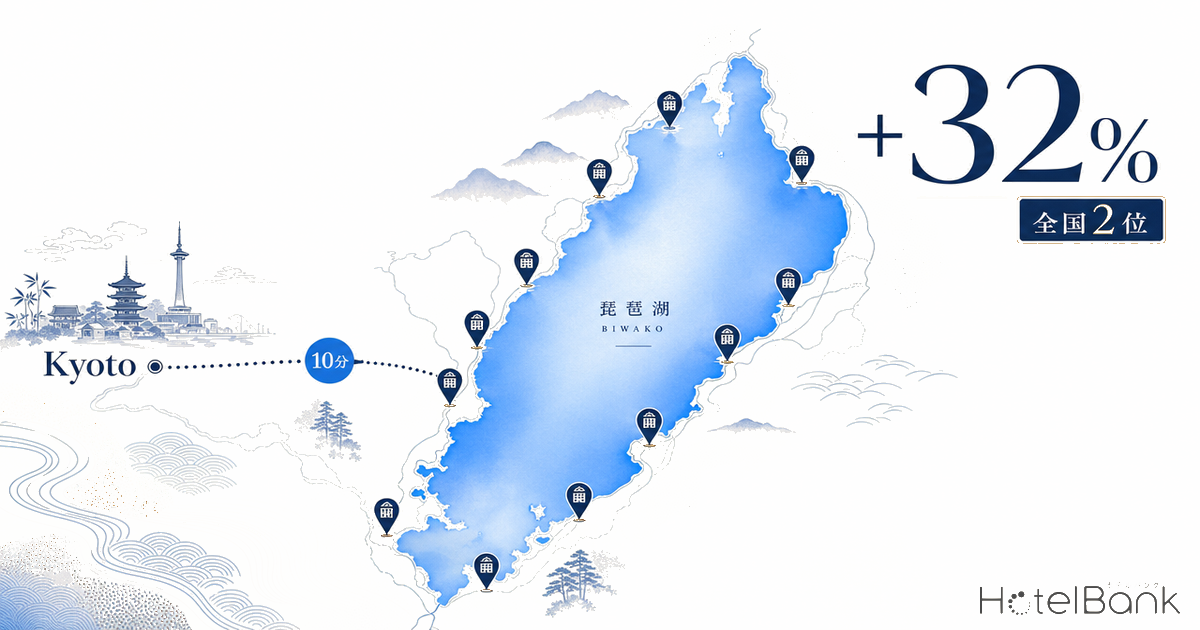
A major OTA’s summer 2026 travel trend survey, released on May 22, 2026, named one prefecture as the country’s #2 fastest-growing search destination. Behind Tokyo (+48% year-on-year, #1), Shiga Prefecture posted +32%. Regional hotel market analysis to date has concentrated on Tokyo, Osaka, Kyoto, Okinawa, and Hokkaido, while Shiga — home to Lake Biwa — has rarely been treated head-on, dismissed as a quiet, off-radar area. Yet as overtourism pushes Kyoto’s room rates ever higher, the lakeside districts of Shiga are emerging as Kyoto’s natural overflow, with a clear demand-supply opportunity opening up. This article quantifies the “10-minute neighbor discount” by comparing the monthly ADRs of Lake Biwa’s main lakeside cities — Otsu, Hikone, and Nagahama — against central Kyoto, then unpacks Shiga’s lake-view differentiation and the new supply now coming online.
Metric Definitions Used in This Article
- ADR (Average Daily Rate): Average of advertised prices on OTAs and other booking channels. Differs from actual transacted prices (cross-checks against REIT disclosures show advertised ADR tends to run +25-30% higher than transacted ADR, as unsold premium-tier plans remain visible on OTAs and pull the average up). Per-room rate for 2 guests/room (tax included), averaged across all plans (room-only through meal-included).
- Central Kyoto ADR: Weighted average (by observation count) of advertised prices across Kyoto City’s 11 wards (Shimogyo, Nakagyo, Higashiyama, Minami, and others).
- 10-Minute Neighbor Discount: Discount of Otsu City ADR vs. central Kyoto ADR = (central Kyoto ADR − Otsu ADR) ÷ central Kyoto ADR.
- Data Source: MetroEngines Research
- — Shiga ranks #2 nationwide in summer 2026 search growth (+32%) on a major OTA, an off-radar destination second only to Tokyo (+48%).
- — Otsu’s advertised ADR runs about 27% below central Kyoto on average, with the discount widening to as much as 43% during the cherry-blossom peak. The “10-minute neighbor discount” — Otsu is roughly 10 minutes from Kyoto Station by JR Special Rapid — is now structurally embedded.
- — Shiga’s prefecture-wide advertised ADR rose +27.3% YoY (about ¥29,500 → about ¥37,600), as search heat translates into actual price action.
- — Lodging supply is concentrated in the southern lake (Otsu), with the north and east still thin. Lake-view rooms and open-air baths at Omi’s heritage inns serve as a clear differentiation asset.
- — Roadside-format new supply is now opening in Nagahama and Hino. The region is shifting from “Kyoto’s overflow” to “the lakefront of choice.”
#2 in National Search Growth — Why “Japan’s Largest Lake” Suddenly Surfaced
The major OTA’s summer 2026 trend survey put the top prefectures by search-volume growth in this order: Tokyo (+48%), Shiga (+32%), Fukuoka and Gunma (tied at +22%), and Nara (+21%). Shiga was singled out for “the natural scenery centered on Lake Biwa, Japan’s largest lake, paired with historic townscapes.” Its proximity to two of the country’s strongest tourism markets — Kyoto and Osaka — combined with the scale of a true lake, is drawing in travelers looking to dodge the crowds.
This search heat is already showing up in real pricing. According to MetroEngines Research, Shiga’s prefecture-wide advertised ADR rose from about ¥29,500 in June 2025 to about ¥37,600 in June 2026, up +27.3% year-on-year. Search growth (+32%) and ADR growth (+27%) are moving almost in lockstep, suggesting that interest is now materializing as lodging demand. Why has Shiga risen at this particular moment? The answer lies in the price structure of neighboring Kyoto. The fact that Kansai-area visitor flows are spilling far beyond the immediate Kinki region has also been documented in our analysis of Osaka-Kansai Expo visitor mobility across wider Japan.
Source: Major OTA “Summer 2026 Travel Trends” (May 22, 2026), compiled by HotelBank Editorial Team
The “10-Minute Neighbor Discount” — Pricing Edge as Kyoto’s Overflow
JR’s Special Rapid service connects Otsu Station to Kyoto Station in roughly 9-10 minutes. Although the route crosses a prefectural border, in practice Otsu sits squarely inside the greater Kyoto commuter and tourism zone. Even so, room rates between the two areas diverge sharply. As of June 2026, central Kyoto’s advertised ADR (weighted average across the 11 wards) was about ¥49,700, while Otsu’s was about ¥34,400. The gap is roughly ¥15,300 — a discount of 31%.
This “10-minute neighbor discount” tends to widen during the peaks when Kyoto’s room rates spike hardest. In the April 2026 cherry-blossom window, central Kyoto rose to about ¥63,800 while Otsu held at about ¥36,400 — pushing the discount up to as much as 43%. Even on a trailing-12-month average, Otsu runs about 27% below central Kyoto, with an average gap of about ¥13,400. In other words, simply switching the booking from Kyoto to Otsu translates into savings north of ¥10,000 per night, almost as a structural constant. What’s noteworthy is that Otsu’s ADR is not simply being left low. Otsu rose from about ¥27,300 in June 2025 to about ¥40,600 in May 2026, and during the peaks the rate climbs steadily in line with Kyoto. The reason a roughly 30% gap persists is that Kyoto’s pace of ADR growth has been outrunning Otsu’s. So long as Kyoto continues to test ceilings, the lakeside cluster — Otsu first among them — will retain its pricing-side overflow capacity. For context on what is keeping Kyoto’s rates climbing, see our coverage of the one-month impact of Kyoto’s new lodging tax on hotel ADR.
Source: MetroEngines Research and HotelBank Editorial Team (central Kyoto N≈430 properties / Otsu N≈13 properties)
Distinct Profiles by Area — Pricing Across Otsu, Hikone, and Nagahama
Despite all being on Lake Biwa, the lakeside cities differ sharply in price band and character. Otsu (southern lake), the gateway with easy Kyoto commuting, sits around ¥34,000 and offers a deep mix from hot-spring ryokans (the Ogoto Onsen cluster) to business and city hotels. Hikone (eastern lake), anchored by Hikone Castle, climbed into ¥45,000-¥61,000 territory from autumn 2025 onward — the highest band in the prefecture. Nagahama (northern lake), backed by the historic Kurokabe Square townscape and Nagahama Castle, has stabilized in the ¥37,000-¥43,000 range. Taga Town (one property only) is a reference data point in the ¥23,000-¥27,000 budget band.
Source: MetroEngines Research and HotelBank Editorial Team
The table below summarizes area-level ADR for June 2025 vs. June 2026. Hikone stands out for its outsized growth, mainly because the observation set includes high-end resort properties and because tourism demand around Hikone Castle and Genkyuen Garden is pulling rates higher. Every area is up YoY, confirming that lakeside demand is lifting across the board.
| Area | 2025/06 ADR | 2026/06 ADR | YoY | N (properties) |
|---|---|---|---|---|
| Otsu City (southern lake) | ¥27,300 | ¥34,400 | +25.9% | 13 |
| Hikone City (eastern lake) | ¥25,800 | ¥56,400 | +118.9% | 11 |
| Nagahama City (northern lake) | ¥35,400 | ¥37,700 | +6.5% | 12 |
| Taga Town (ref., N=1) | ¥16,800 | ¥27,200 | +61.7% | 1 |
| Shiga Prefecture total | ¥29,500 | ¥37,600 | +27.3% | about 180 |
* Hikone’s YoY is large because the observation set includes high-end resort properties. Taga is a reference value (single property).
Lake Views and Open-Air Baths — Omi’s Heritage Inns as Differentiation Assets
Pricing edge as Kyoto’s overflow is not, by itself, enough to anchor sustained demand. Where Shiga truly differentiates is in the lake-view rooms and lakeside open-air baths that only this region can offer. When the HotelBank Editorial Team aggregated guest reviews and extracted properties most frequently mentioning “open-air bath” (rotenburo), the top of the list was dominated by lakeside ryokans and hotels.
The single most-mentioned property was Biwako Ryokusuitei (Otsu, Ogoto Onsen, 69 rooms, 122 mentions). Next came Happu-no-Yu in higashi-Omi (99 mentions, mention rate 45.6%) and Otsu’s Biwako Hotel (175 rooms, 61 mentions). For lake-view praise specifically, Hikone Castle Resort & Spa and Hotel Piazza Biwako (lakeside) both rank near the top — confirming that Shiga’s unique landscape (the lake plus its castle towns) underpins property ratings. On overall scores, smaller Ogoto Onsen ryokans such as Biwako Hanakaido (4.55) and Dantokan Kikunoya (4.67) lead.
Source: Guest review data (HotelBank Editorial Team; trailing 24 months, 206 Shiga properties)
What these properties share is that they are “chosen for the experience, not the price.” The sunset over the lake or the openness of an outdoor onsen — neither is available at a standard city hotel in Kyoto — become assets that hold ADR at a defined level while generating repeat stays. Even within an overflow market, inns with a clear lake-view differentiator can attract demand well beyond what a simple “cheaper Kyoto alternative” would imply.
Lakeside Hotel Distribution — Southern Cluster, Northern and Eastern Gaps
The map below shows the distribution of major ryokans and hotels around Lake Biwa, with circle size representing room count. The pattern is immediately clear: large hotels and onsen ryokans cluster heavily in Otsu (southern lake), while Hikone (eastern) and Nagahama (northern) remain comparatively thin in both number and scale. Kyoto-adjacent convenience drives the southern concentration — but the flip side is that Hikone and Nagahama, both equipped with strong tourism anchors, still have meaningful room to expand supply.
Source: MetroEngines Research / HotelBank Editorial Team
New Supply Coming Online — Roadside Format Lands in Nagahama and Hino
Supply is now responding to demand. Looking at the new Shiga properties that surfaced on OTAs in 2025-2026 (per MetroEngines Research), roadside-format hotel openings cluster around Nagahama City and Hino Town. The 44-room “HOTEL R9 The Yard Nagahama Inter” (opened April 2026) and 47-room “HOTEL R9 The Yard Gamo-Hino” (opened January 2026) are both highway-interchange-adjacent container-format business hotels — clearly aimed at car-borne sightseers and business travelers. July 2025 saw the opening of “Super Hotel Shiga Nagahama Natural Hot Spring” (144 rooms), adding a mid-scale property with natural-hot-spring amenities to Nagahama, the regional anchor city of the northern lake.
In Hikone, “Trail Inn Hikone” (30 rooms, August 2024) and the small-format machiya-style “HATAGO HIKONE” series have appeared in succession, deepening the castle-town lodging experience. In Nagahama, smaller higher-value-add formats — including single-party-only kominka inns — are also emerging; one example we covered is the opening of Tsunaguyado Kihei in Nagahama, Shiga. Together these moves signal supply growth at both ends: roadside / budget-tier rooms catching “priced out of Kyoto” demand, and machiya / hot-spring inns selling distinctly Shiga experiences.
| Property | Location | Rooms | OTA listing confirmed |
|---|---|---|---|
| HOTEL R9 The Yard Nagahama Inter | Nagahama | 44 | April 2026 |
| HOTEL R9 The Yard Gamo-Hino | Hino Town | 47 | January 2026 |
| Super Hotel Shiga Nagahama Natural Hot Spring | Nagahama | 144 | July 2025 |
| Trail Inn Hikone | Hikone | 30 | August 2024 |
| HATAGO HIKONE (Main / Bettei) | Hikone | 15 / 7 | July 2025 |
Source: MetroEngines Research & Consulting (OTA-listing-confirmed basis). Because listings typically appear a few months before opening, additional properties may be added going forward.
Bottom Line — From “Kyoto’s Overflow” to “The Lakefront of Choice”
Shiga’s Lake Biwa opportunity rests on three structural pillars. First, demand has clearly started moving: the prefecture ranks #2 nationally in search-volume growth (+32%) while ADR has risen +27% YoY — interest and price moving in lockstep. Second, a structural pricing edge: Otsu, 10 minutes from Kyoto by rail, sits 20-40% below central Kyoto on a near-permanent basis. Third, differentiation assets — lake-view rooms and lakeside open-air baths — that lift the region beyond pure price competition.
The implication for regional hotel investors and Kansai-area OTA managers is straightforward. As long as Kyoto continues to test pricing ceilings, southern-lake convenience (Otsu) and the demand anchors with supply headroom in the eastern (Hikone) and northern (Nagahama) lake all stand to function as the Kyoto-demand catchment. Whether a property ends up as merely a cheaper substitute, or as a chosen lakefront inn, will come down to operator-level moves. Combining existing strengths — lake views, hot springs — with stepped peak-season pricing offers meaningful room to convert the Kyoto-linked rate climb into actual revenue upside. Shiga is no longer “an untouched off-radar area”; it is becoming a market that belongs on every Kinki-area lodging map.
Note on forward-dated ADR: The ADR figures in this article are averages of advertised prices visible on OTAs at the time of the survey and will move as check-in dates approach. Prices set high today may come down via close-in discounting; please factor this in when interpreting forward-looking figures.
Related Reading
- Kyoto’s New Lodging Tax: One-Month ADR Impact (+18.6% YoY, Shift Toward High-End)
- Osaka-Kansai Expo Visitor Mobility — Tracking Demand Spillover Beyond the Kinki Region
- [On-Site Report] Tsunaguyado Kihei Opens in Nagahama, Shiga — A One-Party-a-Day Kominka Inn
References & Sources
■ Data Sources
Advertised ADR is derived from MetroEngines Research’s OTA-advertised-price dataset (monthly, by municipality, Shiga and Kyoto prefectures, June 2025 – June 2026). Search trend data is from a major OTA’s “Summer 2026 Travel Trends” (released May 22, 2026). Review ratings are aggregated from 206 Shiga properties over a trailing 24-month window.
■ Calculation Assumptions
Central Kyoto ADR is a weighted average across the city’s 11 wards. Discount rate = (central Kyoto ADR − Otsu ADR) ÷ central Kyoto ADR. Gaps and discount rates are calculated from each month’s advertised-ADR realized values; the peak month uses April 2026 and the average uses the trailing 12 months (simple mean).
■ Limitations and Caveats
ADR is on an OTA-advertised-price basis and will differ from actual realized rates. New supply is captured on an OTA-listing-confirmed basis and is therefore not exhaustive. Search-volume growth is from a single-OTA survey. Occupancy (OCC) is outside the scope of this article.
■ Market Data
- MetroEngines Research — OTA-advertised-price dataset (monthly municipality-level ADR, Shiga and Kyoto prefectures); new-supply data (OTA-listing-confirmed basis)
- HotelBank Editorial Team — Guest review data (206 Shiga properties, trailing 24-month window)
■ News and Press Releases