

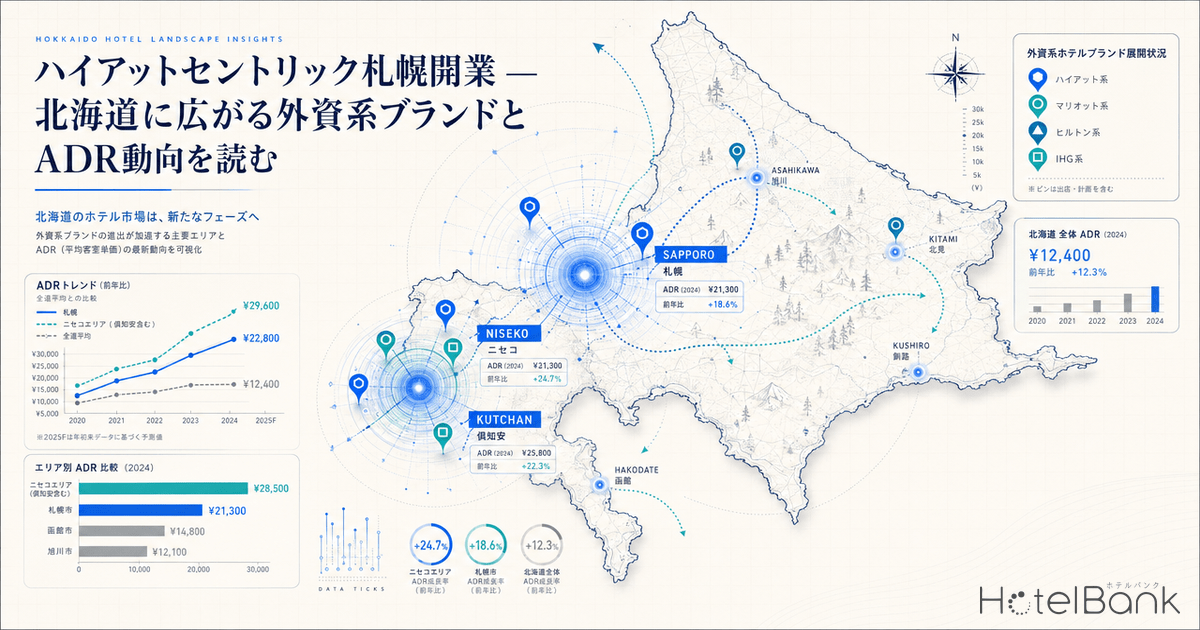

In June 2026, Hyatt Centric Sapporo (ハイアットセントリック札幌) will open after a delay of more than two years caused by construction defects. Since The Ritz-Carlton Reserve, Higashiyama Niseko Village opened in Hokkaido in 2020, foreign hotel brands have been entering the market at an accelerating pace. In central Sapporo alone, Courtyard by Marriott, Grand Mercure, MGallery, and InterContinental have all opened in the past two years. Drawing on public price data from MetroEngines Research, this article examines ADR trends by hotel grade in Sapporo, ADR gaps between major Hokkaido areas, and how surrounding ADR has historically moved before and after foreign-brand openings.
Metric Definitions Used in This Article
- ADR (Average Daily Rate): Average of publicly listed selling prices on OTAs and similar channels. Differs from actual transaction prices. Per-room rate (tax included) for two adults sharing one room, averaged across all plan types (room-only through plans with meals).
- Data Source: MetroEngines Research
Hyatt Centric Sapporo Overview — Comeback from Construction Defects
Hyatt Centric Sapporo will occupy floors 17 through 26 of “Urbannet Sapporo Link Tower,” a development by NTT Urban Development on the former site of HBC headquarters at Kita 2-jo Nishi 2-chome in Chuo Ward, Sapporo. With 216 rooms, the hotel sits about a 10-minute walk from JR Sapporo Station and is directly connected by underground passage to Odori subway station. Originally scheduled to open in spring 2024, the project was upended in March 2023 when contractor Taisei Corporation disclosed construction defects and falsified reports.
The defects were serious. Bolts joining steel frames were smaller than specifications required, with deviations averaging 4 mm and reaching up to 21 mm at 70 steel-frame locations; in addition, concrete thickness for floors and ceilings at 245 locations was on average 6 mm thinner than specifications, with the worst case 14 mm short. Steel framing already erected up to the 15th floor was entirely dismantled and rebuilt from scratch. Taisei booked roughly ¥24 billion in losses for rebuild costs and penalty payments related to the schedule slip, pushing completion back to the end of June 2026.
The comeback from construction defects carries meaning beyond a simple schedule change. Multiple redevelopment projects are under way in central Sapporo — including the North 4 East 6 redevelopment, the North 8 West 1 block, and the Tsukisamu Higashi district — and the delay of Hyatt Centric Sapporo created roughly a two-year gap in luxury and upscale supply for central Chuo Ward. As a result, InterContinental Sapporo (which opened in October 2025, discussed below) moved ahead first, and the foreign-brand opening rush ended up staggered across 2024 to 2026.
| Item | Details |
|---|---|
| Location | Kita 2-jo Nishi 2-chome, Chuo-ku, Sapporo (former HBC HQ site) |
| Building | Urbannet Sapporo Link Tower (26 floors above ground) |
| Guest Floors | 17F – 26F |
| Rooms | 216 |
| Access | 10-min walk from JR Sapporo Station / direct underground link to Odori subway station |
| Opening | June 2026 (originally spring 2024 — delayed by construction defects) |
| Developer | NTT Urban Development |
| Operator | Hyatt Hotels Corporation |
Source: Compiled by HotelBank Editorial Team from NTT Urban Development, Hokkaido Shimbun, and Tracy reports
Foreign Brand Hotels in Hokkaido — Opening Timeline
Hokkaido was long called a “blank zone” for foreign hotel brands, but the situation changed dramatically with The Ritz-Carlton Reserve’s arrival in 2020. Centered on three areas — Sapporo, Niseko, and Kutchan — major brands from Hilton, Hyatt, Marriott International, IHG, Accor, and YTL are now in place. The table below summarizes the opening timeline for major foreign-branded hotels in Hokkaido.
| Year | Hotel Name | Area | Operator | Rooms |
|---|---|---|---|---|
| 2006 | Hilton Niseko Village | Niseko | Hilton | 506 |
| 2020 | Park Hyatt Niseko HANAZONO | Kutchan Hanazono | Hyatt | 100 |
| 2020 | Higashiyama Niseko Village, A Ritz-Carlton Reserve | Niseko | Marriott | 50 |
| 2024.1 | MGallery Sapporo Factory | Sapporo (Chuo-ku) | Accor | 154 |
| 2024.4 | Grand Mercure Sapporo Odori Park | Sapporo (Chuo-ku) | Accor | 222 |
| 2024.7 | Courtyard by Marriott Sapporo | Sapporo (Chuo-ku) | Marriott | 321 |
| 2025.9 | LXR / Curio / Tapestry (3 Niseko Village rebrands) | Niseko | Hilton | ~500 |
| 2025.10 | InterContinental Sapporo | Sapporo (Chuo-ku) | IHG | ~280 |
| 2026.6 | Hyatt Centric Sapporo | Sapporo (Chuo-ku) | Hyatt | 216 |
| 2029 (planned) | Park Hyatt Sapporo | Sapporo (Chuo-ku) | Hyatt | TBD |
Source: Compiled by HotelBank Editorial Team from official chain announcements, Travel Voice, and Hokkaido Shimbun
The table makes one thing clear: 2024 was a turning point that could be called “Sapporo’s foreign-brand year one.” MGallery in January, Grand Mercure in April, and Courtyard by Marriott in July — three foreign-branded hotels opened in central Sapporo in just six months. They are followed by InterContinental in October 2025 and Hyatt Centric in June 2026, with Park Hyatt Sapporo planned for 2029. On a room-count basis, the five years from 2024 to 2029 will add more than roughly 1,200 foreign-branded rooms to central Sapporo.
In Niseko and Kutchan, Hilton rebranded the three Niseko Village hotels (Kasara, Hinode Hills, and The Green Leaf) in September 2025 as LXR Hotels & Resorts, Curio Collection by Hilton, and Tapestry Collection by Hilton respectively. Niseko alone now has Park Hyatt, Ritz-Carlton Reserve, and three Hilton brands, deepening the luxury and upper-upscale tier.
→ Tokyu Stay × Mercure Hiroshima: A Dual-Brand Strategy for Mid-Sized Cities
Sapporo ADR Trends by Grade (2024–2026)
How has the cluster of foreign-brand openings affected ADR in Sapporo? The chart below aggregates monthly ADR by grade from 2024 through August 2026, drawn from MetroEngines Research data covering roughly 210 hotels in the city. Hotels are classified into the standard five grades (Luxury / High Grade / Upper / Economy / Budget), and yearly overlays make seasonality and trend visible at the same time.
Source: Compiled by HotelBank Editorial Team from MetroEngines Research (Sapporo Luxury ~34 properties, N=approx. 300k data points/month average)
The Luxury grade rose +12.7% from 2024 to 2025, peaking at roughly ¥50,000–¥51,000 in July–August 2025. The trend continues in 2026, but growth has slowed to +2.8%, suggesting the Luxury segment is approaching supply-demand equilibrium. Next, we look at the four other grades — High Grade through Budget — together.
Source: Compiled by HotelBank Editorial Team from MetroEngines Research (Sapporo High Grade ~27 properties)
Source: Compiled by HotelBank Editorial Team from MetroEngines Research (Sapporo Upper ~74 properties)
Source: Compiled by HotelBank Editorial Team from MetroEngines Research (Economy ~26 properties, Budget ~42 properties)
| Grade | 2024 Full-Year ADR | 2025 Full-Year ADR | 2025 YoY | 2026 Jan-Aug ADR | 2026 YoY |
|---|---|---|---|---|---|
| Luxury | ¥39,200 | ¥44,100 | +12.7% | ¥45,800 | +2.8% |
| High Grade | ¥26,700 | ¥30,700 | +15.0% | ¥33,900 | +11.3% |
| Upper | ¥26,600 | ¥28,500 | +7.3% | ¥30,200 | +6.5% |
| Economy | ¥20,400 | ¥24,600 | +20.5% | ¥25,500 | +4.9% |
| Budget | ¥16,800 | ¥20,900 | +24.8% | ¥22,300 | +8.8% |
Source: Compiled by HotelBank Editorial Team from MetroEngines Research
Notable is the asymmetry of 2025 growth rates: Budget +24.8%, Economy +20.5%, High Grade +15.0%, Luxury +12.7%, and Upper +7.3%. The lowest grades posted the largest gains. This suggests that inbound demand and demand stimulation from new brand openings spread across Sapporo all the way down to lower price tiers. Equally striking is what happens in 2026 — only High Grade maintains double-digit growth at +11.3%, while other grades decelerate. The High Grade tier is precisely where new foreign brands (Courtyard by Marriott, Grand Mercure, MGallery, etc.) sharpened competition — yet rather than pushing prices down, this competition has been pushing them up.
Competitor Hotel Map — Within 1.5 km of Sapporo Station
Next, we visualize the competitive landscape around Sapporo Station, where Hyatt Centric Sapporo will open. Within a 1.5 km radius of the station, MetroEngines Research tracks 83 operating accommodation properties totaling roughly 13,900 rooms. The grade distribution is shown in the donut chart below: 23 Budget, 20 Upper, 13 Luxury and 13 High Grade, and 13 Economy properties.
Source: Compiled by HotelBank Editorial Team from MetroEngines Research
1.5 km radius from Sapporo Station (circle on map) / circle size reflects room count
Among competitors plotted on the map, the Luxury tier includes JR Tower Hotel Nikko Sapporo (342 rooms), ANA Crowne Plaza Sapporo (412 rooms), and Hotel Keihan Sapporo (200 rooms). In the “lifestyle upper-upscale” space that Hyatt Centric targets, direct foreign-brand competitors within a 10-minute walk of the station are currently limited, giving the property a strong positioning advantage. JR Tower Hotel Nikko Sapporo is the largest Luxury supplier within 1 km, but it has been operating for over 20 years; Hyatt Centric, opening in 2026, can clearly differentiate from this 2003-vintage property on facilities alone.
Hokkaido Area ADR Map (May–September 2026)
Hokkaido is not a single market. Sapporo’s business demand, Niseko’s inbound ski plus summer-resort demand, Furano’s lavender tourism, Hakodate’s heritage tourism, and Noboribetsu’s onsen demand each have very different seasonality and price levels. The chart below compares ADR across six major Hokkaido areas for May to September 2026.
Source: Compiled by HotelBank Editorial Team from MetroEngines Research (May–September 2026 average; circle size reflects ADR level)
Source: Compiled by HotelBank Editorial Team from MetroEngines Research (May–September 2026; property counts: Niseko/Kutchan 123, Noboribetsu 26, Otaru 85, Furano area 119, Sapporo 288, Hakodate 153)
Perhaps surprisingly, the highest ADR for summer 2026 belongs to Noboribetsu. At ¥62,500, it sits roughly 61% above Sapporo’s ¥38,700, reflecting the concentration of high-rate onsen ryokan and the dense demand spread across a limited number of year-round properties. Niseko/Kutchan ranks second at ¥56,800, but this is summer (off-season) data; in winter peak (December–February), the area’s ADR climbs into the ¥150,000–¥200,000 range. Sapporo, at ¥38,700, sits below Niseko, Otaru, and Furano despite having the largest hotel supply in Hokkaido. This reflects the dispersion effect of 288 properties and a structure that mixes business and tourism hotels across a wide range of price points.
→ Hokkaido in June: How Do Hotel Prices Move? 2026 ADR Comparison Across 6 Cities
Area ADR Movement Around Foreign-Brand Openings — Historical Cases
To anticipate how Hyatt Centric Sapporo’s opening might affect surrounding ADR, past foreign-brand luxury openings provide useful reference points. We visualize area Luxury ADR before and after two cases: Bulgari Hotel Tokyo (in front of Tokyo Station, opened April 2023) and Waldorf Astoria Osaka (in front of Osaka Station, opened April 2025).
Source: Compiled by HotelBank Editorial Team from MetroEngines Research (Tokyo Chiyoda-ku and Chuo-ku Luxury ~110 properties, monthly average)
In the Tokyo Station area, Luxury ADR was ¥49,200 in March 2023 — the month before Bulgari Hotel Tokyo opened. It then rose stepwise to ¥52,100 in April (opening month), ¥55,700 in September, and ¥57,900 by November. Roughly +13% six months after opening and +14% one year out — consistent with the hypothesis that the arrival of an ultra-luxury brand pulled neighboring incumbents’ pricing strategies upward. When a hotel priced at ¥250,000–¥4,000,000 per night enters the market, existing Luxury properties (in the ¥50,000s) can be psychologically repositioned as mid-range, making it easier for incumbents to raise rates as well.
Source: Compiled by HotelBank Editorial Team from MetroEngines Research (Osaka Kita-ku Luxury ~14 properties, monthly average)
In Osaka’s Kita Ward (around Umeda and Grand Green), Luxury ADR was ¥69,700 in March 2025 — the month before Waldorf Astoria Osaka opened — and surged 26% to ¥87,900 in April 2025 (opening month). Both the buzz of the opening and the simultaneous start of Expo 2025 Osaka/Kansai (April 13) drove this spike. What is striking, though, is the trajectory after one month: ¥80,100 in May, ¥73,200 in September, and ¥84,700 in October. Even after the peak fades, the area continues to trade above the pre-opening baseline of around ¥70,000.
From the Tokyo and Osaka cases, three implications can be drawn for Sapporo. First, new luxury and upscale foreign-brand openings tend to push existing properties’ prices up rather than down (the price-tier-lift effect dominates the cannibalization effect). Second, the immediate post-opening surge typically calms within one to three months, but the baseline stabilizes above the pre-opening level. Third, while the effect is amplified when paired with one-off events like an Expo or Olympics, a meaningful lift is observed even from pure brand-opening effects.
→ Kansai Luxury Hotel Supply-Demand Inflection — Reading 2026 with DBJ Estimates and OTA Data
Applied to Sapporo, the consecutive foreign-brand openings — InterContinental Sapporo (October 2025), Hyatt Centric (June 2026), and Park Hyatt Sapporo (planned 2029) — are likely to structurally lift the Luxury and High Grade price tiers in central Chuo Ward. Indeed, our grade-level ADR analysis shows Sapporo’s High Grade tier maintaining +11.3% growth into 2026, evidence that the effect is already materializing.
Conclusion — Mid-Term Outlook for Sapporo’s Foreign-Brand Rush
Key takeaways from this article. First, Hyatt Centric Sapporo, a comeback project from construction defects, is set to open with 216 rooms in June 2026 and will play a central role in central Sapporo’s foreign-brand cluster phase. Second, over the two years from 2024, central Sapporo entered an opening rush of foreign-branded hotels — MGallery, Grand Mercure, Courtyard by Marriott, InterContinental, and Hyatt Centric — and including Park Hyatt Sapporo in 2029, more than roughly 1,200 rooms of new supply are planned. Third, despite this supply growth, Sapporo’s grade-level ADRs all rose by roughly low double digits from 2024 to 2025, and the High Grade tier continues to grow at +11.3% in 2026. Fourth, the Tokyo and Osaka cases show that new foreign-brand luxury openings tend to lift incumbents’ rates rather than drag them down.
Comparison across major Hokkaido areas reconfirms that Hokkaido is not a single market — Noboribetsu, Niseko, and Otaru all exceed Sapporo on ADR, with multiple independent supply-demand balances. Hyatt Centric Sapporo’s opening is likely to deepen the high-rate hotel supply in central Sapporo and contribute to lifting ADR at surrounding properties. For revenue managers, the period from immediately before opening through the following six months calls for weekly monitoring of nearby ADR movements — with quick response to demand shifts and price-tier reordering driven by new supply.
Related Links and Sources
- NTT Urban Development — “Urbannet Sapporo Link Tower / Hyatt Centric Sapporo” official page
- Travel Voice — “Hilton rebrands three hotels at Niseko Village” (2025/9/8)
- Travel Voice — “Waldorf Astoria Osaka opens reservations ahead of April 2025 opening” (2024/12/9)
- Hokkaido Shimbun — “Park Hyatt to enter Sapporo as foreign brands open in succession”
- Hyatt Hotels Corporation — Press release on Park Hyatt brand introduction in Sapporo
- Japan Tourism Agency — Official site
Note on future-dated ADR: ADR figures in this article are averages of selling prices listed on OTAs at the time of survey and will fluctuate as check-in dates approach. Prices set high today may decline through last-minute markdowns.
Related Articles
- Hokkaido in June: How Do Hotel Prices Move? 2026 ADR Comparison Across 6 Cities
- Tokyu Stay × Mercure Hiroshima: A Dual-Brand Strategy for Mid-Sized Cities
- Long-Established Ryokan Succession Crisis — 89 Bankruptcies, 30% Without Successors
- Hotel Dining for Special Occasions — Tokyo, Osaka, and Nagoya Luxury Hotel Review Rankings
- Summer 2026: Okinawa, Hokkaido, and Kyoto Hotel Price Comparison — When Is the Best Time to Book?
- How TSMC’s Arrival Moved Kumamoto Hotel ADR — Expectation vs. Reality
Recommended Reading
- Hokkaido in June: How Do Hotel Prices Move? 2026 ADR Comparison Across 6 Cities
- Tokyu Stay × Mercure Hiroshima: A Dual-Brand Strategy for Mid-Sized Cities
- Long-Established Ryokan Succession Crisis — 89 Bankruptcies, 30% Without Successors
- Hotel Dining for Special Occasions — Tokyo, Osaka, and Nagoya Luxury Hotel Review Rankings
- Summer 2026: Okinawa, Hokkaido, and Kyoto Hotel Price Comparison — When Is the Best Time to Book?
- How TSMC’s Arrival Moved Kumamoto Hotel ADR — Expectation vs. Reality