

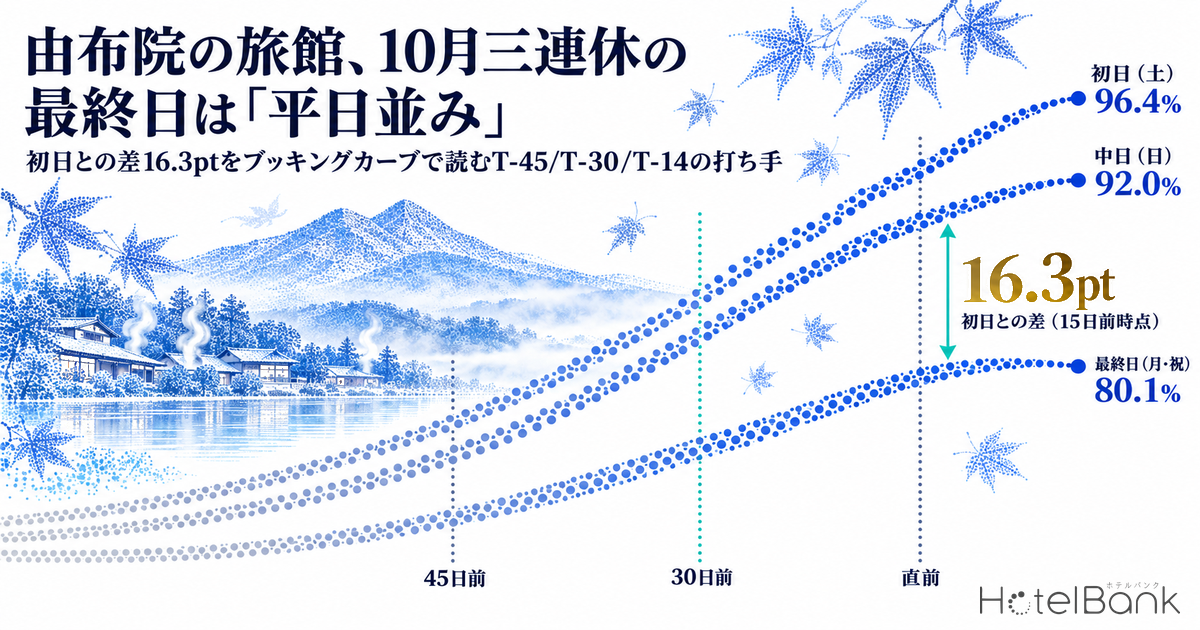
Ryokan (traditional Japanese inns) in Yufu City, Oita Prefecture, home to the Yufuin hot-spring area, show a clear “trough” in booking progress for the October three-day weekend (October 10-12). For a fixed set of properties (N=99 properties, 1,181 rooms), estimated OCC (based on OTA-listed inventory) 15 days before the stay date stands at 96.4% for Day 1, Saturday October 10, and 92.0% for Day 2, Sunday October 11, but only 80.1% for the final day, Monday October 12 (a national holiday). The 16.3pt gap to Day 1 leaves the holiday in the same band as October weekdays (Mondays and Tuesdays) at the same number of days out. The share of properties with no listed inventory visible (estimated sold-out rate) in the latest observation is also less than half: 72.7% for October 10 versus 35.4% for October 12. This article traces how the trough formed at three checkpoints (45 days out, 30 days out and the latest observation) and turns it into a practical T-45 / T-30 / T-14 playbook.
Scope: ryokan in Yufu City, Oita Prefecture, N=99 properties (1,181 rooms). Benchmarks: all ryokan in Oita Prefecture, N=230-231 properties, and resort hotels in Oita Prefecture, N=32 properties. Price figures in this article are the estimated settled ADR (the settled price level estimated from OTA and other sales data, tax-excluded equivalent); occupancy is an estimate based on OTA-listed inventory. Both are defined at the end of the article. Data as of: September 28, 2026.
- — 16.3pt — Estimated OCC for Yufu City ryokan (N=99 properties, 1,181 rooms) 15 days out is 96.4% for Day 1 (Sat, Oct 10) and 80.1% for the final day (Mon, Oct 12, holiday). The final day sits in the same band as October Mondays and Tuesdays at the same number of days out.
- — The gap opens early — From 45 to 30 days out, Day 1 added +10.9pt and the final day +7.4pt. From 30 to 15 days out the gains were almost identical (+8.8pt and +9.9pt), so this is not a late-stage stall.
- — A shallow trough by Oita standards — At 30 days out, the Day 1 vs final-day gap is 17.4pt for Yufu City ryokan, against 21.8pt for all Oita ryokan and 25.5pt for Oita resort hotels.
- — A wide, shallow trough — On October 12, 19 of 80 properties (23.8%) still have more than 50% of their inventory left, with a median remaining share of 25.0% (as of September 28, 2026). Many properties are holding inventory on the same night.
- — Protect the rate — The estimated settled ADR for Yufu City ryokan was ¥24,686 in October 2025 (final; +10.0% YoY), the start of the high-rate autumn-winter season. Filling the night should rely on multi-night conditions, single-night options and stay value.
Booking Curves for the Three Nights — Only the Final Day Follows a Weekday Trajectory
The chart below overlays estimated OCC (based on OTA-listed inventory) for Yufu City ryokan (N=99 properties, 1,181 rooms) for the three nights of the October long weekend and for Saturday, October 3, the Saturday one week earlier, from 45 days before the stay date through the latest observation (observed September 27).
Day 1, Saturday October 10, started at 76.7% at 45 days out, the highest starting point of any October stay date, then built to 87.6% at 30 days out and 96.4% at 15 days out. Day 2, Sunday October 11, followed a few points behind at 71.8%, 81.0% and 92.0%. The final day, Monday October 12 (holiday), went from 62.8% to 70.2% to 80.1%. The 13.9pt gap to Day 1 at 45 days out widened to 17.4pt at 30 days out and was still 16.3pt at 15 days out.
Source: Compiled by HotelBank Editorial Team from MetroEngines Research (Yufu City ryokan, N=99 properties / 1,181 rooms; based on listings on major booking sites)
What stands out is that the final day’s pickup pace is not much different from Day 1’s. From 30 to 15 days out, October 10 added +8.8pt, October 11 +11.0pt and October 12 +9.9pt. The final-day trough stems less from “not selling close in” than from the gap that opened in the early window between 45 and 30 days out. In that window October 10 gained +10.9pt against +7.4pt for October 12, and that gap has carried through to today.
Comparing with weekdays at the same number of days out makes the final day’s position clearer. At 30 days out, estimated OCC was 70.2% for Monday October 12 (holiday), 73.7% for the following day, Tuesday October 13, 77.5% for Monday October 19 a week later, and 67.2% for Monday October 5 a week earlier. At 16 days out it was 80.9% for October 12, 82.5% for October 13 and 77.0% for October 5. Although it is a holiday night, demand for the final day, followed by a regular workday, is moving market-wide “like a weekday”.
| Stay date | 45 days out | 30 days out | 16 days out | Pickup, 45 to 16 days out | Latest (days out) | Sold-out rate (latest) |
|---|---|---|---|---|---|---|
| Sat, Oct 3 | 62.9% | 71.5% | 78.0% | +15.1pt | 82.0% (6 days) | 36.4% |
| Mon, Oct 5 | 59.2% | 67.2% | 77.0% | +17.8pt | 79.5% (8 days) | 38.4% |
| Sat, Oct 10 | 76.7% | 87.6% | 95.5% | +18.8pt | 96.2% (13 days) | 72.7% |
| Sun, Oct 11 | 71.8% | 81.0% | 92.5% | +20.7pt | 92.5% (14 days) | 59.6% |
| Mon, Oct 12 (holiday) | 62.8% | 70.2% | 80.9% | +18.1pt | 80.1% (15 days) | 35.4% |
| Tue, Oct 13 | 66.0% | 73.7% | 82.5% | +16.5pt | 82.5% (16 days) | 47.5% |
Source: Compiled by HotelBank Editorial Team from MetroEngines Research (Yufu City ryokan, N=99 properties / 1,181 rooms. Estimated OCC = based on OTA-listed inventory. Sold-out rate = share of properties with no listed inventory visible on OTAs and other channels, estimated. Latest observation: September 27, 2026)
Looking at the pickup column, October 12’s +18.1pt is almost the same as weekday October 5 (+17.8pt). Day 1 and Day 2 of the long weekend were already high at 45 days out and kept building from there, whereas the final day is growing “from the same starting point as a weekday, at the same pace as a weekday”. Filling the trough therefore comes down to one question: how to close that gap in the starting point.
Comparison with All Oita Ryokan and Resort Hotels — Yufu City’s Trough Is Relatively Shallow
Looking at the same long weekend for all ryokan in Oita Prefecture (N=230-231 properties, about 3,660 rooms) and Oita resort hotels (N=32 properties, 1,492 rooms), the final-day trough is actually deeper than for Yufu City ryokan. At 30 days out, the Day 1 vs final-day gap is 17.4pt for Yufu City ryokan, 21.8pt for all Oita ryokan and 25.5pt for resort hotels.
| Segment | N (properties / rooms) | 10/10 45 days out | 10/10 30 days out | 10/10 latest (13 days) | 10/12 45 days out | 10/12 30 days out | 10/12 latest (15 days) | Gap at 30 days out |
|---|---|---|---|---|---|---|---|---|
| Yufu City ryokan | 99 / 1,181 | 76.7% | 87.6% | 96.2% | 62.8% | 70.2% | 80.1% | 17.4pt |
| Oita ryokan | 231 / 3,664 (10/12: 230 / 3,659) | 77.3% | 87.4% | 95.7% | 58.2% | 65.6% | 77.9% | 21.8pt |
| Oita resort hotels | 32 / 1,492 | 79.6% | 86.9% | 91.6% | 53.2% | 61.4% | 74.3% | 25.5pt |
Source: Compiled by HotelBank Editorial Team from MetroEngines Research (Estimated OCC = based on OTA-listed inventory; based on listings on major booking sites. Latest observation: September 27, 2026)
Day 1 levels are roughly the same across the three segments (all in the 90% range at the latest observation); the difference lies on the final-day side. Yufu City ryokan started the final day from a higher base at 45 days out (62.8%) than all Oita ryokan (58.2%) or resort hotels (53.2%). Resort hotels start the final day low at 45 days out and chase with later pickup. For Yufu City ryokan, the final day is also a night that is “relatively well filled compared with the rest of Oita”, which makes it easier to widen the net through booking conditions rather than chase volume with rate cuts.
Remaining Inventory by Property — On the Final Day, One in Four Properties Still Holds Over Half
Area-wide estimated OCC alone cannot tell whether “a few properties are holding a lot” or “many properties are holding a little”. We therefore compared, for the three nights, the distribution of remaining inventory as of September 28 (current listed rooms as a share of the maximum listed during the observation period) among Yufu City ryokan that have listed at least 30% of their total rooms on OTAs and other channels.
Source: Compiled by HotelBank Editorial Team from MetroEngines Research (Yufu City ryokan; properties that have listed at least 30% of total rooms. 10/10 N=64 properties / 590 rooms, 10/11 N=75 properties / 736 rooms, 10/12 N=80 properties / 817 rooms. As of September 28, 2026)
| Stay date | N (properties) | None left | 1-25% left | 26-50% left | Over 50% left | Median remaining |
|---|---|---|---|---|---|---|
| Sat, Oct 10 | 64 | 37 (57.8%) | 21 (32.8%) | 4 (6.3%) | 2 (3.1%) | 0.0% |
| Sun, Oct 11 | 75 | 32 (42.7%) | 32 (42.7%) | 7 (9.3%) | 4 (5.3%) | 7.7% |
| Mon, Oct 12 (holiday) | 80 | 17 (21.3%) | 24 (30.0%) | 20 (25.0%) | 19 (23.8%) | 25.0% |
Source: Compiled by HotelBank Editorial Team from MetroEngines Research (Remaining inventory = current listed rooms as a share of the maximum listed during the observation period. Properties aggregated anonymously)
On October 10, most properties have nothing left and the median is 0.0%. On October 12, only 21.3% have nothing left, and 19 properties (23.8%) still hold more than half their inventory. The final-day trough is not concentrated in a few properties; it is a wide trough in which many properties hold anywhere from “a little” to “about half”. For any single property, this means many competitors in the city are holding similar inventory on the same night. Rather than competing on price alone, building reasons to be chosen, such as options for single-night demand and added stay value, is the more likely route to filling rooms while protecting the rate.
For reference, we checked the outcome of the previous long weekend in September (September 19-23) using estimated OCC one day before arrival for the same Yufu City ryokan (N=100-101 properties). Saturday September 19 closed at 98.6%, Sunday the 20th at 100.0%, Monday the 21st (holiday) at 100.0% and Tuesday the 22nd (holiday) at 99.2%, whereas the final day, Wednesday September 23 (holiday), followed by a workday, closed at 89.9%, level with the post-holiday weekdays of Thursday September 24 (91.0%) and Friday the 25th (89.8%). The pattern of a long weekend’s final day landing at weekday levels was already visible in September. The same structure, with a trough on the holiday final day of the October long weekend, can also be seen in the October long weekend in Shizuoka’s Izu and Atami area.
Where October Sits on Estimated Settled ADR — Seasonal Shape with Rates Rising from Autumn into Year-End
We check pricing with the monthly estimated settled ADR. For Yufu City ryokan (N=117-129 properties, varying by month), the final estimated settled ADR was ¥22,400 in October 2024 (N=123) and ¥24,700 in October 2025 (N=120), +10.0% YoY. In 2025 it moved from ¥24,700 in October to ¥26,000 in November and ¥27,200 in December, the highest price band of the year. October, as the start of the autumn foliage season, marks the beginning of the high-rate autumn-winter season.
Source: Compiled by HotelBank Editorial Team from MetroEngines Research (Yufu City ryokan. Estimated settled ADR, tax-excluded equivalent. Solid line = final; dashed line = estimate based on current sales)
| Month | Estimated settled ADR (Yufu City ryokan) | N | Status | YoY |
|---|---|---|---|---|
| October 2024 | ¥22,439 | 123 | Final | — |
| October 2025 | ¥24,686 | 120 | Final | +10.0% |
| August 2026 | ¥22,574 | 128 | Final (latest final month) | -5.0% |
| October 2026 | ¥24,918 | 128 | Estimate based on current sales | Compare with final figures after month-end |
| (Reference) Oita ryokan, October 2025 | ¥18,082 | 301 | Final | — |
Source: Compiled by HotelBank Editorial Team from MetroEngines Research (Category = ryokan. Estimated settled ADR, tax-excluded equivalent, monthly)
The estimated settled ADR for October 2026 is ¥24,900 (N=128), an estimate based on current sales. It may change with further sales, and a straight comparison with last year’s final figure has to wait until the month closes. The latest final month, August 2026, came in at ¥22,600 (N=128), -5.0% YoY. On the other hand, January and February 2026 were up +7.9% and +13.6% YoY, so the position relative to last year shifts from month to month even within the year. How to read October’s outcome is best judged once the month-end final figure is in.
Note that estimated settled ADR is a monthly metric and does not show price levels for individual nights of the long weekend or by day of week. This article limits its day-level analysis to estimated OCC (based on OTA-listed inventory) and uses price only to establish the seasonal shape: as a month, October sits at the start of the high-rate autumn-winter season. October estimated settled ADR for Yufu City ryokan is well above that of all Oita ryokan (¥18,100 final for October 2025, N=301), so any plan to fill the final-day trough should start from not breaking this rate band.
For Revenue Managers at Yufu City Ryokan — Insights and an Action Plan for Filling the Final-Day Trough
Insight 1: The trough is created by the early-window gap. The final day’s pickup pace is not much different from Day 1’s; the gap opened between 45 and 30 days out (Day 1 +10.9pt, final day +7.4pt). When reviewing your own pace for October 12, check first how many inquiries and bookings came in for final-day-only inventory between 45 and 30 days out, before looking at close-in sales. If that window looks like a weekday, your property likely has the same trough as the market.
Insight 2: The final day sells as a “weekday”, not a “holiday”. At the same number of days out, estimated OCC for October 12 is in the same band as October Mondays and Tuesdays. If your rate calendar or booking conditions treat the final day as part of the “long weekend” alongside Days 1 and 2, there may be a mismatch with how demand actually sees it. It is worth checking whether weekday conditions (single-night stays and one-night plans) can also be applied to the final day.
Insight 3: The trough is wide and shallow. On October 12, 19 properties (23.8%) have more than half their inventory left, while another 44 have 1-50% left. With many properties in the city holding inventory on the same night, competing through discounts tends to become a race to erode rates. Precisely because October is when estimated settled ADR enters the high-rate autumn-winter season (¥24,700 final for October 2025), priority should go to added value that gets you chosen, such as late check-out, shuttle service, and in-house spending like dinner or hot-spring hopping.
Insight 4: The same shape can repeat on the next long weekend. In September as well, the final day, September 23, stood at 89.9% one day before arrival, lower than the other nights of the holiday (98.6-100.0%), and closed level with the post-holiday weekdays. The November long weekend (November 21-23) has the same structure, with the final day a Monday holiday, so this October curve can serve as a benchmark when preparing that final day.
| Timing | Action | Trigger (figures from this article) | Aim |
|---|---|---|---|
| T-45 | Review multi-night conditions that include the final day. Even if you restrict Day 1 single-night sales, keep Day 2 + final-day two-night stays and final-day single nights open | If your property shows the same pattern as the market, where the final day starts 13.9pt below Day 1 at 45 days out (62.8% vs 76.7%) | Narrow the early-window gap (45 to 30 days out) |
| T-45 | List final-day-only value-added plans early (late check-out, shuttle to the station or sights, next-morning day-use bath, etc.) | If the final day is tracking in the same band as weekdays at the same days out (Tue Oct 13: 73.7% at 30 days out) | Create reasons to be chosen through stay value, not discounts |
| T-30 | Based on Day 1 and Day 2 inventory, consider sales paths that steer inquiries for filled nights to the final day (suggest a date change; offer perks rather than a second-night discount) | If, as in the market, Day 1 is at 87.6% and the final day at 70.2% at 30 days out, a 17.4pt gap | Shift overflow demand to the final day |
| T-30 | Hold final-day rates within the month’s rate band and strengthen the offer by bundling in-house spending such as a dinner upgrade or on-site credit | If you want to fill without breaking the rate, given that October estimated settled ADR marks the start of the high-rate autumn-winter season (¥24,686 final for October 2025) | Balance rate protection and occupancy |
| T-14 (this year’s 10/12 is today) | Check booking conditions so final-day inventory can also accept single-night and last-minute demand (room-only or breakfast-only, late check-in) | If your final day is holding more inventory than the market’s 35.4% sold-out rate and 25.0% median remaining inventory | Do not miss close-in, weekday-type demand |
| T-14 onward | Record your own curve for the October long weekend and reuse it to prepare for the November long weekend (for the final day, November 23: T-45 is October 9, T-30 is October 24) | If, as with the September final day (89.9%), the October final day is confirmed to close at weekday levels | Bring the early window forward for the next long weekend |
All of the above are starting points for discussion based on market-wide estimates and do not guarantee results. Decisions should be made after checking against your own booking data.
Summary — Three Yardsticks for Reading a Long Weekend’s Final Day
| Yardstick | Value for Yufu City ryokan this time | How to use it |
|---|---|---|
| Day 1 vs final-day gap (same days out) | 13.9pt at 45 days out, 17.4pt at 30 days out, 16.3pt at 15 days out | If the gap widens by 30 days out, early-window preparation is the issue |
| Final day vs weekdays | At 30 days out: Oct 12 70.2%, Oct 13 73.7%, Oct 5 67.2% | If in the weekday band, sell the final day under weekday-type conditions |
| Spread of remaining inventory across properties | Oct 12: 23.8% of properties with over 50% left; median 25.0% | The wider the trough, the more you should differentiate on conditions and added value rather than price |
For Yufu City ryokan over the October long weekend, Days 1 and 2 have reached the 90% range at the latest observation, while only the final day, October 12, is following a weekday trajectory. The cause of the trough lies not in a late-stage stall but in the early window from 45 to 30 days out, and at the property level it is a “wide, shallow trough” in which many properties each hold some inventory. October is also when estimated settled ADR enters the high-rate autumn-winter season, so filling the final day through multi-night conditions, options for single-night stays and stay value is easier to justify than competing on discounts. This curve can be used directly as a yardstick for preparing the November long weekend, which has the same structure.
About the Data
| Estimated OCC (based on OTA-listed inventory) | OTA-listed inventory-based occupancy = 100 – 100 x OTA-listed remaining rooms / total rooms. Covers a fixed cohort of properties that list at least 30% of their total rooms on OTAs (the same set of properties for each stay date). It is an estimate based on how OTA-sold inventory is being absorbed and is defined differently from actual room occupancy (rooms not listed are counted as sold, so it tends to read high). |
| Booking curve | Based on observations from 45 days before the stay date through the latest. October stay dates use observations through September 27, 2026; September stay dates use the value one day before arrival. |
| Estimated settled ADR | The settled price level (tax-excluded equivalent) estimated from OTA and other sales data (lowest-plan price level x segment-specific factor, ensembled across multiple channels). Past months are final values; current and future months are estimates based on current sales. Median error of 6.6% when reconciled against published operating results. Category is ryokan (a separate category from resort hotels). |
| Sold-out rate / remaining inventory | Sold-out rate = share of properties with no listed inventory visible on OTAs and other channels (estimated). Remaining inventory = current listed rooms as a share of the maximum listed during the observation period, aggregated anonymously for properties that have listed at least 30% of their total rooms. |
| Sample (N) | Estimated OCC: Yufu City ryokan N=99 properties / 1,181 rooms (based on listings on major booking sites; 100-101 properties for September stay dates), Oita ryokan N=230-231 properties / 3,659-3,664 rooms, Oita resort hotels N=32 properties / 1,492 rooms. Remaining inventory distribution: 10/10 N=64 properties, 10/11 N=75 properties, 10/12 N=80 properties. Estimated settled ADR: Yufu City ryokan N=117-129 properties (varying by month), Oita ryokan N=301 properties (October 2025). |
| Data as of | Data as of: September 28, 2026. Sales and inventory change daily, so the figures in this article are a snapshot as of the retrieval date. |
Source: Compiled by HotelBank Editorial Team from MetroEngines Research