

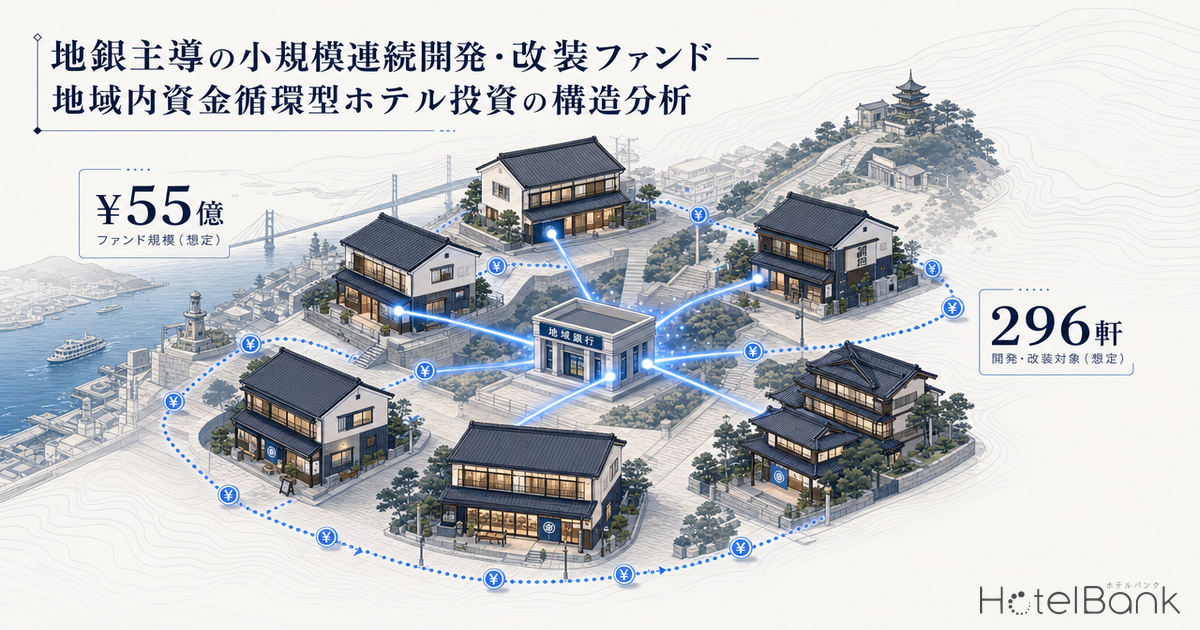
Between 2025 and 2026, a quiet structural shift is underway in the capital supply for regional hotels in Japan. Distinct from the “large single-asset acquisitions” historically led by listed REITs and foreign private equity (PE) firms, regional financial institutions are increasingly leading “small-scale, continuous development and renovation” funds. Examples include the JPY 5.5 billion fund jointly launched by Sumitomo Mitsui Trust Bank and Staple (based in Onomichi, Hiroshima), non-recourse loans for the renovation of Atami inns by Shimizu Bank and Yamanashi Chuo Bank, and dispersed-hotel funds for vacant-house renovation organized by the Ministry of Land, Infrastructure, Transport and Tourism (MLIT), the MINTO Organization, and regional banks. This article quantitatively examines the equity and debt supply structures of these intra-regional capital circulation schemes, comparing them with the large single-asset acquisition models of listed REITs and foreign PE. We back-calculate the conditions under which regional-bank non-recourse loans can be structured in an era of 1%-range interest rates using development scenarios, and verify the alignment between small-scale category dominance and fund formation using new supply data from MetroEngines Research.
Metric Definitions Used in This Article
- ADR (Average Daily Rate): Average of published rates on OTAs etc. Differs from actual transacted rates (in REIT disclosure comparisons, this tends to run +25-30% higher than transacted ADR). Rate per room (tax-included) for double-occupancy use, averaged across all plans (room-only to plans with meals).
- OCC (Occupancy): Ratio of sold rooms to total rooms in an area (estimate based on OTA sales inventory). Occupancy figures in this article’s scenario analysis are assumed values.
- LTV: Loan to Value (borrowing ratio against total investment). DSCR: Debt Service Coverage Ratio (annual operating gross profit / annual debt service). GOP: Gross Operating Profit. Non-Recourse Loan: A non-recourse facility where repayment is limited to cash flows from the underlying property.
- Data Source: MetroEngines Research & Consulting (new-opening data is based on OTA listing verification)
- — Regional bank-led small-scale, continuous development and renovation funds are emerging as a new capital supply layer that fills the JPY tens of millions to several hundred million per deal supply gap that listed REITs and foreign PE cannot reach.
- — The Sumitomo Mitsui Trust x Staple JPY 5.5 billion fund and non-recourse loans from Shimizu Bank and Yamanashi Chuo Bank for an Atami ryokan renovation are concrete examples of intra-regional capital circulation schemes.
- — Scenario analysis for a small ryokan renovation (20 rooms, JPY 600M total investment, 65% LTV) shows that with renovation-driven revenue uplift, DSCR remains around 1.8x even at 2.5% interest rates, and non-recourse financing is fully feasible.
- — The key to feasibility lies in securing equity buffer by keeping LTV at 60-65%, and intra-regional circulation models — which can readily supply local equity — hold a structural advantage.
- — Of the 641 new openings in 2026, the average is 37 rooms with vacation rentals at 296 properties (46%), showing pronounced small-scale dominance and high alignment with regional-bank fund continuous-development designs.
Large Single-Asset Acquisition vs Intra-Regional Capital Circulation — Structural Supply Differences
Hotel acquisitions by listed REITs and foreign PE typically take the form of “large, single-asset” deals of several billion to several tens of billions of yen per property. Hoshino Resorts REIT Investment Corporation (3287) operates 61 properties with an ADR of JPY 21,583 and an estimated occupancy of 79.3% as of April 2026 — a representative profile of a listed vehicle (source: monthly operational results of the same fund, industry benchmark references). While such models excel in liquidity and scale economies, small regional properties — fewer than 10 rooms, acquisition prices around JPY 100 million — are easily excluded from investment scope because per-deal transaction costs are not commensurate with returns. The acquisition white space that listed REITs cannot reach in regional Japan has been analyzed area-by-area in our separate report on REIT white space and supply-demand-tight regions.
In contrast, since 2025 a “small-scale, continuous development and renovation” fund model has been emerging. By January 2025, Sumitomo Mitsui Trust Bank and Staple had established the fund operating company “GOOD SOIL INC.”, building a two-layer development-and-long-term-holding structure that continuously launches multiple deals. According to the Nikkei (December 8, 2025), this regional-hotel-focused fund is sized at JPY 5.5 billion, with investments from JTB, Heiwa Real Estate, Gunma Bank, and Chugoku Bank. Notably, its design philosophy is to develop walking-distance clusters of small-scale assets — including restaurants and shops — into a continuous portfolio. Rather than supporting an isolated hotel, the fund supports area-level placemaking through capital.
Capital flows also differ structurally. In large single-asset acquisitions, equity comes from global institutional investors while senior loans come from major banks and foreign lenders — capital flows in from outside the region and returns outside the region. In intra-regional capital circulation, by contrast, regional banks and credit unions provide debt (non-recourse loans) while local companies, municipal-affiliated funds, and small-lot supporters provide equity, with rent, distributions, and employment retained within the region. The “Initiative for Sustainable Regional Development and Capital Circulation” announced by Sumitomo Mitsui Trust Bank in January 2025 explicitly articulates this intra-regional circulation philosophy. For regional banks, securing new managed assets in both real-estate debt and fund investments — at a time when traditional lending opportunities are shifting — is a strong incentive.
| Item | Large Single-Asset Acquisition (Listed REIT / Foreign PE) | Intra-Regional Capital Circulation (Regional Bank-Led Fund) |
|---|---|---|
| Deal Size | Several billion to tens of billions JPY | Tens of millions to several hundred million JPY (compounded through continuous deals) |
| Equity Supply | Institutional investors / foreign funds | Local firms / municipal-affiliated / small-lot investors |
| Debt Supply | Major banks / foreign senior loans | Regional bank and credit-union non-recourse loans |
| Target Properties | Large, prime location, established track record | Vacant houses, traditional kominka, small ryokan |
| Capital Return Destination | Outside the region (global) | Within the region (rent, employment, distributions) |
| Exit Strategy | REIT incorporation / large sale | Long-term holding fund / regional succession |
LTV, DSCR and Interest Rates of Regional-Bank Non-Recourse Loans — Back-Calculating Feasibility in the 1% Rate Era
How far can regional-bank non-recourse loans remain feasible in a rising rate environment? In April 2026, Shimizu Bank and Yamanashi Chuo Bank jointly extended a non-recourse loan to a private real estate fund formed by NBI Holdings, and the special purpose company (Godo Kaisha NBI Atami Investment) acquired the Atami ryokan “Atami Sanga” (source: Nikkei, April 7, 2026). The equity side is a typical structure backed by silent-partnership investments from an SBI Securities group company as investors. The decisive variables here are the balance of three elements: LTV (borrowing ratio), DSCR (debt service coverage ratio), and interest rate.
In real estate debt practice, a DSCR below 1.3x is considered thin in repayment headroom and an LTV above 90% raises concerns about price-decline risk; conversely, even with a somewhat lower DSCR, financing can be approved if the LTV is at or below 60% with sufficient equity (source: various real estate securitization commentaries). Accordingly, we assumed a small-scale ryokan renovation (20 rooms) and ran a sensitivity analysis varying ADR and occupancy to back-calculate DSCR. The table below summarizes MetroEngines Research’s estimates assuming JPY 600 million total investment, 65% LTV, and a 20-year repayment term.
| Scenario | ADR | Occupancy | Annual GOP | Gross Yield | DSCR at 1.5% | DSCR at 2.5% |
|---|---|---|---|---|---|---|
| Conservative | ¥25,000 | 65% | ¥35.6M | 5.9% | 1.57 | 1.43 |
| Base Case Assumed | ¥30,000 | 70% | ¥46.0M | 7.7% | 2.02 | 1.84 |
The takeaway from these estimates is that if renovation effectively lifts rates and occupancy, DSCR remains around 1.8x even at 2.5% interest, and non-recourse financing is fully feasible. By contrast, in the conservative case (ADR JPY 25,000, occupancy 65%), DSCR falls to 1.43x at 2.5% interest, approaching a level that may require additional equity cushion or a debt service reserve depending on the regional bank’s credit standards. In other words, feasibility hinges on lifting post-renovation profitability and keeping LTV in the 60-65% range to secure buffer. Because intra-regional capital circulation can more readily mobilize thicker equity from local firms and municipal-affiliated funds, it holds a structural advantage in securing this equity buffer. Renovation-driven revenue uplift represents a meaningful upside in regional banks’ business feasibility assessments. Current Cap Rate levels and their gap with NOI realities are examined in our separate market-wide yield environment analysis.
Dispersed Hotels — Per-Unit Investment Size, Yield Tiers, and the Consolidated Operations Model
Another pillar of intra-regional capital circulation is the “dispersed hotel” model, which converts vacant houses and traditional kominka into guest rooms. The MLIT, in partnership with regional banks, supports the creation of dispersed hotels through vacant-house renovation, and the management-type machizukuri funds organized by the MINTO Organization (Organization for Promotion of Urban Development) had reached 32 nationwide by March 2024 (source: Travel Voice, June 19, 2024). A representative example is the JPY 200 million “Ozu Machizukuri Fund” jointly organized by Iyo Bank and the MINTO Organization in 2020, where the renovated kominka cluster operates as the dispersed hotel “NIPPONIA HOTEL Ozu Castle Town”.
The investment profile of dispersed hotels is characterized by extremely small per-unit scale, with business viability emerging only when multiple buildings are bundled. We modeled a four-room traditional kominka unit and calculated yield tiers by investment scale. At JPY 120 million per unit with ADR JPY 30,000 and 60% occupancy, gross yield comes to 7.7%; with renovation-driven uplift at JPY 150 million per unit, ADR JPY 40,000, and 65% occupancy, yield reaches 8.9% — small in scale but with respectable returns. However, a single building cannot bear operating fixed costs alone, and a “consolidated operations contract model” — sharing front desk, reservations, and housekeeping across multiple buildings — is a prerequisite for sustainable yields.
(1) Single-Unit Tier
JPY 100-200M, yield 7-9%
4-room kominka scale. Bearing operating fixed costs alone yields thin returns. Consolidated operations are a prerequisite.
(2) Continuous Development / Consolidated Tier
JPY 500M-1.5B, multi-unit bundle
Sharing front desk, reservations, and housekeeping distributes fixed costs. Matches the Onomichi fund-style continuous development.
(3) Renovation Rate-Uplift Tier
Renovation lifts ADR +30%, occupancy +5pt
Atami ryokan renovation type. Revenue uplift drives up DSCR and strengthens resilience to rate hikes.
Supply Pipeline Analysis — Small-Scale Category Dominance and Alignment with Fund Formation
The properties targeted by intra-regional capital circulation funds are also growing in presence in actual new supply data. Within the scope tracked by MetroEngines Research (OTA listing verification basis), the 641 properties confirmed as new openings in 2026 average 37 rooms — small in scale — with vacation rentals standing out at 296 properties (46% of the total). They are followed by machiya at 24, cottages at 20, guest houses at 27, and hostels at 27, illustrating a structure in which small-scale, dispersed categories occupy the core of supply.
This small-scale dominance is not a single-year phenomenon. In 2024 there were 1,963 properties averaging 20 rooms, in 2025 1,617 properties averaging 25 rooms, and in 2026 641 properties averaging 37 rooms; vacation rentals consistently top the categories at 831 (2024), 666 (2025), and 296 (2026). Note that 2026 appearing below the prior year is due to the structural observation lead time — OTA listings typically appear only a few months before opening — not an actual decline in supply. The 2026 count is expected to rise as additional listings appear.
This dominance of small-scale, dispersed categories aligns well with regional-bank-led fund formation. Vacation rentals, machiya, and cottages all have small per-unit investment scales, and their starting point in vacant-house and kominka renovation aligns with the “continuous development” design of the MINTO Organization-style machizukuri funds and the Onomichi fund. Precisely because these are size brackets that listed REITs cannot capture, intra-regional capital circulation has substantial room to fill the supply gap through equity and debt. The more the quality of supply shifts toward small-scale and dispersed, the more the capital supply role of regional banks and credit unions stands to expand.
Summary — A New Capital Supply Layer Borne by Regional Finance
As we have seen, capital supply for regional hotels in Japan is bifurcating into two layers: “large single-asset acquisition” and “intra-regional capital circulation”. The former has strengths in liquidity and scale, while the latter fills the small-scale and dispersed supply gap that listed REITs and foreign PE cannot capture, through regional-bank non-recourse loans and local equity. The Sumitomo Mitsui Trust x Staple JPY 5.5 billion fund, Shimizu Bank and Yamanashi Chuo Bank’s Atami ryokan renovation financing, and MINTO Organization-style vacant-house renovation funds are concrete examples of this new layer.
Even in a rising rate environment, renovation-driven revenue uplift can secure a DSCR around 1.8x, and keeping LTV in the 60-65% range makes regional-bank non-recourse financing fully feasible. Dispersed hotels are supported by consolidated operations contracts, and the fact that 2026 new supply is dominated by small-scale categories — vacation rentals at 296 properties chief among them — provides a tailwind for such fund formation. For regional financial institutions, intra-regional capital circulation through real estate debt and fund investment is a promising growth opportunity amid shifting traditional lending environments. There remains substantial upside for credit officers in designing financing around post-renovation profitability and equity thickness.
Note: The scenario estimates in this article are simplified calculations based on public information and assumptions; actual investment decisions require detailed feasibility studies for each individual property. New-opening data is based on OTA listing verification, and because listings typically appear only a few months before opening, the most recent month and year may see property counts increase with future listings.
Related Reading
References & Sources
Data Sources
New-opening data from MetroEngines Research & Consulting (OTA listing verification basis, 2024:N=1,963 / 2025:N=1,617 / 2026:N=641 properties) serves as primary aggregation, supplemented by various media reports (Nikkei, Travel Voice), financial institution press releases, and public operational metrics from Hoshino Resorts REIT and Invincible Investment Corporation.
Estimation Assumptions
The DSCR sensitivity analysis assumes a 20-room small ryokan renovation with JPY 600M total investment, 65% LTV, 20-year repayment term, and 30% GOP margin, back-calculating annual debt service coverage by varying ADR, occupancy, and interest rate. The dispersed-hotel yield tier estimates assume a 4-room kominka and 35% GOP margin, with occupancy as an assumed (estimated) value.
Limitations & Caveats
The scenario estimates in this article are simplified calculations based on public information and assumptions; actual investment decisions require detailed feasibility studies for each individual property. New-opening data is OTA listing verification basis, and because listings typically appear only a few months before opening, the most recent month and year may see property counts increase with future listings. ADR is based on published sales prices and differs from transacted prices (transacted prices tend to be 25-30% lower).
Market Data
- MetroEngines Research & Consulting — New-opening data (OTA listing verification basis, 2024:N=1,963 / 2025:N=1,617 / 2026:N=641 properties), ADR and estimated occupancy
Fund & Financial Institution Reports
- Regional Community-Aligned Hotel Investment: Sumitomo Mitsui Trust et al. Form Fund for Small-Scale Continuous Development (Nikkei, December 8, 2025)
- [Hiroshima] Staple Targets Regional Revitalization with Real Estate Fund Jointly with Sumitomo Mitsui Trust (Nikkei)
- Sumitomo Mitsui Trust Bank and Staple Establish Investment Company “GOOD SOIL INC.” (Staple Inc. Press Release)
- Sumitomo Mitsui Trust Bank “Initiative for Sustainable Regional Development and Capital Circulation” (January 21, 2025)
- Shimizu Bank et al. Extend Non-Recourse Loan to Fund for Atami Ryokan Renovation (Nikkei, April 7, 2026)
Public Institutions & Machizukuri Funds
- MLIT Establishes Funds with Regional Banks, Creates Dispersed Hotels via Vacant-House Renovation (Travel Voice, June 19, 2024)
- Organization for Promotion of Urban Development (MINTO Organization) — Management-Type Machizukuri Fund Support
Investment Metrics, Construction Costs & REIT Benchmarks
- Hoshino Resorts REIT Investment Corporation “Monthly Operational Results, April 2026” (industry benchmark reference)
- Invincible Investment Corporation Portfolio (GOP margin actuals reference)
- Onomichi City Land Price Index (2025)