

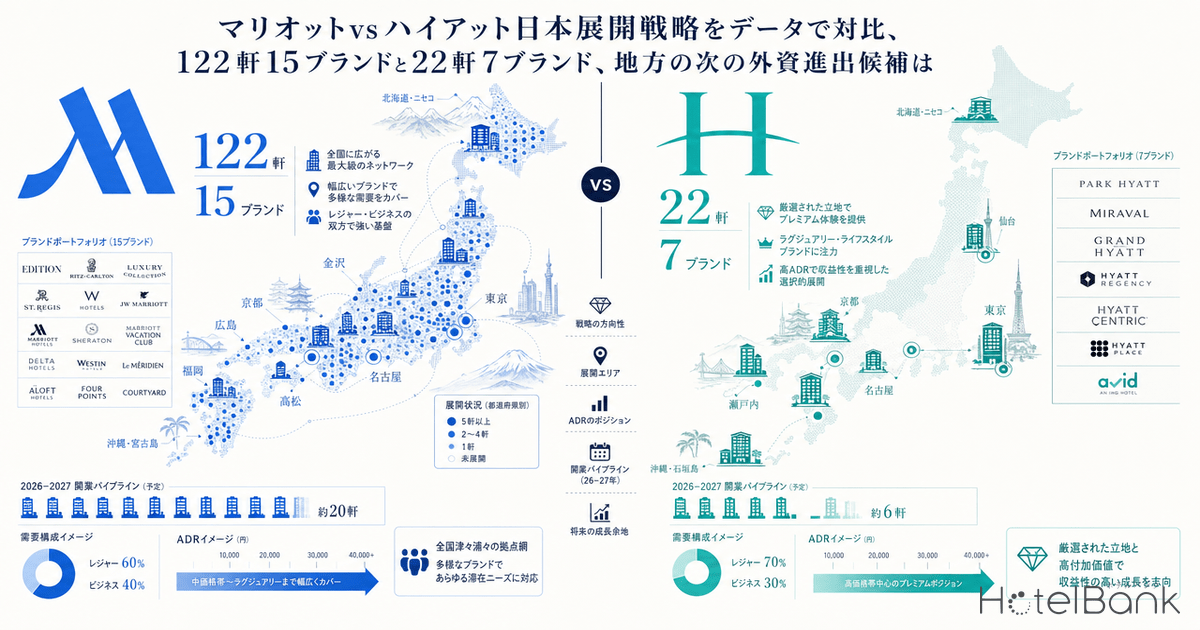

The opening of Conrad Nagoya in July 2026, marking the full-scale entry of Hilton’s flagship luxury brand into a regional ordinance-designated city beyond Tokyo, Osaka, and Kyoto, has drawn considerable attention. Yet the two giants of foreign hotel chains in Japan, Marriott International and Hyatt Hotels Corporation, are pursuing fundamentally different strategies to capture the Japanese market. Marriott has built an overwhelming footprint of 122 hotels across 15 brands, blanketing regional resort destinations nationwide, while Hyatt operates just 22 hotels across 7 brands. Despite the smaller scale, Hyatt’s average daily rate (ADR) actually exceeds Marriott’s in certain segments, reflecting a deliberately curated, premium-focused selection strategy.
This article compares the two chains’ brand-level ADR distribution, prefecture-level deployment density, and 2026-2027 opening pipeline based on publicly available pricing data from MetroEngines Research. Finally, we present what the data suggests are the most likely candidate areas for the next wave of regional luxury foreign-brand entries.
A 5.5x Scale Gap: Contrasting “Coverage” vs “Selectivity” Strategies
First, let us establish the overall picture. Within MetroEngines Research’s coverage, the currently operating hotel counts, prefectures of deployment, and total room counts for the two chains are as follows.
| Metric | Marriott | Hyatt | Gap |
|---|---|---|---|
| Operating hotels | 122 | 22 | 5.5x |
| Number of brands | 15 | 7 | 2.1x |
| Prefectures covered | 31 | 10 | 3.1x |
| Largest brand | Fairfield (33 hotels) | Hyatt Regency (8 hotels) | ― |
| Segment range | Select Service to Luxury | Upper Midscale to Luxury | ― |
Source: Compiled by HotelBank Editorial Team based on MetroEngines Research (as of April 2026)
Of Marriott’s 122 hotels, the largest single brand is Fairfield by Marriott with 33 properties. These have been deployed since 2020 through the “Trip Base” project jointly developed with Sekisui House, placing regional resort hotels alongside roadside stations (michi-no-eki) across Japan. This is followed by Sheraton (30 hotels), Courtyard (10), Westin (9), Ritz-Carlton (7), and Moxy (4). Hyatt’s portfolio, by contrast, consists of Hyatt Regency (8 hotels), Hyatt House (4), and Park Hyatt (3), with no presence in Japan of select-service brands equivalent to Fairfield or Moxy.
In other words, the strategic divergence can be summarized as “Marriott covers the surface, Hyatt picks the points.” Marriott uses Fairfield, a regional roadside-focused brand, to extend reach into smaller cities and onsen towns, while Hyatt limits itself to prime metropolitan locations, narrows its brand portfolio, and maintains a higher rate band.
Brand-Level ADR: The Apex Belongs to Park Hyatt, Not Marriott
Next, we compare the two chains’ brand-level ADR (April 2026, per-room rate based on double occupancy, tax-inclusive).
Source: Compiled by HotelBank Editorial Team based on MetroEngines Research
The result was unexpected. The highest ADR is held neither by Marriott’s “Edition” (¥243,600, N=2 hotels) nor by Ritz-Carlton (¥213,200, N=7 hotels), but by Hyatt’s “Park Hyatt” at ¥315,700 (N=3 hotels). Hyatt’s “Andaz” also stands at ¥213,100 (N=1 hotel), comparable to Ritz-Carlton, while “Grand Hyatt” maintains a solid ¥167,500 (N=2 hotels) in the high-rate tier.
The average ADR across Hyatt’s 6 luxury-tier hotels comes to ¥211,500, versus ¥195,900 for Marriott’s 12 luxury-tier hotels. With less than half the hotel count, Hyatt secures an 8% premium in the upper tier. In the upper-midscale volume zone too, Marriott’s 74 hotels average ¥48,100 while Hyatt’s 3 hotels (Hyatt Place and Hyatt House) average ¥64,000, putting Hyatt approximately 33% higher.
Source: Compiled by HotelBank Editorial Team based on MetroEngines Research
The clear divergence appears at the lower end of the brand range. Marriott has Fairfield at ¥17,100 (N=31 hotels) and Moxy at ¥30,000 (N=4 hotels) in the mid-to-economy tier, and these form the foundation supporting its 122-hotel scale. Hyatt has no equivalent segment, with its lowest-priced brand stopping at Hyatt House (¥58,500).
This suggests Hyatt has deliberately refrained from bringing its lower-tier brands into the Japanese market. Mark Hoplamazian, CEO of the U.S. parent company, described the global 148,000-room development pipeline at the early-2026 earnings announcement as “luxury and lifestyle-centric,” and this strategy appears to extend to the Japanese market as well.
Major-City ADR: Hyatt 20% Cheaper in Kyoto, 20% More Expensive in Tokyo
When we line up the two chains’ ADR by major city, position varies significantly by location.

Source: Compiled by HotelBank Editorial Team based on MetroEngines Research
Source: Compiled by HotelBank Editorial Team based on MetroEngines Research
| Prefecture | Marriott ADR | Marriott hotels | Hyatt ADR | Hyatt hotels | Price gap |
|---|---|---|---|---|---|
| Tokyo | ¥147,700 | 16 | ¥172,400 | 7 | +17% |
| Kyoto | ¥128,000 | 9 | ¥109,100 | 3 | −15% |
| Osaka | ¥65,700 | 16 | ― | 0 | ― |
| Okinawa | ¥157,400 | 1 | ¥122,900 | 2 | −22% |
| Fukuoka | ¥102,400 | 3 | ¥107,500 | 1 | +5% |
| Kanagawa | ¥66,900 | 3 | ¥50,600 | 2 | −24% |
| Hokkaido | ¥25,800 | 9 | ¥93,600 | 1 | +263% |
Source: Compiled by HotelBank Editorial Team based on MetroEngines Research (April 2026, N=22,580 samples)
In Tokyo, the average ADR of Hyatt’s 7 hotels exceeds Marriott’s 16 hotels by approximately 17%. This stems from a compositional difference: Hyatt concentrates ultra-premium brands such as Park Hyatt Tokyo (Shinjuku), Andaz Tokyo (Toranomon), and Grand Hyatt Tokyo (Roppongi), while Marriott’s Tokyo lineup mixes mid-tier brands like Courtyard and AC Hotels.
Conversely, in Kyoto, Okinawa, and Kanagawa (Yokohama and Hakone), Marriott surpasses Hyatt. In Kyoto, the presence of JW Marriott Hotel Nara (technically in a neighboring prefecture but within the Kyoto metropolitan zone) and Ritz-Carlton Kyoto pulls the average up. In Okinawa, resort brands such as Okinawa Marriott Resort & Spa drive rates above Hyatt’s two properties.
In Hokkaido, the average ADR of Marriott’s 9 hotels (Fairfield, Courtyard, etc.) sits at just ¥25,800, whereas Hyatt’s single property, represented by Hyatt Regency Ishigaki, records ¥93,600. This case most starkly demonstrates the strategic divergence: “Marriott covers the regions through volume, Hyatt extracts high rates from a few strategic points.”
Deployment Density Map: Hyatt’s 37 Untouched Prefectures Are a Vast White Space
Aggregating hotel counts by prefecture reveals dramatic differences in deployment density. Marriott covers 31 of Japan’s 47 prefectures, while Hyatt is limited to just 10.
Source: Compiled by HotelBank Editorial Team based on MetroEngines Research (as of April 2026)
The 10 prefectures where Hyatt operates consist of Tokyo (7 hotels), Hokkaido (3), Kyoto (3), Fukuoka (2), Okinawa (2), Kanagawa (2), Ishikawa (2), and Chiba (1). Notably, Hyatt has no operating property in Osaka at present (Hyatt Regency Osaka, which previously existed, exited in December 2024).
Marriott, by contrast, extends reach into Tohoku (Miyagi, Iwate, Yamagata), Chugoku and Shikoku (Okayama, Hiroshima), and southern Kyushu (Kumamoto, Kagoshima, Miyazaki, Saga, Nagasaki). This wide distribution reflects the fact that many of Fairfield’s 33 properties are sited in smaller cities and onsen towns with populations below 200,000.
Among Hyatt’s “37 untouched prefectures,” areas where the foundations for foreign-brand luxury entry appear to be falling into place — judging from population, tourist inflow, and existing hotel rate levels — are presented in the next section.
2026-2027 Pipeline: Both Chains Focus on Osaka, Sapporo, and Hiroshima
Compiling publicly disclosed opening plans, clear focal areas emerge in both chains’ 2026-2027 pipelines.

Source: Compiled by HotelBank Editorial Team based on MetroEngines Co., Ltd.
| Opening | Property | Location | Rooms | Brand tier |
|---|---|---|---|---|
| Marriott | ||||
| April 2026 | Sugata Hotel Osaka Shinsaibashi (Series by Marriott) | Osaka | 256 | Upper Midscale (Japan first) |
| May 2026 | Hamamatsu Marriott Hotel | Shizuoka | 236 | Upper Midscale |
| June 2026 | Courtyard by Marriott Kobe | Hyogo | ― | Upper Midscale |
| August 2026 | Courtyard by Marriott Shin-Yokohama | Kanagawa | ― | Upper Midscale |
| Fall 2026 | HOTEL THE MITSUI HAKONE (Luxury Collection) | Kanagawa | ― | Luxury |
| Within 2026 | Osaka Marriott Hotel Bayside Tower | Osaka | 829 | Upper Midscale |
| Within 2026 | City Express by Marriott Osaka Namba South / Shin-Imamiya | Osaka | ― | Select Service (Asia first) |
| Q1 2027 | Hiroshima Marriott Hotel | Hiroshima | 183 | Upper Midscale |
| Q1 2027 | Kokura (Kitakyushu) Marriott | Fukuoka | 90 | ― |
| Hyatt | ||||
| June 2026 | Hyatt Centric Sapporo | Hokkaido | 216 | Premium |
| Within 2027 | Andaz Hiroshima | Hiroshima | 235 | Luxury (Hiroshima’s first foreign-brand luxury) |
| Planned 2029 | Park Hyatt Sapporo (Odori Park) | Hokkaido | ― | Luxury |
Source: Compiled by HotelBank Editorial Team from Marriott International, Hyatt Hotels Corporation, NTT Urban Development and partners’ IR materials and press releases
Marriott is set to deploy seven properties totaling roughly 1,500 rooms within 2026 alone. Particularly notable is the simultaneous launch of two Asia/Japan-first brands in Osaka — “Series by Marriott” and “City Express by Marriott.” This represents a strategy to capture share in the mid-tier segment, where competing Hilton lacks brands such as True Hotels or Motto, leveraging demand from the 2025 Kansai Expo.
Hyatt’s pipeline, by contrast, is quantitatively modest with three domestic properties between 2026 and 2029, but every single one is positioned at “Hyatt Regency or above.” The lineup of Hyatt Centric Sapporo (Premium), Andaz Hiroshima (Luxury), and Park Hyatt Sapporo (top-tier Luxury) shows clear concentration on upper-tier brands. Andaz Hiroshima will be both Hyatt’s first property in Hiroshima Prefecture and the first foreign-brand luxury hotel in the prefecture, making it a symbolic case of regional luxury foreign-brand entry in 2027.
Investment Implications: Where Is the “Next Regional Luxury” After Conrad Nagoya?
Building on the July 2026 opening of Conrad Nagoya and the 2027 opening of Andaz Hiroshima, we estimate which regional cities are most likely to be the next foreign-brand luxury destinations, based on three quantitative criteria.
| Criterion | Indicator |
|---|---|
| (1) Demand foundation | Prefecture ADR ¥30,000+, meaningful inbound share, presence of redevelopment plans |
| (2) No foreign-brand presence | Hyatt absent, no existing Ritz-Carlton/Conrad/Four Seasons-class luxury |
| (3) City functions | International conference facilities, large-scale commercial, international airport access (within 90 minutes) |
Key indicators for each candidate area are as follows.
Source: Compiled by HotelBank Editorial Team based on MetroEngines Research (April 2026, ADR for major regional prefectures)
| Candidate area | Prefecture ADR | Marriott | Hyatt | Likelihood |
|---|---|---|---|---|
| Shizuoka (Hamamatsu, Izu) | ¥42,800 | Izu Shuzenji, Hamamatsu (May 2026) | Not present | Medium (resort type) |
| Nagano (Karuizawa, Matsumoto) | ¥40,900 | Karuizawa, Hakuba | Not present | High (resort luxury) |
| Ishikawa (Kanazawa) | ¥39,300 | Not present | 2 existing (incl. Hyatt Centric) | High (room for Marriott entry) |
| Hiroshima | ¥33,100 | 2027 Hiroshima Marriott planned | 2027 Andaz planned | Confirmed |
| Okayama | ¥32,700 | Hiruzen, Tsuyama (Fairfield) | Not present | Low |
| Kumamoto (Aso) | ¥31,400 | Aso (Fairfield) | Not present | Low to Medium (resort only) |
Source: Compiled by HotelBank Editorial Team based on MetroEngines Research
The data points to two strong “next regional luxury” candidates: Nagano (resort luxury around Karuizawa) and Kanazawa in Ishikawa (an opening for Marriott entry). Nagano’s prefectural ADR of ¥40,900 ranks second among major regional prefectures, and although Karuizawa Marriott Hotel already exists, no Ritz-Carlton or JW Marriott-class property has yet opened. With excellent access (70 minutes from Tokyo by Shinkansen), the existence of legacy resorts such as Karuizawa Prince Hotel, and an established affluent demand base, a luxury resort in the vein of “Karuizawa Ritz-Carlton Reserve” looks like the most reasonable next form of entry.
In Kanazawa, Marriott’s luxury segment (e.g., a hypothetical Ritz-Carlton Kanazawa) sits as a white space against the existing Hyatt Centric Kanazawa and Hyatt House Kanazawa. Since the Hokuriku Shinkansen extension to Tsuruga (2024), access from the Kansai region has improved. Combined with redevelopment plans around Omicho Market and Kenrokuen Garden, full-scale entry from 2028 onward is anticipated.
By contrast, regional ordinance-designated cities such as Okayama, Kumamoto, and Sendai (Miyagi) — where ADR remains around ¥30,000 — still face challenging conditions for sustaining luxury hotel profitability. For these areas, “Courtyard” or “Hyatt Centric”-class upper-midscale to premium brand entry would be more realistic.
Summary: Marriott’s Scale, Hyatt’s Selectivity
Marriott pursues an overwhelming “coverage strategy” with 122 hotels across 15 brands and 31 prefectures, using Fairfield as a regional roadside-type weapon to channel loyalty members into regional markets devoid of foreign hotel brands. Hyatt, in turn, executes a thorough “point strategy” with 22 hotels across 7 brands and 10 prefectures, deploying only upper-tier brands such as Park Hyatt, Andaz, and Grand Hyatt at the most prime metropolitan locations to achieve an average ADR exceeding Marriott’s luxury tier.
Looking at the 2026-2029 pipeline, Marriott continues mid-to-lower tier expansion through new brands like “Series” and “City Express,” while Hyatt focuses on a luxury breakthrough with Andaz Hiroshima and Park Hyatt Sapporo. The two strategies are unlikely to converge going forward; each is more likely to deepen the market position it has chosen.
For the next regional luxury entry candidates, Karuizawa (Nagano) and Kanazawa (Ishikawa) stand out from the standpoint of ADR levels, demand foundations, and existing hotel composition. The third wave following Conrad Nagoya (2026) and Andaz Hiroshima (2027) may well begin in these regional resort cities.
Supplement: Who Actually “Owns” These Hotels — Foreign-Brand Hotel Ownership Structure in Japan
Both Marriott and Hyatt act only as “operators” in Japan, with management contracts in which the “ownership” of the real estate is held by Japanese companies. In other words, while the brand sign is foreign, the risk and return on the building and land are borne by Japanese real estate developers and REITs. Understanding this ownership structure helps explain why specific brands cluster in specific areas.
Major Hyatt property owners:
| Property | Owner | Owner type |
|---|---|---|
| Park Hyatt Tokyo | Tokyo Gas Urban Development | Operating company (Shinjuku Park Tower) |
| Grand Hyatt Tokyo | Mori Building | Developer (Roppongi Hills) |
| Andaz Tokyo | Mori Building | Developer (Toranomon Hills) |
| Hyatt Regency Tokyo | Odakyu Electric Railway | Railway and real estate |
| Hyatt Regency Kyoto | Sekisui House | Developer |
| Hyatt Regency Naha / Seragaki | Tokyo Tatemono | Developer |
| Hyatt Regency Yokohama | Ken Corporation | Real estate |
| Hyatt House Kanazawa | Tokyo Tatemono | Developer |
| Park Hyatt Niseko | PCPD (Hong Kong-based developer) | Foreign developer |
Major Marriott property owners:
| Property | Owner | Owner type |
|---|---|---|
| The Ritz-Carlton, Tokyo | Mitsui Fudosan | Developer (Tokyo Midtown) |
| The Ritz-Carlton, Kyoto | Sekisui House | Developer |
| The Ritz-Carlton, Nikko | Tobu Railway | Railway and real estate |
| The Ritz-Carlton, Okinawa | Mori Trust | Developer / REIT |
| The Ritz-Carlton, Fukuoka | Sekisui House | Developer (Daimyo Garden City) |
| The Tokyo EDITION, Toranomon | Mori Building | Developer (Toranomon-Azabudai project) |
| JW Marriott Hotel Nara | Mori Trust | Developer |
| The St. Regis Osaka | Sekisui House | Developer |
| W Osaka | Sekisui House | Developer |
| The Westin Tokyo | Sapporo Real Estate | Operating company (Yebisu Garden Place) |
| Sheraton Miyako Hotel Tokyo | Kintetsu Group | Railway and real estate (own and operate) |
| Fairfield (33 hotels) | Sekisui House | Developer (Trip Base project) |
Owner-level holdings:
| Owner | Hotels held | Brand examples |
|---|---|---|
| Sekisui House | 40+ hotels (incl. 33 Fairfield) | Ritz-Carlton Kyoto/Fukuoka, St. Regis Osaka, W Osaka, HR Kyoto, nationwide Fairfield |
| Mori Building | 3 | Grand Hyatt Tokyo, Andaz Tokyo, EDITION Toranomon |
| Tokyo Tatemono | 3 | HR Naha, HR Seragaki, Hyatt House Kanazawa |
| Mori Trust | 2 | Ritz-Carlton Okinawa, JW Marriott Nara |
| Mitsui Fudosan | 2 | Ritz-Carlton Tokyo, Courtyard Tokyo Station |
Sekisui House stands out by a wide margin. In addition to the 33 Fairfield “Trip Base” properties, it owns Ritz-Carlton Kyoto and Fukuoka, The St. Regis Osaka, W Osaka, and Hyatt Regency Kyoto, holding luxury-tier properties of both Marriott and Hyatt. It is one of Japan’s largest foreign-brand hotel owners. Mori Building, by contrast, concentrates two Hyatt properties and one Marriott property in its self-developed Toranomon and Roppongi areas, executing a distinctive “urban development x hotel brand” strategy.
Source: Compiled by HotelBank Editorial Team based on each company’s IR materials, securities reports, and media reports (as of April 2026). Ownership may shift through inter-REIT transactions and similar transactions.
References
- Japan Tourism Agency, Accommodation Travel Statistics Survey
- Marriott International News Releases
- Hyatt Hotels Corporation Press Releases
Data Sources and References
| Source | Content | URL |
|---|---|---|
| MetroEngines Research | OTA pricing data (ADR, hotel counts, brand classification). Per-room rates for double occupancy (tax-inclusive), all-plan averages. | — |
| Hyatt Q4 2025 Earnings | 148,000-room pipeline, luxury and lifestyle-centric strategy (Mark Hoplamazian, CEO) | Hyatt official / Hotel Management |
| Sekisui House Trip Base | Fairfield by Marriott michi-no-eki project | Trip Base official / Fairfield official |
| Hyatt Centric Sapporo | 216 rooms, scheduled to open Fall 2026 | Hyatt official / Monthly Hoteres |
| Conrad Nagoya | 170 rooms, scheduled to open July 31, 2026 | Hilton PR TIMES |
| Park Hyatt Niseko | Developed by PCPD (Pacific Century Premium Developments) | PCPD official / Developer info |
| Ritz-Carlton Kyoto | Developed and owned by Sekisui House | Sekisui House case study |
| Ritz-Carlton Fukuoka | Within Daimyo Garden City, developed by Sekisui House and partners | Sekisui House official / Marriott PR TIMES |
| W Osaka | Developed and owned by Sekisui House, design supervised by Tadao Ando | Sekisui House case study |
| Grand Hyatt Tokyo | Within Roppongi Hills, operated by Mori Building Hospitality Corporation | Roppongi Hills official |
| Marriott International | Japan official site and news releases | Japan official / Newsroom |
| Hyatt Hotels | Japan official site and newsroom | Japan official / Newsroom |
| Japan Tourism Agency | Accommodation Travel Statistics Survey | mlit.go.jp |
*ADR figures in this article represent average list prices published on OTAs and similar channels and may differ from actual transacted rates. Ownership information is based on each company’s IR materials, securities reports, and media reports, and may shift through inter-REIT transactions. Data as of April 2026.