

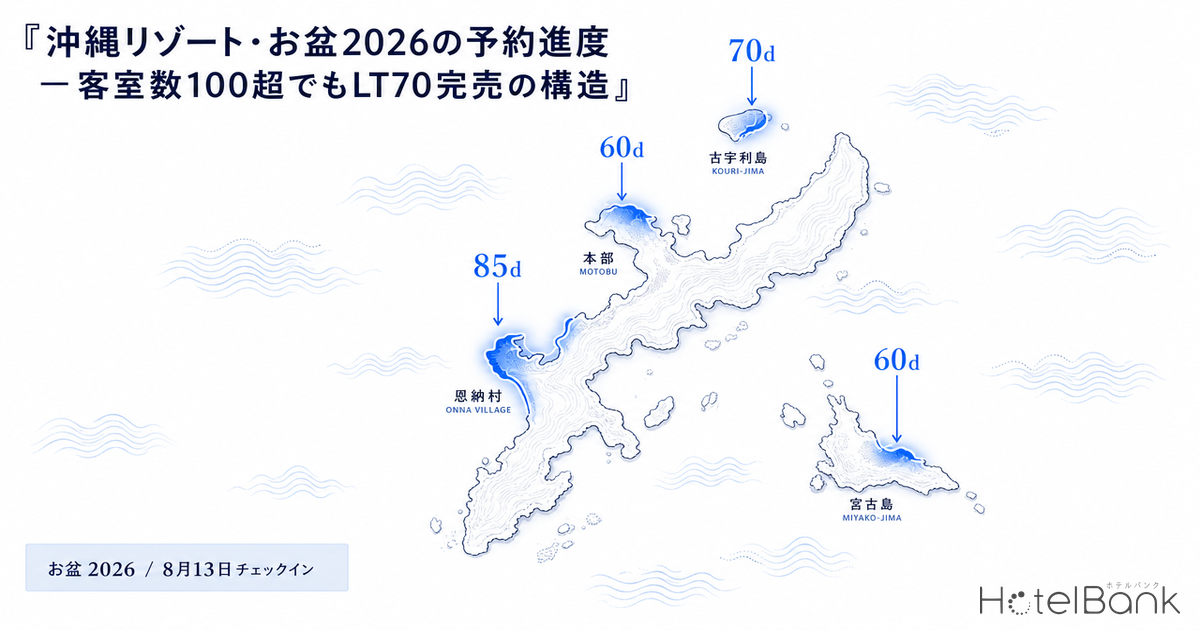
For Okinawa resort hotels with a Thursday, August 13, 2026 check-in, we read booking pace from lead-time (LT, days until check-in) trends using inventory data tracked by MetroEngines Research. Even at the peak of the Obon holiday, large properties have moved fastest — a 67-room mid-tier resort in Miyakojima tightened its online inventory window roughly three weeks after LT90, with observation-based signs of supply-demand tightening. This article starts with a population of 111 resort hotels in Okinawa Prefecture (limited to properties whose OTA-published inventory represents 30% or more of total rooms) and examines how mid-sized and larger properties are narrowing inventory, cross-referencing competitive density and ADR tiers across Miyakojima, Onna Village, and central Okinawa Main Island.
Metric Definitions Used in This Article
- ADR (Average Daily Rate): Average of selling prices published on OTAs and similar channels. Differs from actual transaction prices. Per-room rate for double occupancy (tax included), averaged across all plans (room-only through meal-inclusive).
- OCC (Occupancy Rate): Share of sold rooms relative to total rooms in the area (estimated based on OTA sales inventory).
- LT (Lead Time): Days until check-in. LT0 = day of check-in.
- Early Sellout LT: The lead time at which remaining rooms first reach zero (a larger value means earlier sellout).
- Data Source: MetroEngines Research
- — A 67-room mid-tier resort in Miyakojima was observed to sell out once for the August 13 Obon check-in within three weeks between LT90 and LT70. Inventory absorption speed at mid-sized properties is structurally accelerating.
- — At LT60, remaining rooms across Okinawa Prefecture resorts stood at 4,787 rooms (−18.8% vs. LT90); supply-demand for the resort category as a whole is gradually tightening.
- — Okinawa Prefecture’s average August ADR reached ¥36,587 (YoY +10.5%) — the highest level in 18 months. Demand pressure is also flowing through to rates.
- — The 67-room property under observation eased its online inventory window after the LT70 sellout, returning inventory to reach an occupancy rate of 59.7% (as of June 2026). Implementation of supply-demand control is observable.
- — From competitive density and ADR tiers in Miyakojima, Onna Village, and central Okinawa Main Island, the mid-scale resort (50–100 rooms) range suggests opportunities for new market entry and operational efficiency gains.
August 13 Obon Check-in: Population and Area-Wide Booking Pace
We start by establishing the overall movement of Okinawa Prefecture’s resort category. For the Thursday, August 13, 2026 check-in, MetroEngines Research tracks 473 resort hotels in Okinawa Prefecture. Of these, 231 properties have observable OTA data, and narrowing further to those satisfying the condition of “OTA-published inventory at 30% or more of total rooms” yields 111 properties. We limit the population to the 30%-plus group because properties with small OTA windows make it structurally difficult to read booking pace from inventory movements; this article analyzes the resulting 111 properties.
For the area-wide resort category (228 properties / 25,126 rooms in Okinawa Prefecture, observation basis), remaining rooms stood at roughly 5,892 at LT90 and 4,787 at LT60, meaning about 1,100 rooms (approximately 18.8% of observed published inventory) were absorbed over three weeks. Okinawa Prefecture’s average resort ADR has trended around the ¥63,000 range, with ADR holding nearly flat even amid strong demand. Within the price band of the peak Obon period, levels are already close to a ceiling for upside.
Source: MetroEngines Research & Consulting (August 13, 2026 check-in, Okinawa Prefecture resort category 228 properties / 25,126 rooms)
Looking by category, the luxury band (ADR ¥100,000 and above, 110 properties / 7,420 rooms) shows a similar pace, with roughly 260 rooms (25.5%) absorbed between LT90 and LT60. Pricing barely moved from the LT90 level of ¥153,100. Across the full set (1,007 properties / 51,929 rooms, including business through ryokan), remaining inventory at LT60 still stood at 14,721 rooms — a thick buffer thanks to the larger denominator — but the pace within the resort and luxury bands stands out.
Booking Pace Ranking — A Structure Where Even 100+ Room Properties Hit First-Time LT70 Sellouts
Ordering the 111 properties by Early Sellout LT (the lead time at which remaining rooms first hit zero), the top ranks are mostly occupied by small-scale villas and condominiums with 1–10 rooms. That is as expected — properties that operate as whole-building rentals on peak dates lose their inventory window early. What deserves attention, however, is that a mid-tier resort of around 67 rooms recorded a zero-remaining-rooms observation at LT70, a very long lead time. Among the 111-property population, only one property simultaneously satisfies both “30 or more rooms” and “Early Sellout LT of 60 or greater” — a structurally rare movement.
| Rank | Property | Total Rooms | Early Sellout LT | Days Sold Out | Current Remaining Rate |
|---|---|---|---|---|---|
| 1 | Sunline Chatan Condominium Resort (サンライン北谷コンドミニアムリゾート) | 1 room | LT90 | 26 days | 0.0% |
| 2 | Petit Resort Kouri Island (プチリゾート古宇利島) | 3 rooms | LT89 | 6 days | 66.7% |
| 3 | Naata Beach Villa (ナータビーチヴィラ) | 10 rooms | LT74 | 3 days | 10.0% |
| 4 | UMI THE K Kouri Island (UMI THE K 古宇利島) | 3 rooms | LT72 | 11 days | 0.0% |
| 5 | Hotel California Miyakojima Resort (ホテルカリフォルニア宮古島リゾート) | 67 rooms | LT70 | 2 days | 40.3% |
| 6 | JUSANDI | 5 rooms | LT66 | 7 days | 0.0% |
| 7 | MIHANA Onna Village (MIHANA 恩納村) | 5 rooms | LT62 | — | 0.0% |
*Population = 111 properties in the Okinawa Prefecture resort category satisfying “OTA-published inventory at 30% or more of total rooms” (of 473 resort properties in the prefecture, 231 have observation data, and 111 of those satisfy the 30% condition). Source: MetroEngines Research.
The fifth-ranked Miyakojima mid-tier resort (67 rooms) differs in room scale by an order of magnitude from the other top-ranked properties. Properties with 1–10 rooms can sell out instantly with a single reservation or a single building rental, so even a high Early Sellout LT carries limited implication for the broader market. By contrast, a 67-room property reaching zero remaining rooms at LT70 (73 days before check-in) indicates that, on a room-count basis, demand absorption is concentrating intensively in a short window.
Case Observation — LT Trajectory of a 67-Room Resort, Step-Down and Inventory Release
Examining the LT trajectory of this 67-room Miyakojima mid-tier resort at each observation point, an interesting step structure emerges. At LT90 (the initial observation on May 15), remaining rooms stood at 40 and estimated occupancy at 40.3%. From there through LT80, absorption proceeded slowly at about one room per day, with 36 remaining at LT80. But at LT79 (May 26), remaining rooms suddenly dropped to one, and at LT70 (June 4) the zero-remaining-rooms observation finally occurred. Calculated, this means 40 rooms were absorbed down to zero over three weeks.
What deserves attention is that at LT67 (June 7), remaining rooms rebounded to 31. The size of this rebound (5+ rooms, sustained for 3+ days) is too large for a one-off cancellation cycle and is presumed to reflect the hotel releasing additional OTA inventory. Heading into the run-up to the Obon peak, the property appears to have stepped its window open one notch from the initial tightening — a suggestive observation from a supply-demand control standpoint. As of LT59 (June 15), at the time of writing, remaining rooms stand at 27 and occupancy has returned to 59.7% (same basis).
Source: MetroEngines Research & Consulting (31-day observation window, May 15 to June 15, 2026)
This movement should be read not just as the snapshot fact that the property “sold out at LT70” but as a booking-pace structure that includes the subsequent inventory release. Given that check-in is still 30+ days out (58 days at time of writing), it is premature to conclude that the property will remain sold out from here; we need to keep watching how the cycle of additional releases and re-absorption plays out between LT30 and LT60. That said, the fact that large-scale absorption occurred at the early LT90–70 stage is a meaningful signal that Obon demand at this property is strong.
Miyakojima’s Competitive Density and ADR Tiers
To understand what is happening in Miyakojima, we mapped competitive density within a 5 km radius centered on the 67-room resort. The radius contains 200 hotels with 3,219 total rooms (the range MetroEngines Research tracks, including villas, detached villa units, and condominiums). This scale is comparable to the resort area of central Okinawa Main Island and shows that Miyakojima is not merely a remote island but a meaningful hotel cluster.
Ordering the 12 mid-to-large hotels with 50 or more rooms by ADR (August 13, 2026 check-in) reveals a clear three-tier structure. The top ¥100,000 band is occupied solely by Hilton Okinawa Miyakojima Resort (329 rooms). The ¥40,000 band consists of two mid-tier resorts — Palm Springs Miyakojima Resort (53 rooms) and the 67-room resort that is the focus of this article. The remaining 8 properties cluster in the ¥15,000–¥35,000 mid-to-economy band.
Source: MetroEngines Research & Consulting (within 5 km radius, 50 or more rooms, August 13, 2026 check-in)
What stands out in this structure is the room-scale gap between Hilton (329 rooms) and the mid-tier resort group (50–67 rooms). Resorts in the 100–250 room range with ADR in the ¥40,000–¥70,000 band are effectively absent within the 5 km radius of Miyakojima’s central commercial area (city center to Shimozato district), creating a supply vacuum. Given the strength of area demand and the situation where 50–70 room mid-tier resorts are recording zero remaining rooms at LT70, this suggests that mid-scale, mid-priced room demand may not be fully absorbed by current supply.
Furthermore, while Okinawa Prefecture’s overall resort category average ADR is ¥50,500 (271 properties), the two Miyakojima mid-tier properties have been operating below that in the ¥40,000 band. Early absorption of room occupancy indicates that the balance between price band and location is matching market needs; with phased price adjustments and plan-mix revisions tuned to demand, this range can also be viewed as a band carrying further revenue opportunities.
Okinawa Prefecture’s Obon Demand — Direction Shown by 18 Months of ADR Trends
Tracing 24 months of Okinawa Prefecture’s overall ADR shows growth of +10.5% year-over-year, from ¥33,100 in August 2025 to a projected ¥36,600 for August 2026. This growth rate sits behind only Kyoto (+29.9%) and Hokkaido (+12.9%), pointing to an upward price-band shift heading into the Obon peak season. On a monthly basis, July 2026 (¥33,400) and August 2026 (¥36,600) trace a seasonally-driven rising curve.
Source: MetroEngines Research & Consulting (Okinawa Prefecture all-category average, monthly sample 1,596–1,805 properties)
One caveat: the ADR shown here is the average of OTA-published list prices and represents a snapshot at the time of observation. For August Obon prices, plans currently priced high may be discounted late and revise downward, or, conversely, as remaining rooms dry up, the mix may shift toward higher-priced plans and revise further upward. Our booking-pace observations should be positioned as a hint for reading the direction of those shifts.
Reading the Structure — Opportunities Emerging for Mid-Scale Resorts
Several structural points surface from the booking-pace observations in this article. First, for Okinawa resorts with August 13 Obon check-in, a 67-room mid-tier property recorded an LT70 sellout once within three weeks of the initial observation, and after a subsequent inventory release settled at an occupancy rate of 59.7% (as of June 2026, MetroEngines inventory observation). For this to happen at a timing more than 30 days out is evidence that demand is concentrating early relative to supply.
Second, while Miyakojima’s competitive density is high at 200 properties / 3,219 rooms within a 5 km radius, the ADR tier shows that resorts in the 100–250 room / ¥40,000–¥70,000 band are thin, creating a supply vacuum in the mid-scale, mid-priced segment. The mid-tier resort that demonstrated early sellout was operating exactly at the edge of this vacuum — suggesting the market has room to absorb additional mid-scale resort supply.
Third, in an environment where Okinawa Prefecture’s overall August Obon ADR is rising +10.5% YoY, area-wide demand is reliably building. While the resort category average ADR trends at ¥50,500, properties that built occupancy early at a more accessible ¥40,000 level retain upside as brands that engineer the balance between price and demand. The next key to reading the direction of Obon 2026 for Okinawa resorts as a whole will be the LT30–60 inventory trajectory, particularly how the cycle of additional inventory releases and re-absorption plays out in the near-in window.
⚠ Note on Future-Dated ADR: ADR figures in this article are averages of selling prices published on OTAs at the time of observation and fluctuate as the check-in date approaches. Prices currently set high may decline through late discounting, or conversely, may revise upward as the mix shifts with declining remaining inventory. Please keep both possibilities in mind.
References and Sources
■ Data Sources
OTA-published price and remaining-inventory observation data (MetroEngines Research & Consulting, continuous observation late May to June 15, 2026, target = 111 Okinawa Prefecture resort hotels, population = properties with OTA-published inventory at 30% or more of total rooms); Japan Tourism Agency Accommodation Travel Statistics; JNTO inbound tourist statistics.
■ Calculation Assumptions
Occupancy rate is estimated from OTA-published inventory utilization (remaining / published). LT (lead time) is days until check-in, measured from Thursday, August 13. ADR trends use Okinawa Prefecture all-category averages; year-over-year comparisons are same-month comparisons.
■ Limitations and Caveats
As the data is OTA-published-inventory-based, group, direct-sales, and group-member inventory is not reflected. Occupancy is an estimate and may differ from actuals. The LT70 sellout observation indicates “a single instance of inventory depletion”; subsequent inventory release reflects operator judgment.
- MetroEngines Research & Consulting — OTA-published pricing data, remaining-inventory observation data, estimated occupancy (OCC), booking curve analysis
- Japan Tourism Agency “Accommodation Travel Survey” (reference: Obon-period demand environment)
- JNTO “Statistics of Inbound Visitors” (reference: international flight demand to Okinawa Prefecture)