


*Prices are per-room rates (tax included) for double occupancy. Data is aggregated from publicly listed OTA prices.
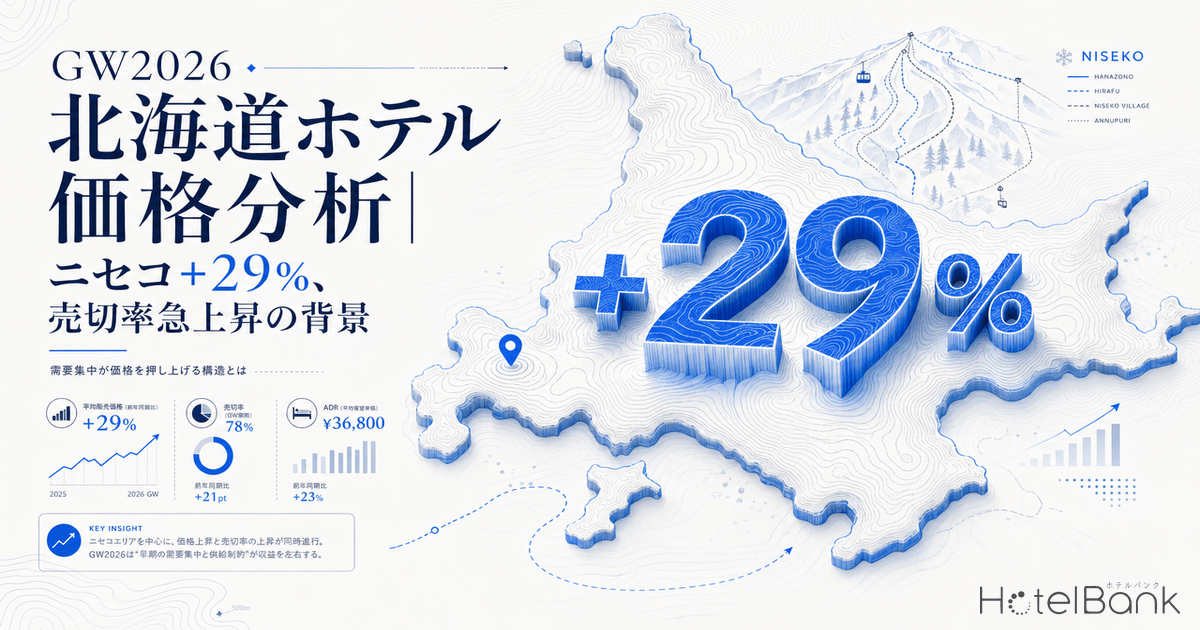
Our analysis of accommodation prices in Hokkaido during Golden Week 2026 (April 25 – May 6) reveals that the average room rate across the prefecture rose +7.7% year-on-year to ¥35,700. Within the prefecture, Kutchan Town (the heart of the Niseko area) recorded a striking +29.1% YoY rise during the GW period, with the peak day (May 2) jumping +35.2%. The drivers include the spillover of inbound demand into the spring season, a wave of new luxury resort openings, and a sharp rise in sellout rates. Drawing on N=1,703,077 plan-level price records, this article unpacks the price dynamics by area and property type.
Metric Definitions Used in This Article
- ADR (Average Daily Rate): The average of publicly listed sale prices on OTAs and similar channels. This differs from actual transacted prices. Per-room rate (tax included) for double occupancy, averaged across all plan types (room-only through plans with meals).
- Sellout Rate: The percentage of plans on OTAs that had stopped accepting reservations at the time of survey. This differs from the property-level occupancy rate.
- Data Source: MetroEngines Research
Hokkaido GW Price Trajectory: The Daily Wave of Supply and Demand
Looking at Hokkaido’s accommodation prices during GW 2026 (April 25 – May 6) on a daily basis, demand peaked on Friday May 2 at ¥47,000, a +36.3% jump from the previous year’s ¥34,500 on the same date. In contrast, prices fell sharply from May 5 onward in the latter half of GW, dropping from ¥36,300 to ¥30,200, with the gap from the peak day reaching as much as ¥16,800. Furthermore, sellout rates exceeded 20% on every day of the period in 2026, and on the peak day of May 3 the rate hit 41.5%, indicating a serious supply crunch.
Source: Compiled by HotelBank Editorial Team from MetroEngines Research (N=1,703,077)
Whereas the GW 2025 sellout rate was effectively 0%, the 2026 average climbed to 27.5%, indicating a significant shift in the supply-demand balance. In other words, the price increases are not driven by mere “rate hikes” but by inventory tightness stemming from genuine demand growth.
Price Movements by Area: Kutchan Town Stands Out at +29%
Comparing GW-period average prices across Hokkaido’s main areas on a YoY basis, the most striking gain was Kutchan Town (heart of the Niseko area) at +29.1%. With prices climbing from ¥43,900 to ¥56,700, the area has decisively shifted into the resort price tier. Otaru City followed at +19.5%, and Kushiro City at +19.3%, suggesting that rising visibility as tourism destinations and improved transport access are contributing factors.
Source: Compiled by HotelBank Editorial Team from MetroEngines Research
Not all areas saw gains, however. Furano City posted Hokkaido’s largest decline at -10.9% YoY, while Asahikawa City fell -5.2% and Niseko Town (adjacent to Kutchan Town) dropped -5.5%. The declines in Furano and Niseko Town may reflect renovations at some upscale properties as well as a demand shift within the area toward Kutchan Town.
| Area | GW 2025 | GW 2026 | YoY | Sellout (2026) | Sample Size |
|---|---|---|---|---|---|
| Toyako Town | ¥65,700 | ¥66,900 | +1.7% | 46.5% | N=18,271 |
| Noboribetsu City | ¥62,900 | ¥64,900 | +3.2% | 38.1% | N=34,151 |
| Kutchan Town (Niseko) | ¥43,900 | ¥56,700 | +29.1% | 19.0% | N=34,476 |
| Niseko Town | ¥48,500 | ¥45,800 | -5.5% | 22.6% | N=18,499 |
| Hakodate City | ¥39,900 | ¥42,900 | +7.6% | 35.4% | N=203,826 |
| Otaru City | ¥34,300 | ¥40,900 | +19.5% | 25.5% | N=64,723 |
| Kushiro City | ¥33,900 | ¥40,500 | +19.3% | 27.9% | N=57,693 |
| Furano City | ¥38,300 | ¥34,100 | -10.9% | 24.3% | N=32,450 |
| Sapporo City | ¥28,500 | ¥30,200 | +5.9% | 33.1% | N=622,828 |
| Asahikawa City | ¥21,000 | ¥19,900 | -5.2% | 23.1% | N=92,447 |
Source: Compiled by HotelBank Editorial Team from MetroEngines Research. *GW period = 12-day average from April 25 to May 6.
Structural Change in the Niseko Area: Premiumization and Supply Constraints
Behind Kutchan Town’s outsized +29.1% YoY price gain lies a structural transformation across the entire area. Between 2025 and 2026, the Niseko area has seen a string of luxury hotel openings. In 2025, Nikko Style Niseko HANAZONO, HOTEL LOGIN NISEKO, and Kassia Hirafu Niseko opened, and 2026 is set to bring openings of ultra-luxury brands including Six Senses Niseko (IHG group, 76 rooms) and Capella Niseko.
Yet the number of plans listed on OTAs and similar channels has actually declined. The GW-period sample size for Kutchan Town fell 16.4% from N=41,262 in 2025 to N=34,476 in 2026. This suggests luxury properties are reducing their reliance on OTA distribution and channeling sales toward their own websites and high-net-worth-focused channels. When supply tightens while demand grows, prices naturally rise: as a fundamental principle of dynamic pricing, shrinking inventory translates directly into upward price pressure.
In addition, three properties within Niseko Village (Kasara Niseko Village Townhouse, Hinode Hills Niseko Village, and The Green Leaf Niseko Village) have been rebranded under the Hilton group, which is believed to have boosted international visibility and direct bookings from overseas.
Price Movements by Property Type: Condominiums Surge
By property type, condominiums commanded the highest GW-period average price at ¥60,500, surging +57.2% from ¥38,500 a year earlier. This reflects the proliferation of condominium-style luxury accommodations in the Niseko area. Ryokan came in at ¥55,300 (+1.6% YoY), holding a relatively stable yet structurally high price point with only a modest rate of increase.
Source: Compiled by HotelBank Editorial Team from MetroEngines Research
The hotel category posted a solid ¥28,400 (+5.1% YoY) and registered the tightest supply-demand balance with a 30.0% sellout rate. That said, mid- and lower-tier price segments such as pensions (¥26,200, +9.8%) and youth hostels (¥17,100, +25.2%) also saw price gains, confirming that accommodation demand across Hokkaido is reaching a wide range of property types.
Inbound Demand Spilling into the Spring Season
Hokkaido’s inbound demand has historically been concentrated in the winter ski season (December – February). Recently, however, that demand window has been widening. According to the MLIT Hokkaido Transport Bureau Tourism Baseline Data (March 2026), foreign overnight visitor counts in Hokkaido continued to set record highs throughout fiscal 2025, with particularly notable gains in spring (April – May).
The trend is corroborated by the monthly operating data of REITs. The seven properties owned by Invincible Investment Corporation (8963) in the Sapporo area reported ADRs of ¥18,600 – ¥28,100 with occupancy of 93 – 96% as of February 2026, indicating that high winter demand has carried straight into the spring. Additionally, fav Hakodate held by Kasumigaseki Hotel REIT Investment Corporation (401A) recorded an ADR of ¥25,400 and 74.4% occupancy, reflecting expanding demand in the Hakodate area.
Hokkaido in spring offers a unique appeal: cherry blossoms bloom one to two months later than on Honshu, and visitors can enjoy lingering snow and fresh greenery side by side. For overseas travelers, “off-peak” Hokkaido immediately following the winter season feels like a value buy, and the overlap between GW and overseas spring demand has generated strong upward pressure on the lodging market.
Sellout Rate Surge Signals Tight Supply-Demand
The most notable shift in GW 2026 is the sharp rise in sellout rates. While the GW 2025 sellout rate for Hokkaido as a whole was 0.0%, the 2026 average jumped to 27.5%. By area, the highest were Toyako Town (46.5%), Noboribetsu City (38.1%), Hakodate City (35.4%), and Sapporo City (33.1%) – revealing especially tight inventory in onsen towns and urban centers.
Source: Compiled by HotelBank Editorial Team from MetroEngines Research
On a daily basis, the sellout rate peaked at 41.5% on Saturday May 3, indicating a serious supply shortage on GW’s main peak day. This means a meaningful volume of latent demand from would-be guests who could not secure a reservation. That latent demand was likely absorbed by spillover into surrounding areas or by switching to day trips.
Note on Mixed Data Sources: This article uses both OTA-listed price data (sale-price basis) and REIT monthly operating data (transacted-price basis). Because the two have a structural level gap, please focus on the YoY (year-on-year) rates of change rather than direct comparisons of absolute values.
REIT Data Confirms Hokkaido’s Underlying Lodging Strength
Monthly operating data from hotel-focused REITs further confirms the strength of Hokkaido’s lodging market. Looking at February 2026 figures, the Sapporo and Otaru properties owned by Invincible Investment Corporation are operating at uniformly high occupancy: Hotel MyStays Sapporo Aspen reported ADR ¥28,100 / 96.1% occupancy, and Hotel Sonia Otaru ADR ¥24,400 / 94.0% occupancy – all at exceptionally high levels.
| REIT / Property | ADR | Occupancy | RevPAR |
|---|---|---|---|
| Invincible Investment Corporation (8963) | |||
| Hotel MyStays Sapporo Aspen | ¥28,100 | 96.1% | ¥27,000 |
| Hotel MyStays Sapporo Station North | ¥24,200 | 96.1% | ¥23,200 |
| Hotel Sonia Otaru | ¥24,400 | 94.0% | ¥23,000 |
| Hotel Nord Otaru | ¥23,900 | 96.0% | ¥22,900 |
| Hotel MyStays Premier Sapporo Park | ¥18,800 | 93.1% | ¥17,500 |
| Art Hotel Asahikawa | ¥16,500 | 88.3% | ¥14,600 |
| Hakodate Kokusai Hotel | ¥12,700 | 72.0% | ¥9,100 |
| Kasumigaseki Hotel REIT Investment Corporation (401A) | |||
| fav Hakodate | ¥25,400 | 74.4% | ¥18,900 |
| Ichigo Hotel REIT Investment Corporation (3463) | |||
| Comfort Hotel Kushiro | ¥7,900 | 85.7% | ¥6,700 |
| Hoshino Resorts REIT Investment Corporation (3287) | |||
| Hotel WBF Grande Asahikawa | ¥16,300 | 90.4% | ¥14,700 |
Source: Compiled by HotelBank Editorial Team from each REIT’s monthly operating data (February 2026 actuals)
It is particularly noteworthy that Sapporo hotels are uniformly operating above 90% occupancy. Although February is typically the peak of the winter tourism season, this level being sustained into the GW period aligns with Sapporo City’s 33.1% sellout rate for GW 2026. While property-level REIT data is published on a monthly basis and does not include GW-period spot data, it serves as useful supplementary evidence corroborating the structural high-demand trend.
Conclusion: Hokkaido’s GW Market at the Pivot from “Volume” to “Value”
The GW 2026 Hokkaido lodging market posted a solid +7.7% YoY overall gain. The picture beneath the headline differs sharply by area, however. While areas like Kutchan Town (Niseko core) at +29.1%, Otaru at +19.5%, and Kushiro at +19.3% delivered double-digit increases, others such as Furano (-10.9%) and Asahikawa (-5.2%) declined.
This polarization reflects the spillover of inbound demand into the spring season together with the lift in price tier driven by new luxury resort openings. The Niseko area in particular continues to attract international luxury brands such as Six Senses and Capella, structurally elevating the area’s overall ADR. Meanwhile, areas without concentrated demand have seen price declines, underscoring an increasingly uneven distribution of demand within Hokkaido.
The sharp rise in sellout rates (from 0% in 2025 to 27.5% in 2026) signals that supply shortages are becoming visible. How the wave of upcoming new openings will reshape the supply-demand balance is the next focal point. Hokkaido’s lodging market is arguably entering a transition from “expanding volume” to “elevating quality.”
Note on Forward-Dated ADR: The ADR figures in this article reflect average sale prices listed on OTAs at the time of survey and will fluctuate as check-in dates approach. Please note that prices currently set high may decline through last-minute discounting.